


EN
Freeport-McMoRan (FCX) Drops On Downgrade, Is It A Bargain Or Fully Valued?
Freeport-McMoRan (FCX) came under pressure after Erste Group shifted its rating to Hold from Buy. The move was tied to concerns about copper and gold volumes and valuation, and the stock dropped 7.09%.
The downgrade comes after a weak recent stretch for Freeport-McMoRan, with the share price falling 17.18% over the last week and 26.24% over the past month. The 1-year total shareholder return of 25.89% still keeps the longer track record positive.
Scan how Freeport-McMoRan compares to other miners facing similar volume and pricing pressures by reviewing a curated set of 16 top copper producer stocks.
After a 26% slide in a month, Freeport-McMoRan now trades on very different terms than it did in October. Does that reset finally tilt the risk reward back toward buyers, or not yet?
Most Popular Narrative: 35% Undervalued
On the analyst consensus Narrative on Simply Wall St, Freeport-McMoRan screens as undervalued, with a fair value of $79.07 against the latest close at $51.45. That framework leans heavily on copper growth projects and margin improvement to justify the gap.
The Bagdad expansion in Arizona, now estimated at about US$4.5b of capital and expected to make Bagdad one of the largest U.S. copper mines while still meeting internal return thresholds at a long term copper price assumption of US$4 per pound, represents a sizeable brownfield project that could increase future production volumes and support Freeport-McMoRan’s longer term earnings power.
See why 120 investors see Freeport-McMoRan as 35% undervalued.
Result: Fair Value of $79.07 (UNDERVALUED)
Still, the Freeport-McMoRan story can break if Grasberg or the new Indonesian smelter run into fresh delays, or if project costs keep climbing.
Find out about the key risks to this Freeport-McMoRan narrative.
Another View On Freeport-McMoRan’s Valuation
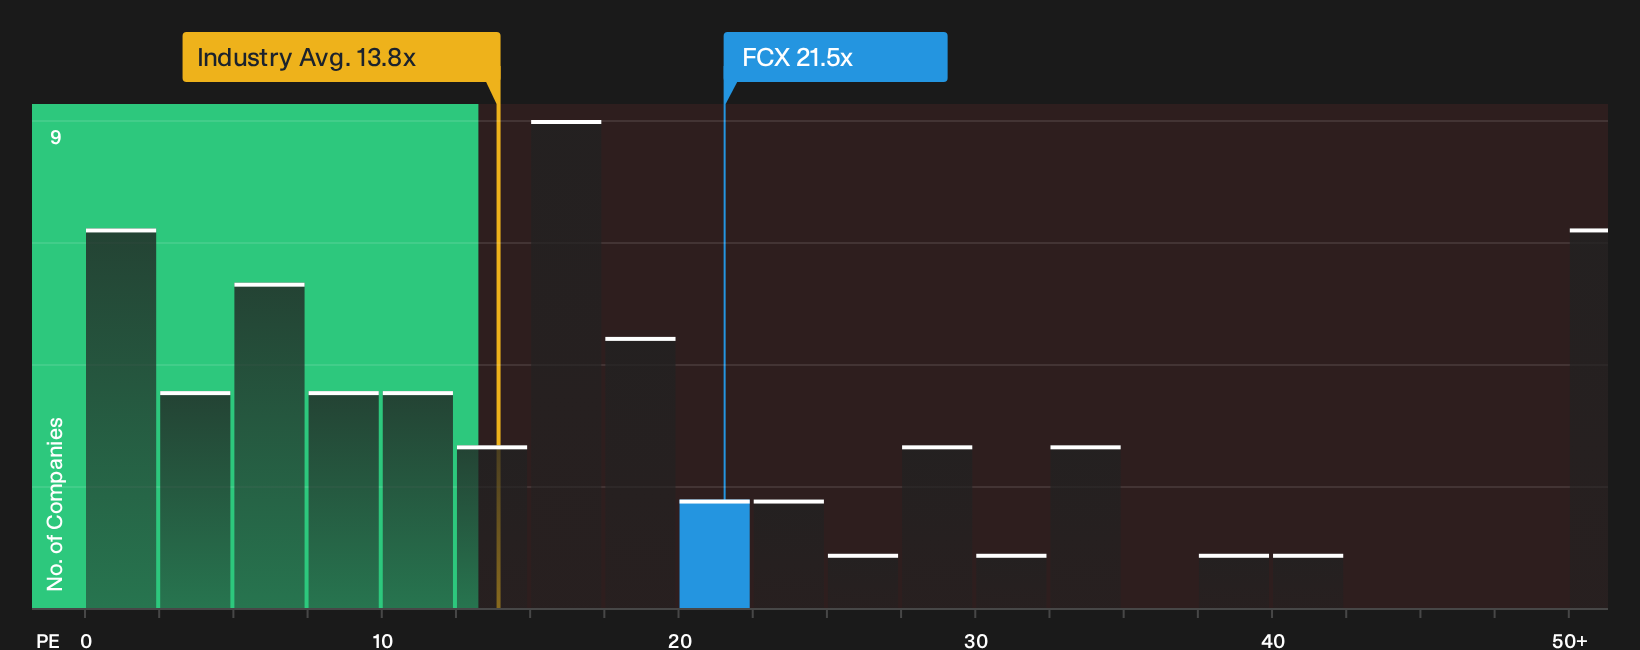
Those analyst fair values lean on earnings forecasts and price targets. A different lens comes from simple P/E math. Freeport-McMoRan trades on 21.5x earnings versus 13.8x for the US metals and mining group and an estimated fair ratio of 23.9x. This raises a clear question: is that premium a margin of safety or a margin for error?
To see how those earnings multiples stack up against both peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this Freeport-McMoRan story is mixed, so move quickly, review the same valuation and risk data yourself, and then balance those concerns against 2 key rewards
Looking For More Investment Ideas Beyond Freeport-McMoRan?
If the Freeport-McMoRan setup has you reassessing risk and reward, use that same discipline to scan fresh opportunities that might fit your portfolio even better.
- Target stronger upside potential by reviewing a focused group of 19 high quality undiscovered gems that combine quality fundamentals with lower market attention.
- Strengthen portfolio resilience by assessing a list of solid balance sheet and fundamentals (24 results) that can better withstand funding stress or earnings volatility.
- Reduce downside shocks by filtering for a 30 resilient stocks with low risk scores that aligns with steadier business models and cleaner financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com