


EN
Is Alphabet Stock a Buy Right Now?
Key Points
Alphabet posted negative free cash flow in the third quarter because of surging AI-related spending.
Google Cloud is the fastest-growing of the "big three" cloud providers, outpacing AWS and Azure.
Alphabet's stock is trading well below its historical average (based on P/E ratio).
It has been a rough year for the "Magnificent Seven" stocks as a whole, with four in the negative for the year through market close on Nov. 13. Among the four is Google's parent company Alphabet (NASDAQ:GOOG)(NASDAQ:GOOGL), which is down 5.5%, including a 12.6% single-day drop on Oct. 29 that saw the company lose more value in one day than ever before in its history.
With Alphabet in the red and underperforming (the S&P 500 is up 10.5%), is now a good time to invest in the stock, or should investors take it as a warning sign and steer clear of a falling knife?
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Getty Images.
Why Alphabet's stock has struggled
Alphabet's stock struggles this year are more about how much it's spending than how much it's making. In the third quarter, Alphabet made $127.6 billion in revenue, up 25% year over year, and its operating income (profit from its core business) increased nearly 30% to $40.6 billion.
Unfortunately, Alphabet's free cash flow was negative, with a $9.1 billion deficit, because of high capital expenditures (capex). It spent $51.4 billion in the quarter, most of it on AI-related projects (data centers, custom chips, and other infrastructure).
High spending has been the recent norm for hyperscalers like Alphabet, Amazon (NASDAQ:AMZN), Microsoft (NASDAQ:MSFT), and Meta Platforms (NASDAQ:META), but it's easy to see why investors value free cash flow. That's money used for things like dividends, share buybacks, and other investments.
The spending isn't expected to slow down anytime soon, either. Alphabet projects total 2026 capex of between $195 billion and $205 billion, more than doubling what it spent last year.
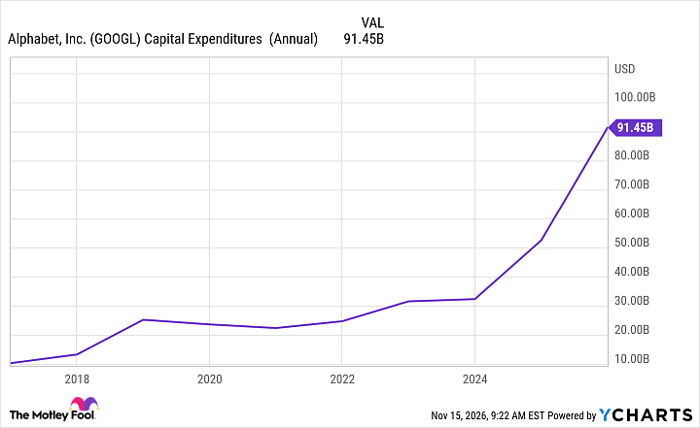
GOOGL Capital Expenditures (Annual) data by YCharts
Is Alphabet a buy right now?
Alphabet has a trifecta working in its favor. First, it has a thriving Google Cloud business that increased revenue 103% to $30.7 billion in Q3. Google Cloud still trails Amazon Web Services and Microsoft Azure in market share (and likely will for the foreseeable future), but it's growing much faster than both.
Cloud progress is one of the clearest indicators of whether a company is seeing a return on its AI investments. Although we're still a ways away from any hyperscaler seeing a clear return on investment, triple-digit growth is encouraging.
The second thing working in Alphabet's favor is a virtual monopoly in Google Search, with a 91% market share. Google Search revenue has slowed over the past couple of quarters, but it still generated $63.4 billion of revenue (up 12%), with elite margins. Alphabet is still working through balancing traditional search and AI convenience, but I don't see that as a long-term issue.
The third thing working in Alphabet's favor -- and why it's especially looking like a buy right now -- is how cheap the stock is at the moment, trading at 15.4 times its earnings. It's not only the cheapest of the "Magnificent Seven" stocks, but also well below the 23.5 it has averaged over the past five years.
At its current valuation, Alphabet has far more upside than downside for long-term investors.
Stefon Walters has positions in Microsoft. The Motley Fool has positions in and recommends Alphabet, Amazon, Meta Platforms, and Microsoft. The Motley Fool has a disclosure policy.