


EN
Should Vaccine Medium Launch Require Action From Thermo Fisher Scientific (TMO) Investors?
- Thermo Fisher Scientific recently launched Gibco VaxEvo CD 293 Medium, a chemically defined, animal origin free solution for suspension HEK293 cultures that is designed to support high titer adenovirus production for vaccine developers across liquid and AGT formats.
- The medium targets a practical bottleneck in adenovirus vaccine workflows by aiming to pair robust HEK293 cell growth with simplified, feed free upstream processes for human and animal health manufacturers.
- Next, the focus shifts to what this new HEK293 vaccine medium could mean for Thermo Fisher Scientific broader investment narrative.
Scan how Thermo Fisher Scientific fits into the broader vaccine and health science story by sizing it up against hand-picked peers in the list of solid balance sheet and fundamentals (24 results).
Thermo Fisher Scientific Investment Narrative Recap
To own Thermo Fisher Scientific, you need to believe the business can keep turning its large tools and services footprint into steadier earnings, even while academic and government demand stays muted. The analyst consensus narrative on Simply Wall St focuses on pharma and biotech customers, bioproduction and higher value instruments to do that heavy lifting. The new VaxEvo CD 293 Medium fits that story but appears incremental rather than a major factor for near term results.
The bigger near term swing still depends on how quickly funding-sensitive customers recover and how effectively Thermo Fisher Scientific executes its portfolio reshaping, including the microbiology divestiture. If funding remains softer than expected or divestiture proceeds and reinvestment underwhelm, the risk is that margin expansion and earnings growth prove harder to deliver than analysts currently include in their models.
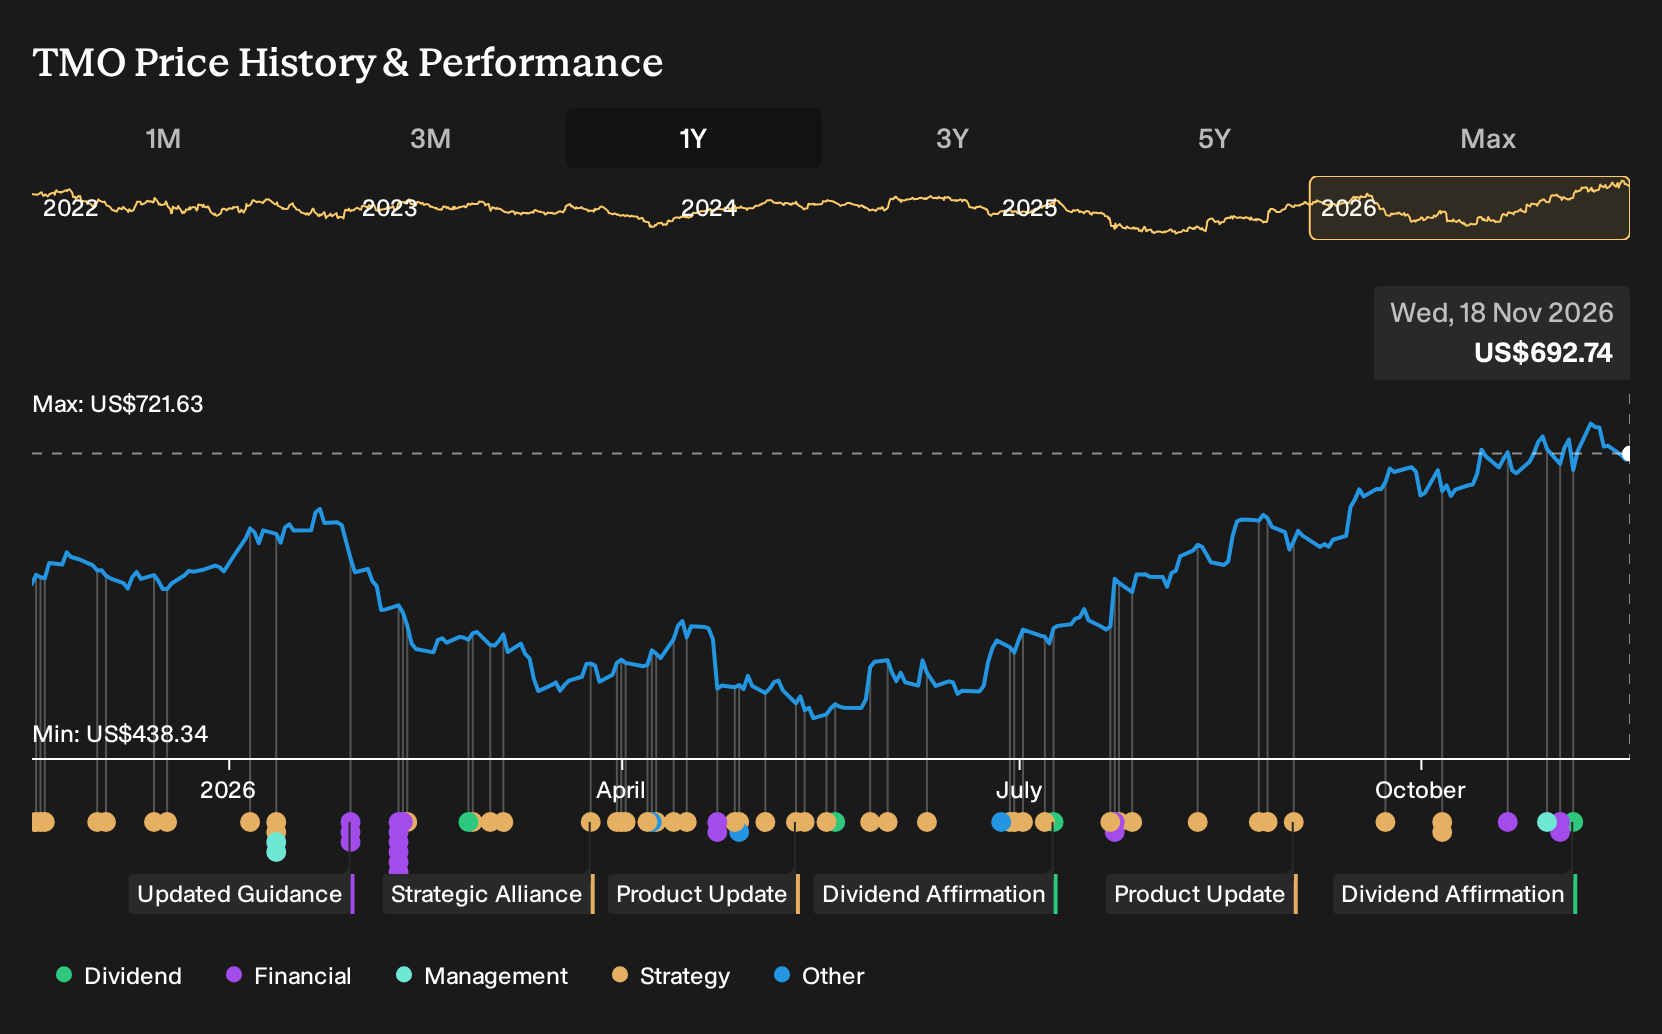
Among the recent items, the quarterly dividend affirmation of US$0.47 a share is most relevant alongside VaxEvo. It indicates the board is comfortable returning cash while the firm invests in areas such as higher end media for HEK293 vaccine work, clinical trial logistics and bioproduction capacity. For you as a shareholder, that suggests a management team trying to balance reinvestment needs with regular cash returns.
The dividend itself is unlikely to move the stock by much, but it highlights capital allocation as one of the key execution levers from here, alongside M&A and debt management. If Thermo Fisher Scientific continues to fund product launches like VaxEvo, integrate deals such as Clario and Solventum and still support the payout, that combination could be more important for the medium term catalyst path than any single product launch.
Thermo Fisher Scientific's current narrative assumes revenue of US$56.1b and earnings of US$10.7b by 2029, built on 5.8% yearly top line growth and an earnings increase of about US$3.6b from US$7.1b today.
Uncover why Thermo Fisher Scientific's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame Thermo Fisher Scientific quite differently. They lean on higher margin potential from platforms like digital CMC and AI rich clinical services, and were already modelling revenue of about US$57.8b and earnings of US$12.3b by 2029. You can use the VaxEvo news to test whether those pre news assumptions still feel realistic.
Explore 4 other Thermo Fisher Scientific fair value estimates, including one that suggests as much as 20% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Thermo Fisher Scientific research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Thermo Fisher Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thermo Fisher Scientific's overall financial health at a glance.
Looking For More Ideas Beyond Thermo Fisher Scientific?
If you want to put Thermo Fisher Scientific in context, it helps to size it up alongside other high quality businesses and see how different balance sheets, dividends and valuations compare side by side.
- For investors who care most about resilient finances and cleaner balance sheets, start by scanning a list of solid balance sheet and fundamentals (24 results) that filters for companies with stronger fundamentals.
- If your focus is on cash returns, income focused investors can review a 8 dividend fortresses that highlights businesses offering higher yields with an emphasis on sustainability.
- Looking for opportunities where quality and price still seem to line up, you can comb through a 35 high quality undervalued stocks that surfaces stocks flagged as both financially robust and potentially mispriced.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com