


EN
Palo Alto Networks beats expectations in strong Q3 CY2026, stock jumps 12.7%
Cybersecurity platform provider Palo Alto Networks (NASDAQ:PANW) beat Wall Street’s revenue expectations in calendar Q3 2026 [fiscal Q1 2027], with revenue up 39.2% year on year to $3.45 billion. In addition, next quarter’s revenue guidance ($3.54 billion at the midpoint) was stronger than expected, at 3.8% above analysts’ consensus estimates. Its non-GAAP profit of $1.05 per share was 8.2% above analysts’ consensus estimates.
For more on Palo Alto Networks, read the full research report for free.
Palo Alto Networks Q3 CY2026 highlights:
- Revenue $3.45 billion vs analysts’ consensus estimates of $3.31 billion, according to S&P (39.2% year-on-year growth, 4.2% beat)
- Adjusted EPS $1.05 vs analysts’ consensus estimates of $0.97, according to S&P (8.2% beat)
- Adjusted operating income $1.06 billion vs analysts’ consensus estimates of $968.3 million (30.7% margin, 9.4% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $14.55 billion at the midpoint from $14.15 billion, a 2.8% increase
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $4.28 at the midpoint, a 2.5% increase
- Operating margin 2.8%, down from 12.5% in the same quarter last year
- Free cash flow margin 58.5%, up from 36.8% in the previous quarter
- Market capitalization $252.6 billion
"We had a strong start to the year with a record Q1 and delivered one of our highest NGS ARR beats ever as our customers turn to us to protect them against an unprecedented threat environment," said Nikesh Arora, chairman and chief executive officer of Palo Alto Networks. "As AI reshapes the threat landscape, we must continually evolve to protect our customers and enable them to adopt AI securely. To that end, we are pleased to announce our intent to acquire Applied Compute, which will allow us to deliver secure open weight models to our customers and accelerate the adoption of enterprise AI."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Palo Alto Networks’s revenue grew at a solid 22.3% compounded annual growth rate over the last five years. Its growth surpassed the average software company and shows its offerings resonate with customers.
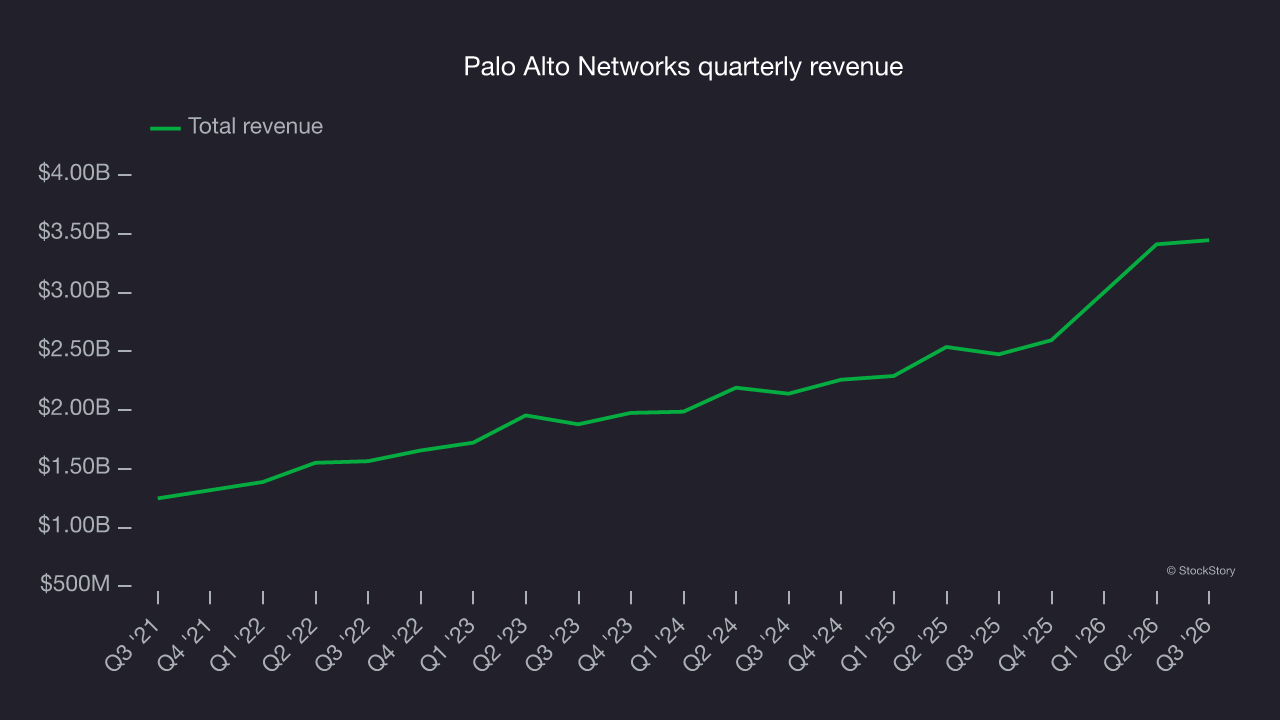
Long-term growth is the most important, but within software, a half-decade historical view may miss new innovations or demand cycles. Palo Alto Networks’s annualized revenue growth of 22.6% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 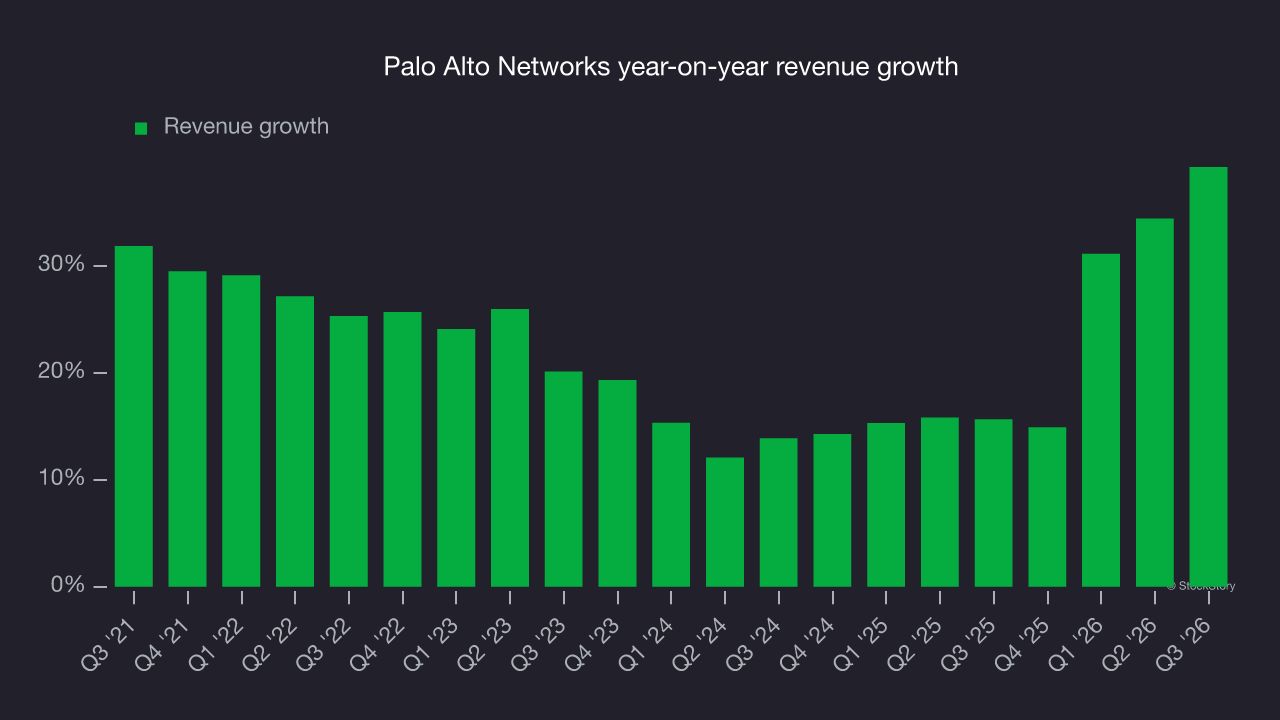
This quarter, Palo Alto Networks reported strong year-on-year revenue growth of 39.2%, and its $3.45 billion of revenue exceeded Wall Street’s consensus estimates by 4.2%. Management is guiding for a 36.5% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 17.5% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, its growth trajectory is attractive given its scale and suggests the market is forecasting success for its products and services.
Customer acquisition efficiency
The customer acquisition cost, or CAC, payback period measures the months a company needs to recoup the money spent on acquiring a new customer. This metric helps assess how quickly a business can break even on its sales and marketing investments.
Palo Alto Networks is very efficient at acquiring new customers, and its CAC payback period was 17.5 months this quarter. The company’s rapid recovery of its customer acquisition costs indicates it has a highly differentiated product offering and a strong brand reputation due to its scale. These dynamics give Palo Alto Networks more resources to pursue new product initiatives while maintaining the flexibility to increase its sales and marketing investments. 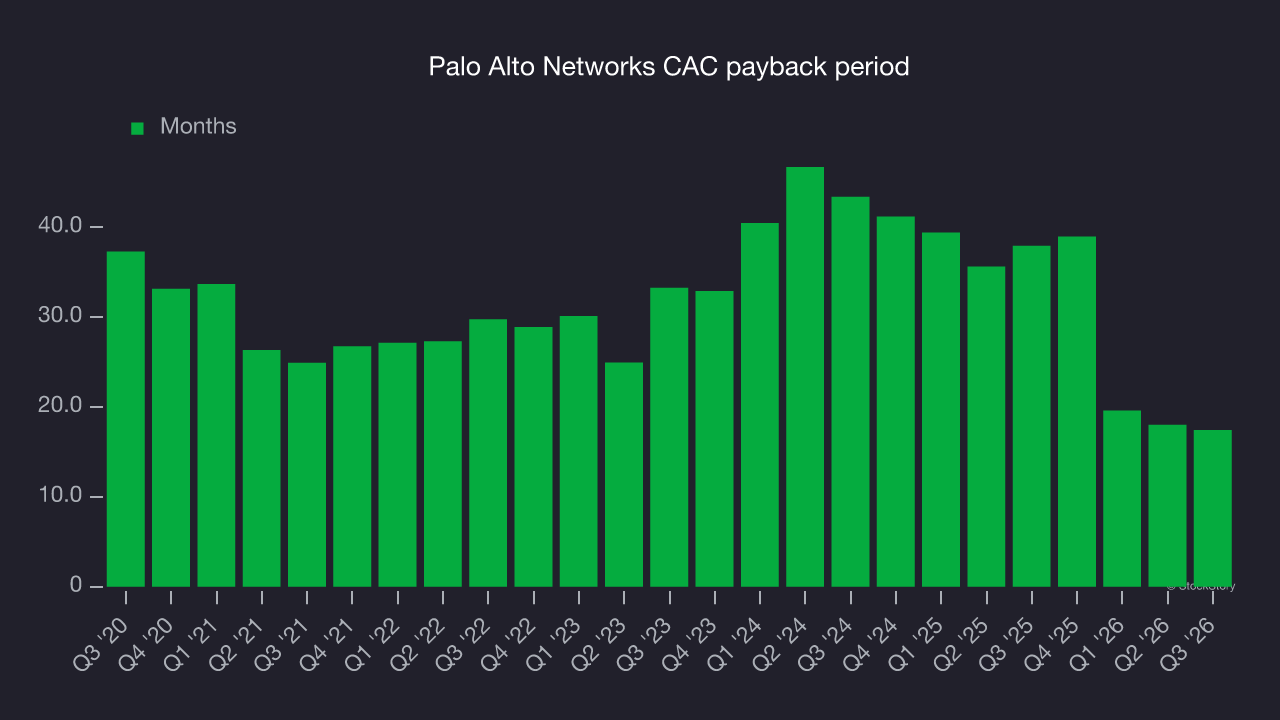
Key takeaways from Palo Alto Networks’s Q3 results
An adjusted operating income beat and upbeat full-year EPS guidance made this a strong quarter for Palo Alto Networks. Operating income came in well ahead of analysts’ consensus estimates, and the EPS outlook topped Wall Street’s consensus. Shares soared 12.7% to $380.64 immediately after the results.
Palo Alto Networks may have had a good quarter, but does that mean the stock is a buy? The latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our full research report, which you can read here (it’s free).