


EN
Everpure reports upbeat Q3 CY2026, stock soars
Data storage solutions provider Everpure (NYSE:P) announced better-than-expected revenue in calendar Q3 2026 [fiscal Q3 2027], as revenue rose 51.4% year on year to $1.46 billion. Guidance for next quarter’s revenue was better than expected at $1.51 billion at the midpoint, 1.4% above analysts’ consensus estimates. Its non-GAAP profit of $0.86 per share was 10.8% above analysts’ consensus estimates.
For more on Everpure, read our full research report for free.
Everpure Q3 CY2026 highlights:
- Revenue $1.46 billion vs S&P analysts’ consensus estimates of $1.33 billion (51.4% year-on-year growth, 9.5% beat)
- Adjusted EPS $0.86 vs S&P analysts’ consensus estimates of $0.78 (10.8% beat)
- Revenue guidance $1.51 billion at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $1.49 billion
- Operating margin 10.3%, up from 5.6% in the same quarter last year
- Free cash flow margin 18.1%, up from 5.5% in the same quarter last year
- Market capitalization $33.92 billion
"The strength of our Q3 results reinforces Everpure's role as the trusted partner customers rely on for their most critical data infrastructure," said Charles Giancarlo, Chairman and CEO of Everpure. "As organizations work to break down data silos and modernize their data estates, our growth across both core and new, high-growth markets shows we are uniquely equipped to solve their most complex data challenges at scale."
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Everpure’s 19.2% annualized revenue growth over the last five years was strong. Its growth surpassed the average business services company and shows its offerings resonate with customers.
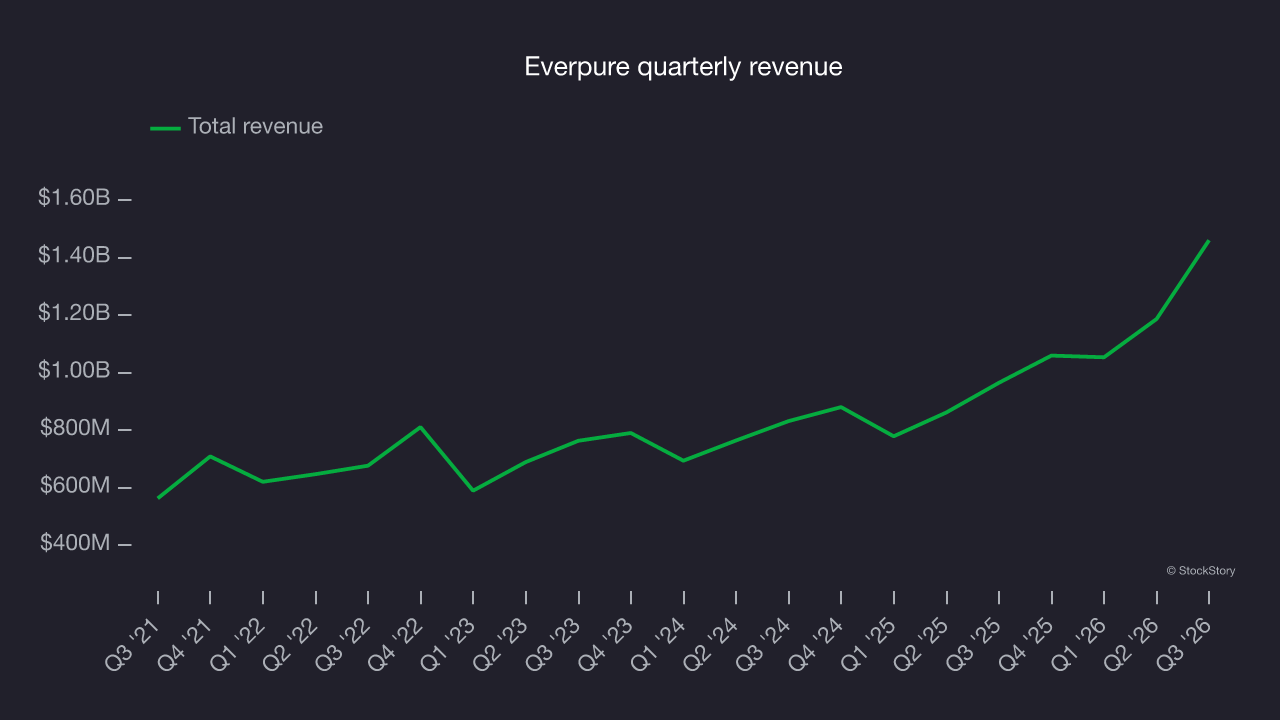
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Everpure’s annualized revenue growth of 24.3% over the last two years is above its five-year trend, suggesting demand was strong and recently accelerated. 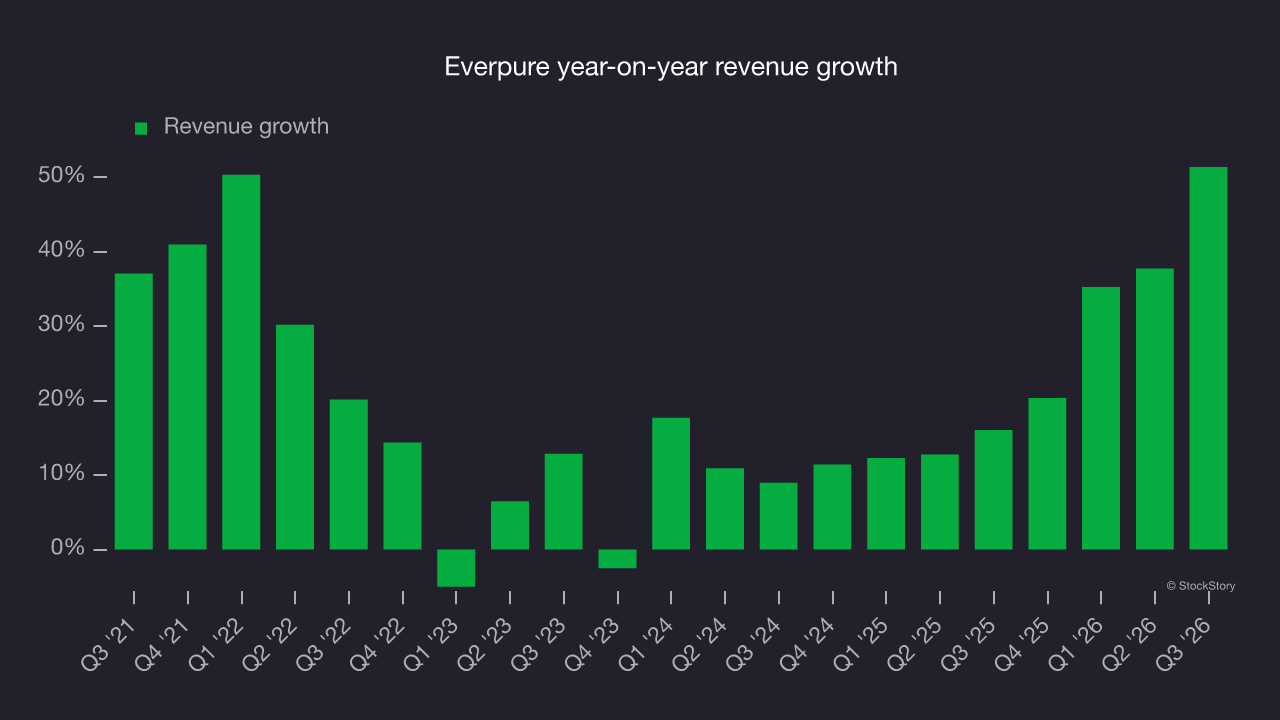
This quarter, Everpure reported year-on-year revenue growth of 51.4%, and its $1.46 billion of revenue beat Wall Street’s consensus estimates by 9.5%. Management is guiding for a 42.6% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 35.1% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection implies its newer products and services will drive better revenue performance.
Adjusted operating margin
Everpure has been an efficient company over the last five years. It was one of the more profitable businesses in the business services sector, with an average adjusted operating margin of 17.6%.
Everpure’s adjusted operating margin rose by 4.3 percentage points over the last five years, as its revenue growth gave it operating leverage.
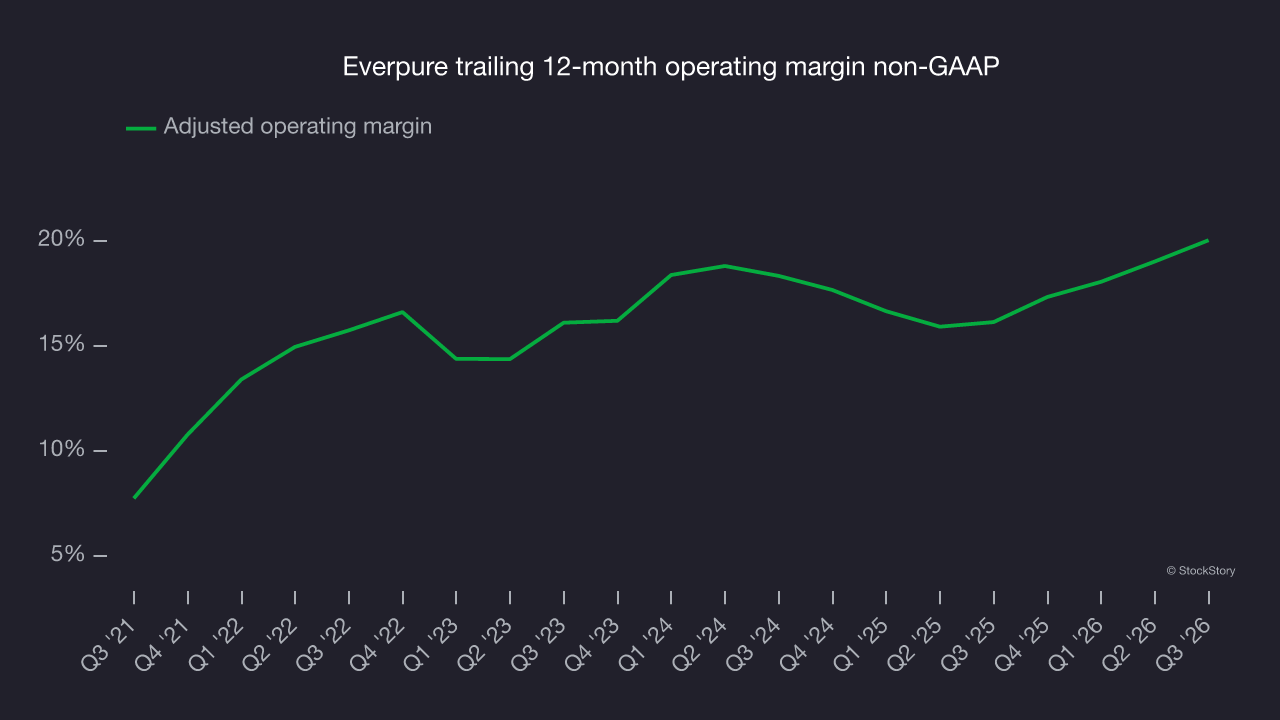
This quarter, Everpure generated an adjusted operating profit margin of 23.2%, up 2.8 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Everpure’s EPS grew at a 40.9% compounded annual growth rate over the last five years, higher than its 19.2% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
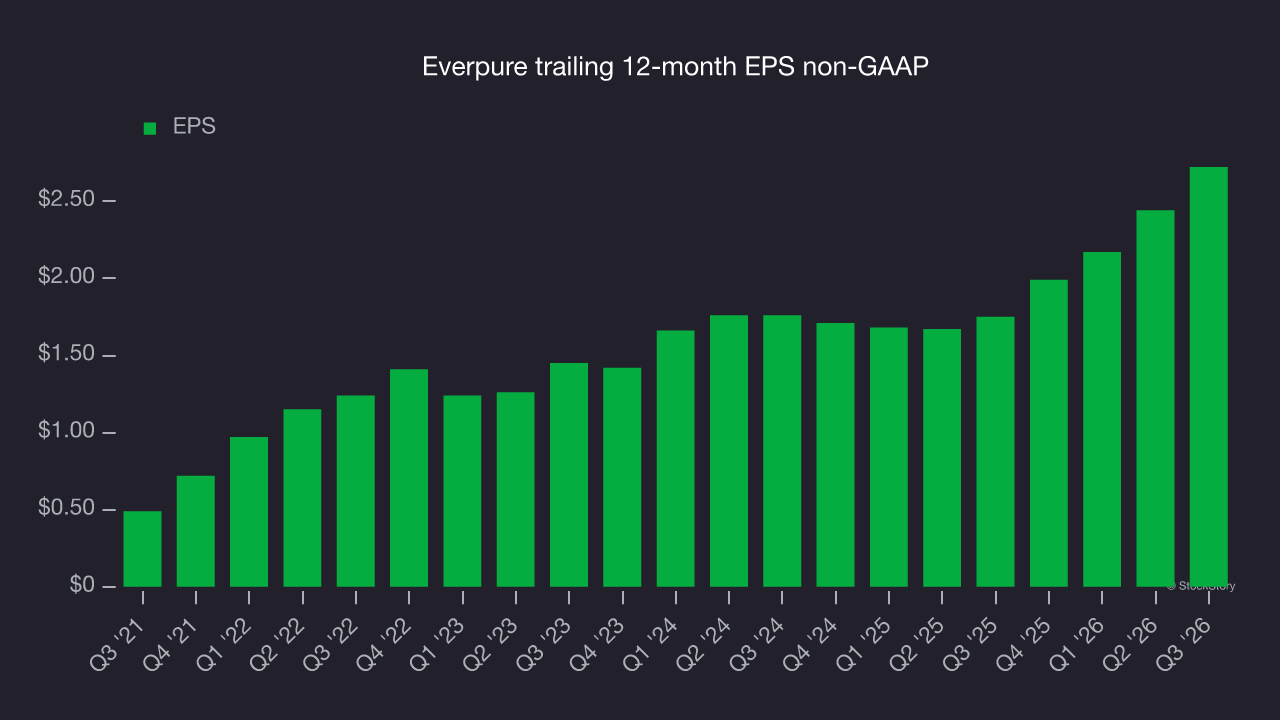
We can take a deeper look into Everpure’s earnings to better understand the drivers of its performance. As we mentioned earlier, Everpure’s adjusted operating margin expanded by 4.3 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Everpure’s two-year annual EPS growth of 24.3% was lower than its five-year trend. Even so, growth remained solid, and a future acceleration would be a positive.
In Q3, Everpure reported adjusted EPS of $0.86, up from $0.58 in the same quarter last year. The result easily cleared analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Everpure’s full-year EPS to grow 34.9% from $2.72 to $3.67, according to S&P.
Key takeaways from Everpure’s Q3 results
Revenue led the positives in Everpure’s Q3 results, coming in well ahead of analysts’ consensus estimates, and EPS also topped Wall Street’s estimates. Those beats made for a strong quarter. Shares surged 5.3% to $104.53 immediately after the release.
Everpure reported solid quarterly earnings, but is the stock a good investment at this price? The latest quarter matters, but longer-term fundamentals and valuation matter much more when deciding whether the stock is a buy. For more on Everpure, read the full research report here (it’s free).