


EN
Kulicke and Soffa delivers strong Q3 numbers, inventory levels improve
Semiconductor production equipment company Kulicke & Soffa (NASDAQ: KLIC) beat Wall Street’s revenue expectations in calendar Q3 2026 [fiscal Q4 2026], with revenue up 131% year on year to $410.3 million. In addition, next quarter’s revenue guidance ($410 million at the midpoint) was surprisingly strong, coming in 7.9% above analysts’ consensus estimates. Its non-GAAP profit of $1.52 per share was 6.3% above analysts’ consensus estimates.
For more on Kulicke and Soffa, read our free full research report.
Kulicke and Soffa Q3 CY2026 highlights:
- Revenue $410.3 million vs S&P analysts’ consensus estimates of $377.7 million (131% year-on-year growth, 8.6% beat)
- Adjusted EPS $1.52 vs S&P analysts’ consensus estimates of $1.43 (6.3% beat)
- Adjusted operating income $96.5 million vs analysts’ consensus estimates of $93.23 million (23.5% margin, 3.5% beat)
- Revenue guidance $410 million at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $380 million
- Adjusted EPS guidance $1.65 at the midpoint for Q4 CY2026, above analysts’ consensus estimates of $1.43
- Operating margin 21.2%, up from 0.5% in the same quarter last year
- Free cash flow margin 3.6%, up from 2.5% in the same quarter last year
- Inventory days outstanding 101, down from 120 in the previous quarter
- Market capitalization $3.43 billion
Raj Talluri, Kulicke & Soffa's president and chief executive officer, stated, "I look forward to bringing greater focus and leading the Company through its next phase of growth. This has been a tremendous quarter for many reasons – we delivered strong financial results, core wire bonding demand is resilient, our technology is evolving with AI, Data Center and Advanced Packaging trends, and we have additional visibility within our growing Advanced Solutions portfolio."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Kulicke and Soffa struggled to consistently generate demand over the last five years as its revenue dropped at a 4.9% annual rate, falling short of our standards and signaling poor business quality. Semiconductors are a cyclical industry, and long-term investors should be prepared for periods of high growth followed by periods of revenue contractions.
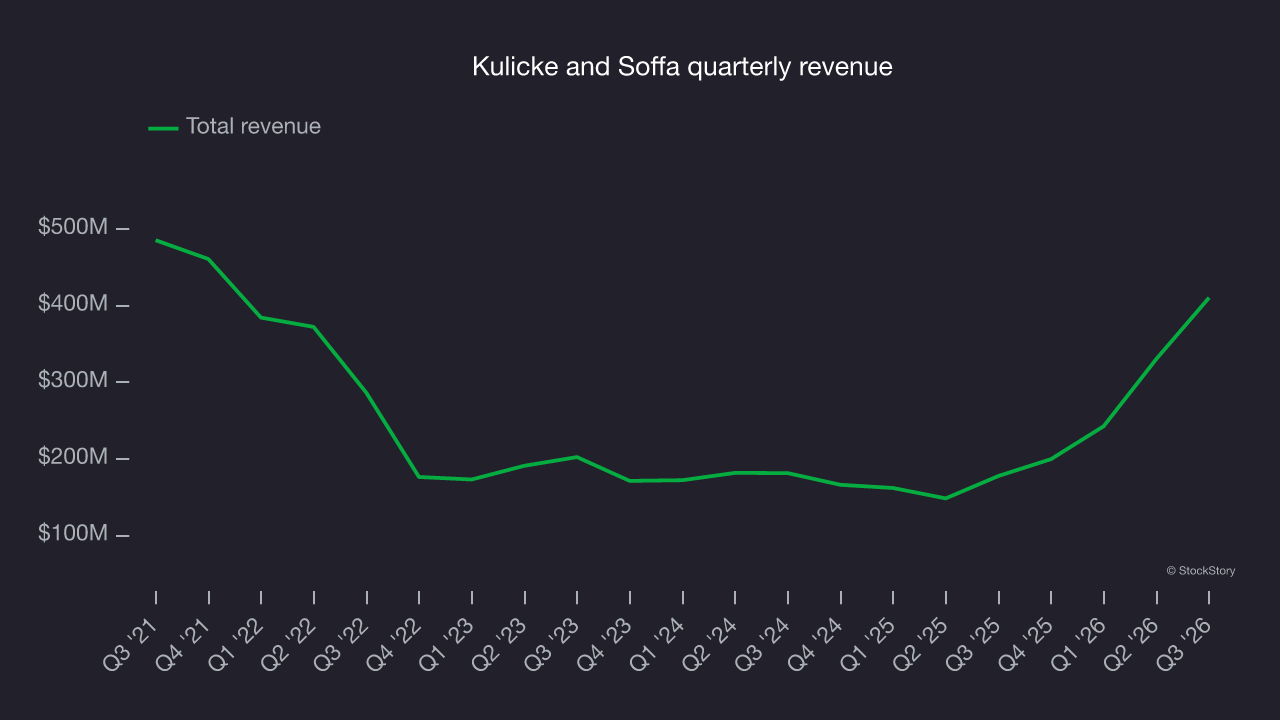
Long-term growth is the most important, but short-term results matter for semiconductors because the rapid pace of technological innovation (Moore’s Law) could make yesterday’s hit product obsolete today. Kulicke and Soffa’s annualized revenue growth of 29.4% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 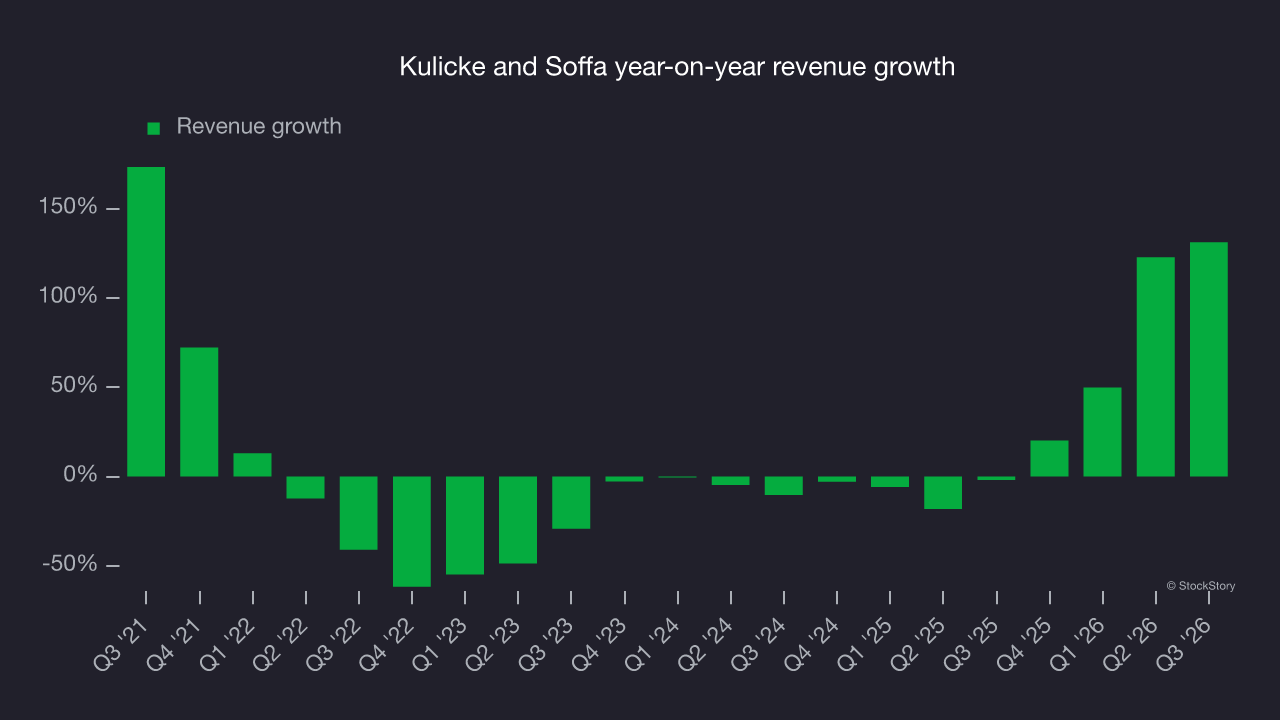
This quarter, Kulicke and Soffa reported year-on-year revenue growth of 131%, and its $410.3 million of revenue beat Wall Street’s consensus estimates by 8.6%. Beyond the beat, this marks 4 consecutive quarters of growth, implying that Kulicke and Soffa is in the middle of its cycle – a typical upcycle generally lasts 8 to 10 quarters. Company management is guiding for a 105% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 34.5% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is above average for the sector and suggests its newer products and services will catalyze better top-line performance.
Product demand & outstanding inventory
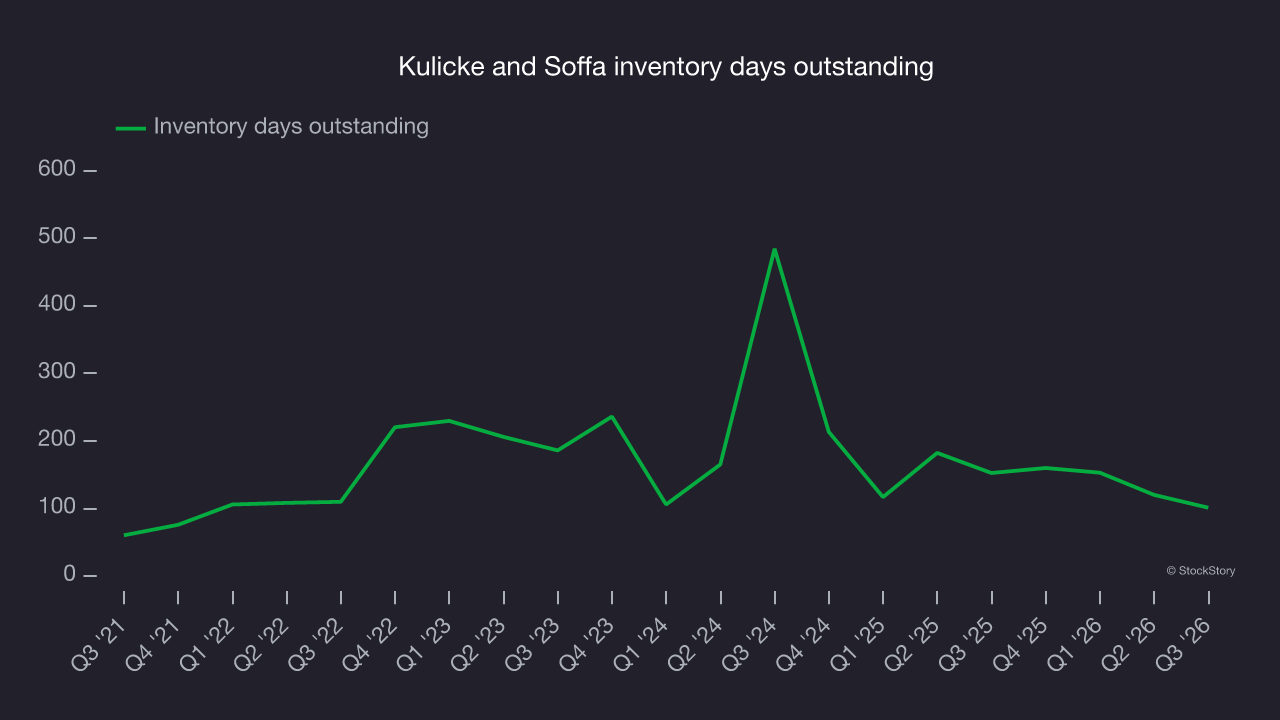
Days inventory outstanding, or DIO, is an important metric for chipmakers, as it reflects a business’s capital intensity and the cyclical nature of semiconductor supply and demand. In a tight supply environment, inventories tend to be stable, allowing chipmakers to exert pricing power. Steadily increasing DIO can be a warning sign that demand is weak, and if inventories continue to rise, the company may have to reduce production.
This quarter, Kulicke and Soffa’s DIO came in at 101, which is 70 days below its five-year average. These figures show no indication of an excessive inventory buildup.
Key takeaways from Kulicke and Soffa’s Q3 results
A wide revenue beat versus Wall Street’s consensus and a marked improvement in inventory levels were the key positives in Kulicke and Soffa’s quarter. Shares rose 4.7% to $67.99 immediately after the results.
Kulicke and Soffa had a solid quarterly earnings result, but is the stock a good investment? When making that decision, it’s important to consider its valuation and business quality as well as the latest quarter. For more, read our full research report here (it’s free).