


EN
Palo Alto Networks (PANW) Stock Gains as AI-Driven Cyberattacks Take Center Stage
Palo Alto Networks (PANW) shares are pushing higher on Nov. 18 after two U.S. senators and the DHS Secretary warned that artificial intelligence (AI)-enabled threats were advancing faster than the country’s defenses, boosting the need for advanced cybersecurity companies. PANW is in focus also because the cybersecurity firm is scheduled to report earnings for its fiscal first quarter today after market close.
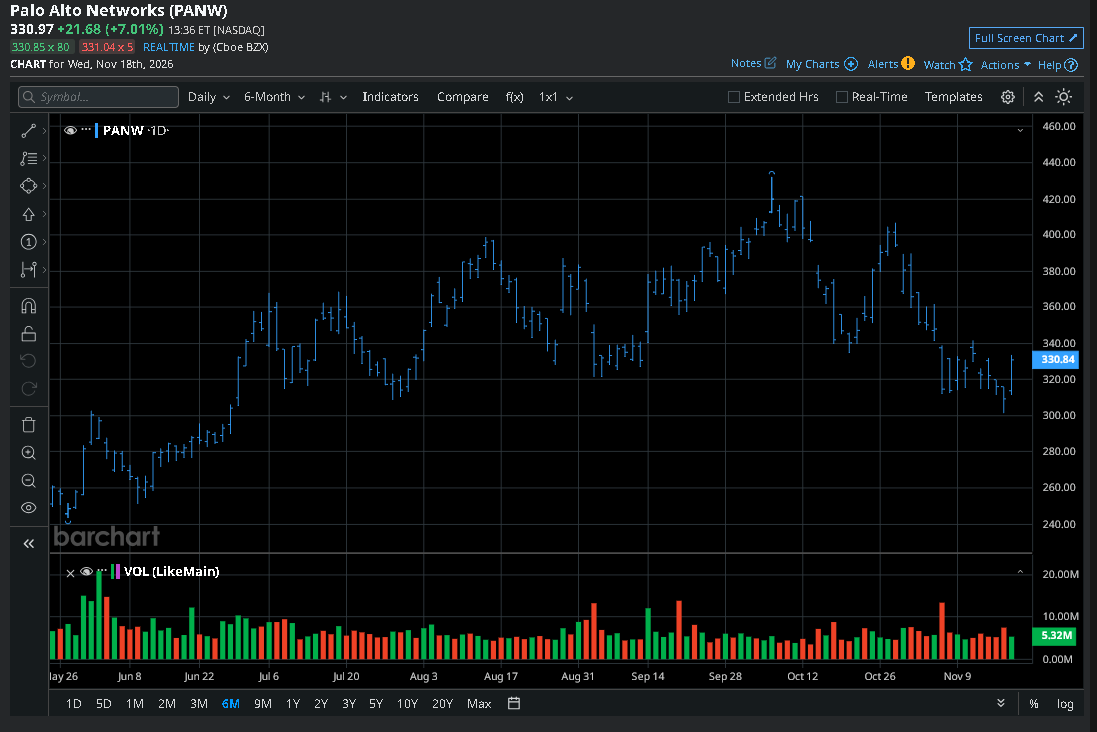
Heading into the earnings print, Palo Alto Networks shares are up 78% year-to-date.
What the Warning Means for PANW Shares
On Wednesday, Senator Maria Cantwell and Senator Mike Rounds urged the White House to “act quickly” to protect critical infrastructure, financial institutions, and widely used software. Separately, Department of Homeland Security Secretary Markwayne Mullin warned in his prepared congressional testimony about foreign adversaries using AI cyber capabilities to threaten U.S. infrastructure.
For PANW stock, the commercial opportunity is in what companies do before the next disruption. The company’s Unit 42 business offers a service that continuously checks customers’ systems for weaknesses and helps prioritize fixes.
If organizations move from periodic assessments to continuous monitoring, Palo Alto Networks has a chance to sell an ongoing service to customers that already rely on its security products.
Should You Buy Palo Alto Networks Stock Today?
Consensus is for Palo Alto Networks to record $0.52 in earnings per share (EPS) for its fiscal Q1, which would represent a nearly 2% decrease on a year-over-year basis.
Heading into the earnings event, the cybersecurity stock is trading at about 136x forward earnings, which makes it expensive by any stretch of the imagination. Therefore, even if PANW reports a solid quarter, much of the related upside is baked into its share price already.
Even from a technical perspective, Palo Alto Networks shares currently sit below major moving averages (MAs), indicating bears remain in control across multiple timeframes.
Wall Street’s Consensus View on Palo Alto Networks
On the flip side, however, Wall Street analysts haven’t thrown in the towel on PANW shares quite yet.
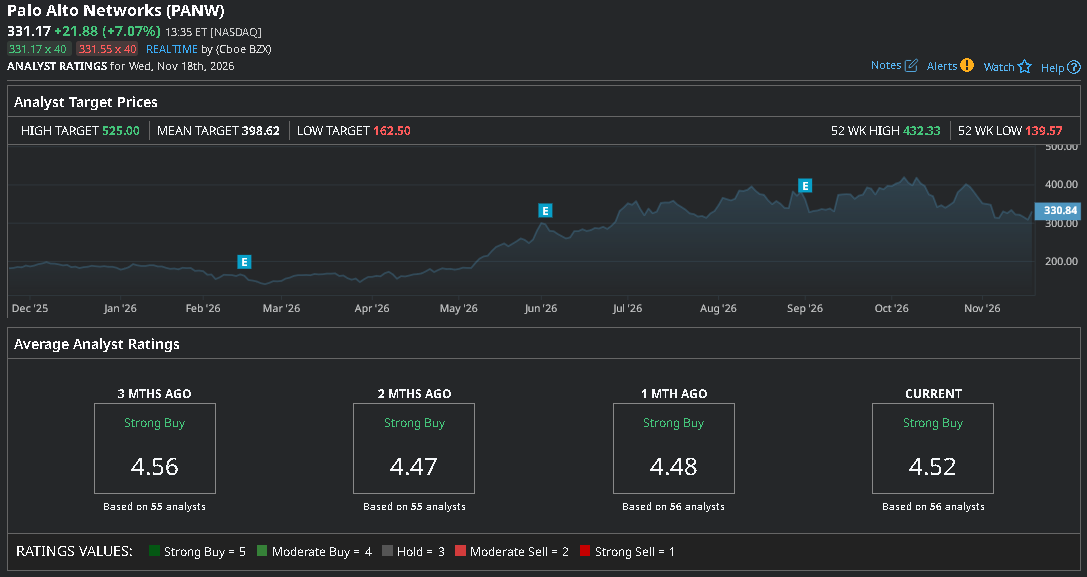
According to Barchart, the consensus rating on Palo Alto Networks remains at Strong Buy, with the mean price target of about $399 indicating potential upside of roughly 20% from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.