


EN
Why Analysts Are Suddenly Talking About This Forgotten Tech Stock
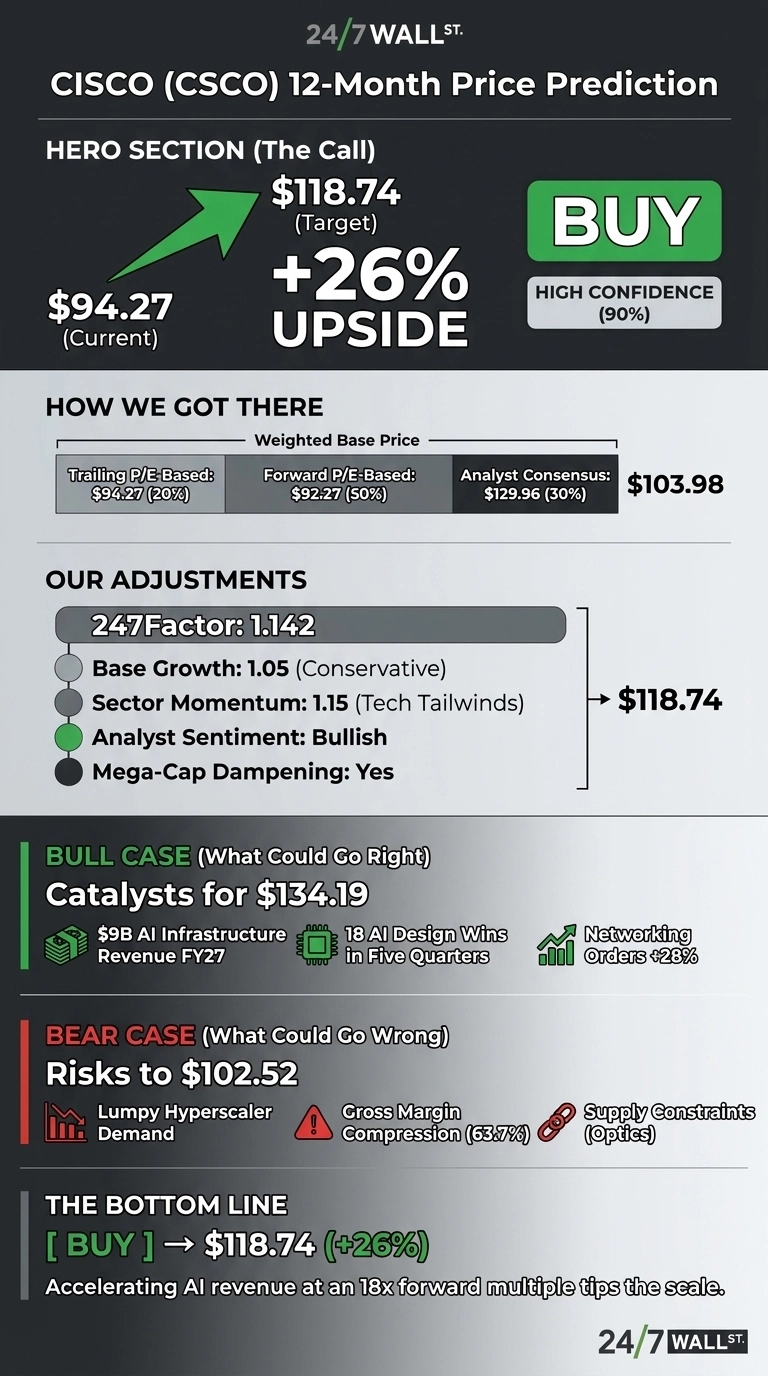
For most of the past decade, Cisco Systems (NASDAQ:CSCO) was known primarily as a dividend stock. AI networking changed that. Cisco’s 24/7 Wall St. price target is $118.74, which implies 25.97% upside from $94.27.
 24/7 Wall St. 24/7 Wall St. Price Target Summary Metric Value Current Price $94.27 Price Target from 24/7 Wall St. $118.74 Upside/Downside 25.97% Recommendation BUY Confidence Level 90%
CSCO gets a buy rating with high confidence from the model because its inputs line up. Cisco just posted 24.4% revenue growth, yet shares trade at roughly 18x forward earnings.
Record Quarter Meets a Post-Earnings PullbackShares fell 2% over the past week, 9.97% over the past month and 15.97% over the past quarter, though they remain up 27.8% year to date. CSCO sits 27.1% below its 52-week high of $129.38 and 31.2% above its low of $71.86. On Monday the stock also underperformed its competitors (MarketWatch).
The selloff came after strong results. Q1 FY27 revenue of $18.517B rose 24.4%, ahead of the $18.116B consensus. Non-GAAP EPS of $1.40 topped the $1.3243 estimate. Networking revenue rose 43%, and management raised FY27 guidance to $74.8B to $75.8B in revenue and $5.47 to $5.53 in non-GAAP EPS.
Why Bulls See $134 and BeyondCisco now expects $9 billion in FY27 AI infrastructure revenue, “more than double FY26 levels.” Cisco has logged 18 AI design wins in five quarters. The campus refresh is still early, with only 9% of switching sales coming from the new portfolio. Chuck Robbins called this “the very early stages of a multi-year networking super cycle.”
Analysts are also bullish: 5 rate the stock a Strong Buy, 14 a Buy and 10 a Hold, with no Sells. Their consensus target is $129.96. In Q3, Renaissance Technologies and Bridgewater opened new positions. If the optimistic case plays out, the stock reaches $134.19.
Margin Mix and Lumpy Orders Could Cap GainsThe rising share of AI hardware drove GAAP gross margin down to 63.7% from 65.5%. Q2 revenue guidance of $18.0B to $18.2B falls short of Q1’s level. Robbins himself called hyperscaler demand “lumpy.”
Services grew only 1%, and optics remain a supply constraint. Still, non-GAAP operating margin hit a record 37.8%, so the business is handling the lower-margin mix well. The bear case comes to at $102.52, which is still above today’s price.
Cisco Trades at a Steep Discount to Arista and HPEArista Networks (NYSE:ANET) is Cisco’s most direct competitor in AI data center switching. Arista grew revenue 58.45% with a 49.1% non-GAAP operating margin, but it trades at about 67x earnings. Cisco trades at 25x.
Hewlett Packard Enterprise (NYSE:HPE) completed its Juniper acquisition and now competes with Cisco in enterprise networking. HPE’s networking revenue rose 74.9%, but its non-GAAP operating margin of 16.2% is far below Cisco’s.
Company Trailing P/E Latest Revenue Growth Non-GAAP Op. Margin Cisco 25 24.4% 37.8% Arista 67 58.45% 49.1% HPE N/M 32.72% 16.2%Arista’s premium multiple makes our 24/7 Wall St. price target look conservative.
Growth at a Value Multiple Tips the ScaleMy 24/7 Wall St. price target remains at $118.74, with a buy rating and 90% confidence. Accelerating AI revenue at an 18x forward multiple tips the scale.
The outlook strengthens if hyperscaler orders hold up and campus refresh orders speed up. The case weakens if gross margin keeps falling without matching operating leverage. For now, the numbers favor the bulls.
Year Price Target from 24/7 Wall St. 2026 $96.04 2027 $120.64 2028 $141.16 2029 $158.71 2030 $172.40The projections rest on Cisco continuing to execute on its current strategy. A sharp pullback in hyperscaler AI spending is the biggest risk to the trend.