


EN
Lowe's posts better-than-expected sales in Q3 2026
Home improvement retailer Lowe’s (NYSE:LOW) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 9.3% year on year to $22.76 billion. The company’s full-year revenue guidance of $92.5 billion at the midpoint came in 0.5% above analysts’ consensus estimates. Its non-GAAP profit of $3.10 per share was 7.6% above analysts’ consensus estimates.
For more on Lowe's, read our free full research report.
Lowe's Q3 2026 highlights:
- Revenue $22.76 billion vs S&P analysts’ consensus estimates of $22.42 billion (9.3% year-on-year growth, 1.5% beat)
- Adjusted EPS $3.10 vs S&P analysts’ consensus estimates of $2.88 (7.6% beat)
- Revenue guidance The company slightly lifted its revenue guidance for the full year to $92.5 billion at the midpoint from $92 billion
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $12.25 at the midpoint
- Operating margin 11.3%, in line with the same quarter last year
- Free cash flow margin 4.7%, up from 0.4% in the same quarter last year
- Same-store sales rose 1.8% year on year (0.4% in the same quarter last year)
- Market capitalization $123.7 billion
"We just delivered our sixth consecutive quarter of positive comp sales driven by continued growth across Pro, Online and Home Services. These results reflect the resiliency of our Total Home strategy," said Marvin R. Ellison, Lowe's chairman, president and CEO. "We remain confident in our agile business model and look forward to sharing more about our growth opportunities in December at our Analyst and Investor Conference. I would also like to thank our frontline associates for their dedication to serve our customers by solving problems and fulfilling dreams for their homes."
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Even a poor business can perform well for one or two quarters, but a top-tier one grows for years.
With $92.37 billion in revenue over the past 12 months, Lowe's is a major player in the consumer retail sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and gives it the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s harder to find incremental growth when you’ve penetrated most of the market. For Lowe's to boost its revenue, it likely needs to adjust its prices or expand into foreign markets.
Lowe's struggled to increase demand as its $92.37 billion in revenue for the trailing 12 months was close to its revenue three years ago. This was mainly because it didn’t open many new stores.
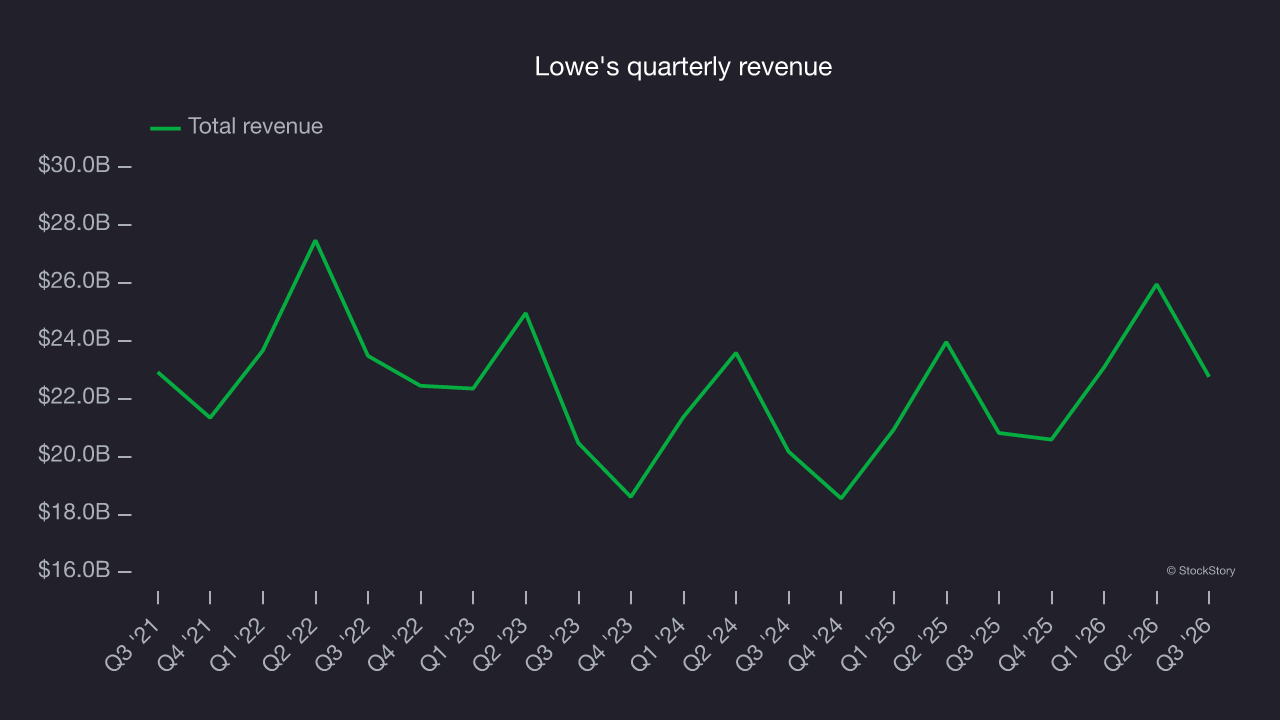
This quarter, Lowe's reported year-on-year revenue growth of 9.3%, and its $22.76 billion in revenue exceeded Wall Street’s consensus estimates by 1.5%.
Looking ahead, sell-side analysts expect revenue to grow 1.3% over the next 12 months, according to S&P, similar to its three-year rate. That uninspiring outlook indicates its newer products will not lead to better top-line performance yet.
Store performance
Number of stores
A retailer’s store count often determines how much revenue it can generate.
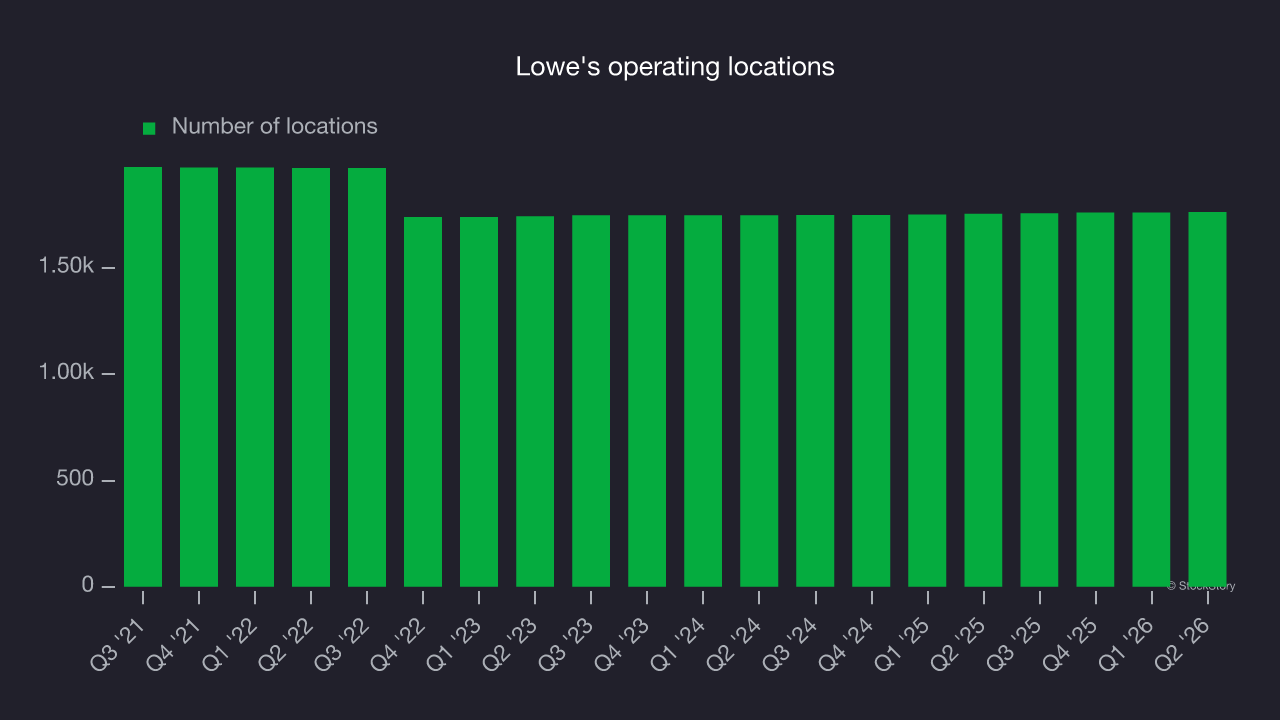
Over the last two years, Lowe's has kept its store count flat while other consumer retail businesses have opted for growth.
When a retailer keeps its store footprint steady, it usually means demand is stable and it’s focusing on operational efficiency to increase profitability.
Note that Lowe's reports its store count intermittently, so some data points are missing in the chart below.
Same-store sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales provide a deeper understanding of this issue because they measure organic growth at brick-and-mortar shops open for at least a year.
Lowe’s demand within its existing locations has barely increased over the last two years as its same-store sales were flat. This performance isn’t ideal, and any move by Lowe's to open new stores to artificially boost revenue growth would warrant skepticism.
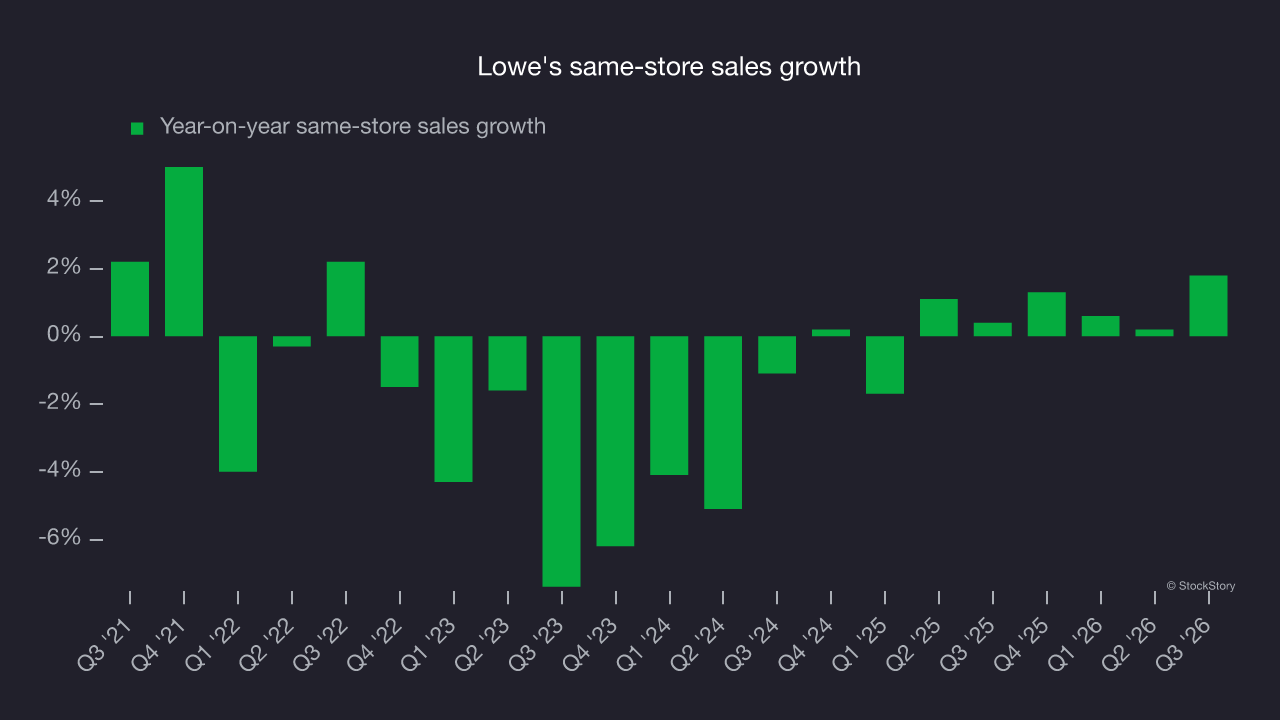
In the latest quarter, Lowe’s same-store sales edged higher 1.8% year on year. This growth marked an acceleration from historical levels, a positive sign.
Key takeaways from Lowe’s Q3 results
Lowe’s delivered a solid quarter, with revenue and EPS topping Wall Street’s consensus estimates. Gross margin came in as expected. Shares rose 3% to $227.12 immediately after the results.
Should you buy the stock or not? When making that decision, it’s important to consider its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).