


EN
BellRing Brands’s Q3 CY2026: Beats on revenue, stock jumps 11.8%
Nutrition products company Bellring Brands (NYSE:BRBR) announced better-than-expected revenue in calendar Q3 2026 [fiscal Q4 2026], with revenue up 6.8% year on year to $692 million. The company expects the full year’s revenue to be around $2.37 billion, close to analysts’ consensus estimates. Its non-GAAP profit of $0.22 per share was in line with analysts’ consensus estimates.
For more on BellRing Brands, read the full research report for free.
BellRing Brands Q3 CY2026 highlights:
- Revenue $692 million vs S&P analyst consensus of $658.2 million (6.8% year-on-year growth, 5.1% beat)
- Adjusted EPS $0.22 vs S&P analyst consensus of $0.23 (in line)
- Adjusted EBITDA $66.4 million vs analysts’ consensus estimates of $65.66 million (9.6% margin, 1.1% beat)
- EBITDA guidance $330 million at the midpoint for fiscal 2027, above analysts’ consensus estimates of $319.5 million
- Operating margin 9.8%, down from 15.8% in the same quarter last year
- Sales volumes rose 14.9% year on year (19.2% in the same quarter last year)
- Market capitalization $1.28 billion
“Fourth quarter Premier Protein ready-to-drink consumption was our strongest of the year, and we were pleased to deliver consumption and sales growth ahead of our guidance with profitability in-line with expectations,” said Michael Axelrod, President and Chief Executive Officer of BellRing. “Fiscal 2027 will be a year of strengthening our foundation, sharpening our execution and driving cost savings to position BellRing for a return to sustainable, profitable growth. My first 100 days have reinforced my conviction in the significant opportunities ahead. We have strong brands, meaningful scale and a clear opportunity to drive more consistent performance and create long-term shareholder value. I look forward to sharing our refreshed strategy and long-term financial targets later this fiscal year.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $2.4 billion in revenue over the past 12 months, BellRing Brands is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the positive side, it can grow faster because it has a longer list of untapped store chains to sell into.
BellRing Brands grew its revenue at a solid 12.9% compounded annual growth rate over the last three years as consumers bought more of its products.
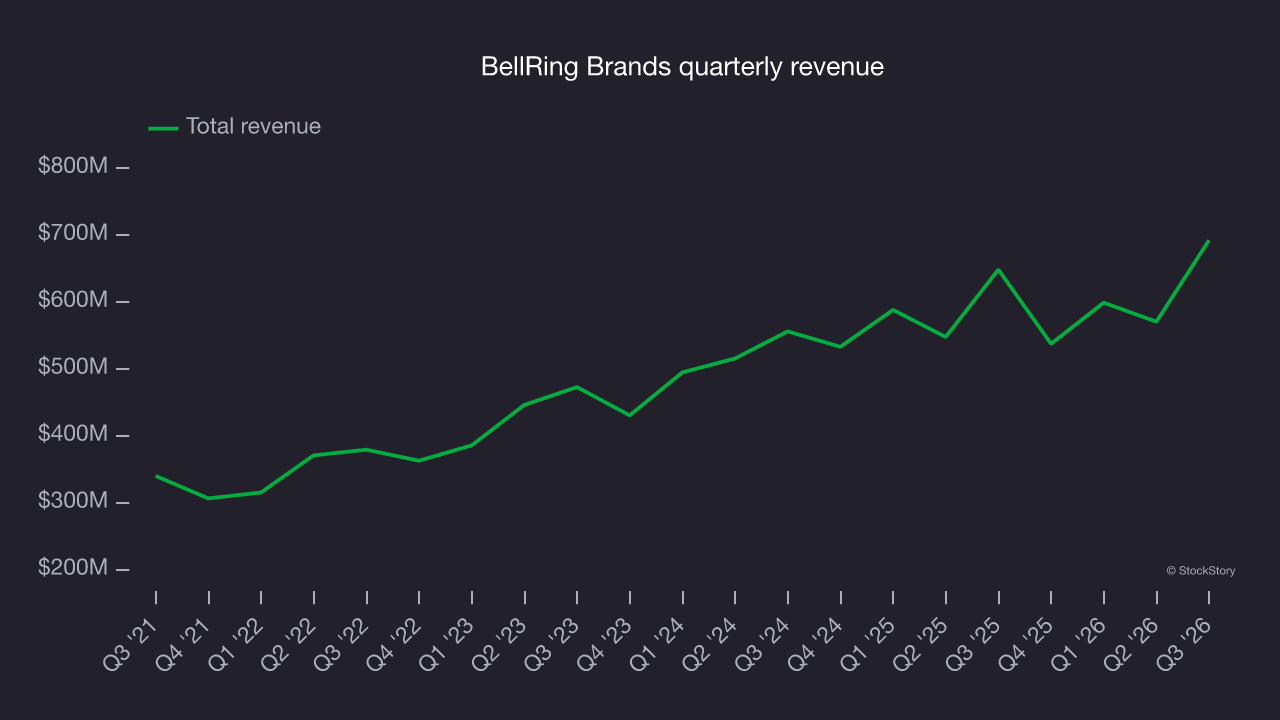
This quarter, BellRing Brands reported year-on-year revenue growth of 6.8%, and its $692 million in revenue exceeded Wall Street’s consensus estimates by 5.1%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P, a deceleration versus the last three years. This projection is underwhelming and indicates its products will face some demand challenges.
Volume growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is central to a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
BellRing Brands’s average quarterly volume growth of 11.2% over the last two years has far outpaced the competition. That is a positive sign, as significant volume growth is rare in the stable consumer staples sector. 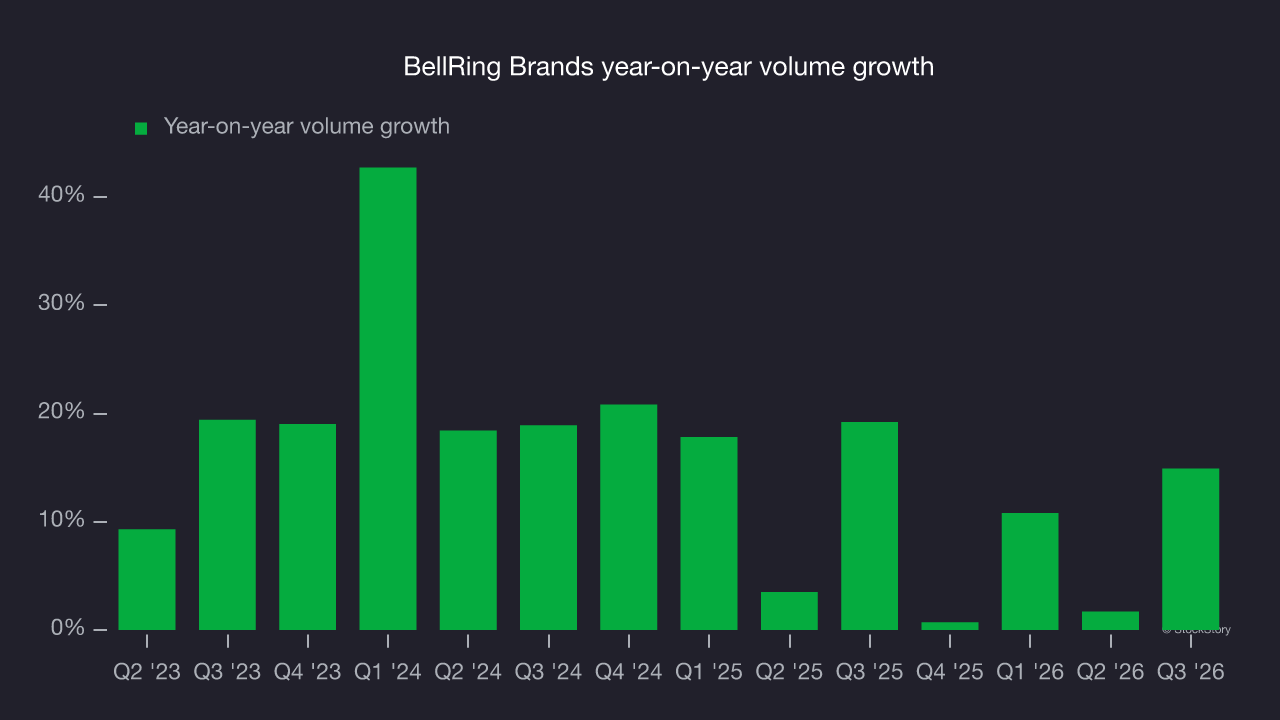
In BellRing Brands’s Q3 2026, sales volumes grew 14.9% year on year. This marked an acceleration from historical levels, a positive signal.
Key takeaways from BellRing Brands’s Q3 results
A revenue beat and full-year EBITDA guidance above Wall Street’s consensus gave BellRing Brands’ quarter some key positives. But the results were mixed overall, with gross margin missing expectations and EPS in line with consensus. Shares soared 11.8% to $12.31 immediately after the release.
The latest quarter is only one piece of the longer-term business quality picture. Quality, combined with valuation, can help determine whether the stock is a buy. For more on the stock, read the full research report here (it’s free).