


EN
Netflix Just Hit a 52-Week Low. Where's the Bottom?
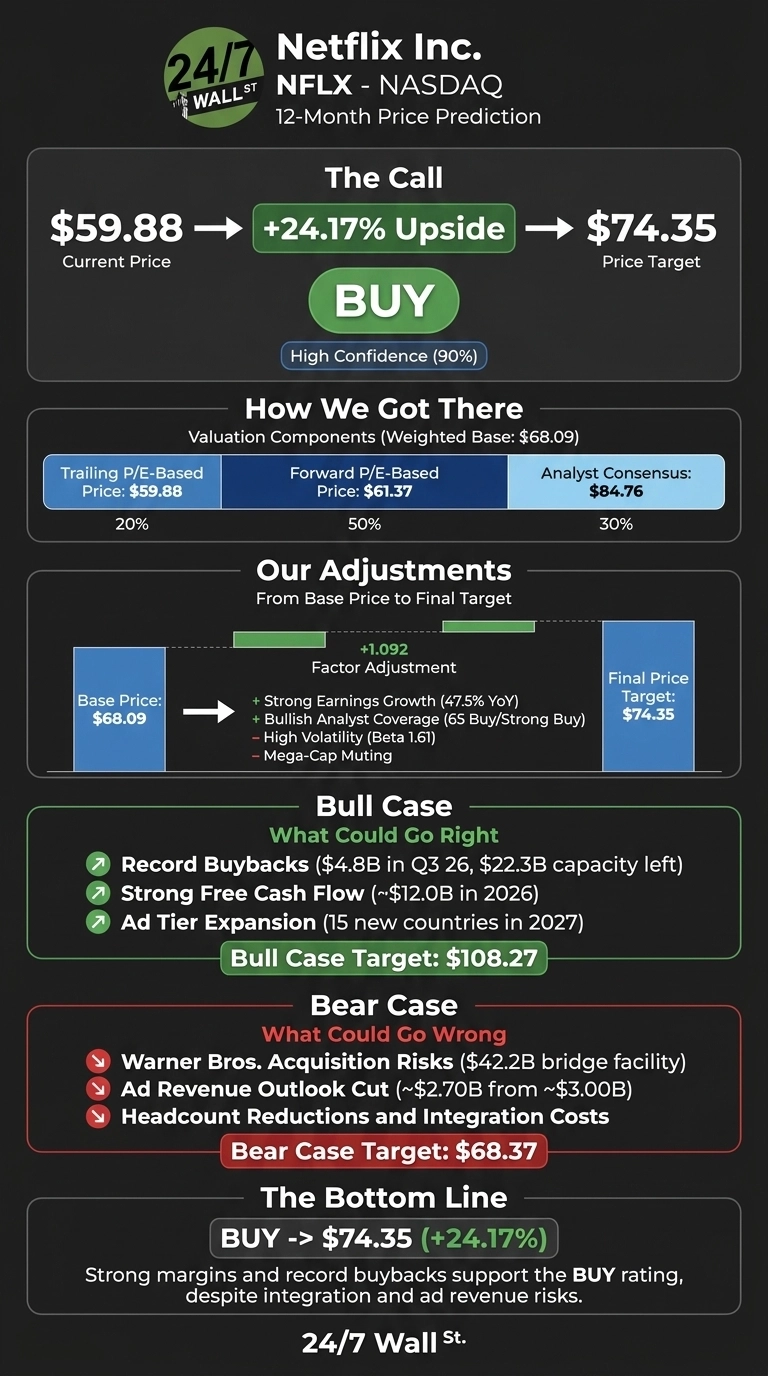
Netflix (NASDAQ:NFLX) closed at $59.68 on November 17, 2026, below its prior 52-week low of $60.48. The 24/7 Wall St. price target for Netflix is $74.35, meaning 24.17% upside from the $59.88 price used in the model. The stock gets a buy rating with high confidence from the model.
24/7 Wall St. Price Target Summary Metric Value Current Price $59.88 Price Target from 24/7 Wall St. $74.35 Upside/Downside 24.17% Recommendation BUY Confidence Level 90%At about 17x forward EPS of $3.5012, I think the selloff already prices in a slower ad rollout, softer U.S. content and deal risk. Netflix still posts some of the best margins in media, and buybacks are running at a record pace.
Ad Cuts and Deal Overhang Drove a 47% Slide From the HighShares fell 5.66% over the past week, 15.38% over the past month, 19.73% since mid-July and 36.35% year to date. The stock sits 47.3% below its 52-week high of $113.34.
Q3 revenue of $12.874B rose 11.85%, essentially in line with estimates, while EPS of $0.87 beat the $0.8229 consensus. Operating margin expanded to 34.6% from 28.2%.
The damage came from the outlook: 2026 ad revenue was cut to about $2.70B from about $3B. Media coverage now openly asks whether Netflix is worth buying at $60.
Why Bulls See $108 AheadNetflix bought back $4.8B of stock in Q3, its largest quarter ever, and has $22.3B of capacity left. Free cash flow should reach about $12B in 2026. Ad tiers launch in 15 new countries starting March 2027, and India view hours grew 24%.
Co-CEO Ted Sarandos said “our business and our business flywheel are working.” Wall Street agrees: 7 analysts rate it a strong buy while 26 have buy ratings. Upside in the bull case reaches $108.27.
Warner Bros. Integration Is the Risk Worth Watching
The pending all-cash acquisition of Warner Bros. Discovery (NASDAQ:WBD) at $27.75 per share carries a $42.2B bridge facility and largest integration risk.
Sarandos acknowledged, “We do need better execution in the U.S.” Q4 operating margin guidance of 26% includes a about 120 bps headwind from headcount cuts. That charge is a one-time restructuring cost, and the free cash flow trim from $12.5B traces to a Q4 real estate transaction. Even the bear case lands at $68.37, and only 2 analysts rate the stock a sell.
 24/7 Wall St. Netflix Earns a Premium Over Disney but Trades Far Below Spotify
Walt Disney (NYSE:DIS) competes directly through Disney+ and Hulu, and its SVOD revenue rose 19% to $6.05 billion last quarter. Disney trades cheaper, but its margin is about half of Netflix’s, which explains the gap.
Spotify (NYSE:SPOT) is the closest subscription-streaming pure play, with 306 million Premium subscribers. It commands more than double Netflix’s earnings multiple despite lower margins.
Company P/E P/FCF Operating Margin Netflix 22 25.9x 29.5% Disney 16 20.0x 14.6% Spotify 56 43.2x 12.8%Netflix sits between its peers on valuation while leading both on margins. Against that peer group, the 24/7 Wall St. price target looks reasonable.
Below $60, Two Catalysts Will Decide the Next MoveOur 24/7 Wall St. price target of $74.35 carries a buy rating and 90% confidence. The deciding factor is cash generation funding record buybacks at a low multiple.
The bull case improves if the 2027 ad expansion launches on schedule. The bear case gains weight if the Warner Bros. integration stresses the balance sheet. At this price, the model projects more upside than downside.
Our model projects Netflix could trade at the following levels, assuming current growth trends and market conditions hold.
Year Price Target from 24/7 Wall St. 2026 $59.14 2027 $74.17 2028 $86.02 2029 $96.35 2030 $106.92Netflix would need to keep executing on its current strategy for these projections to hold. The Warner Bros. integration and the pace of the ad rollout could drove results significantly higher or lower than projected.