


EN
Did Omnyx Edge Launch Just Shift Teradyne (TER) Stock Investment Narrative?
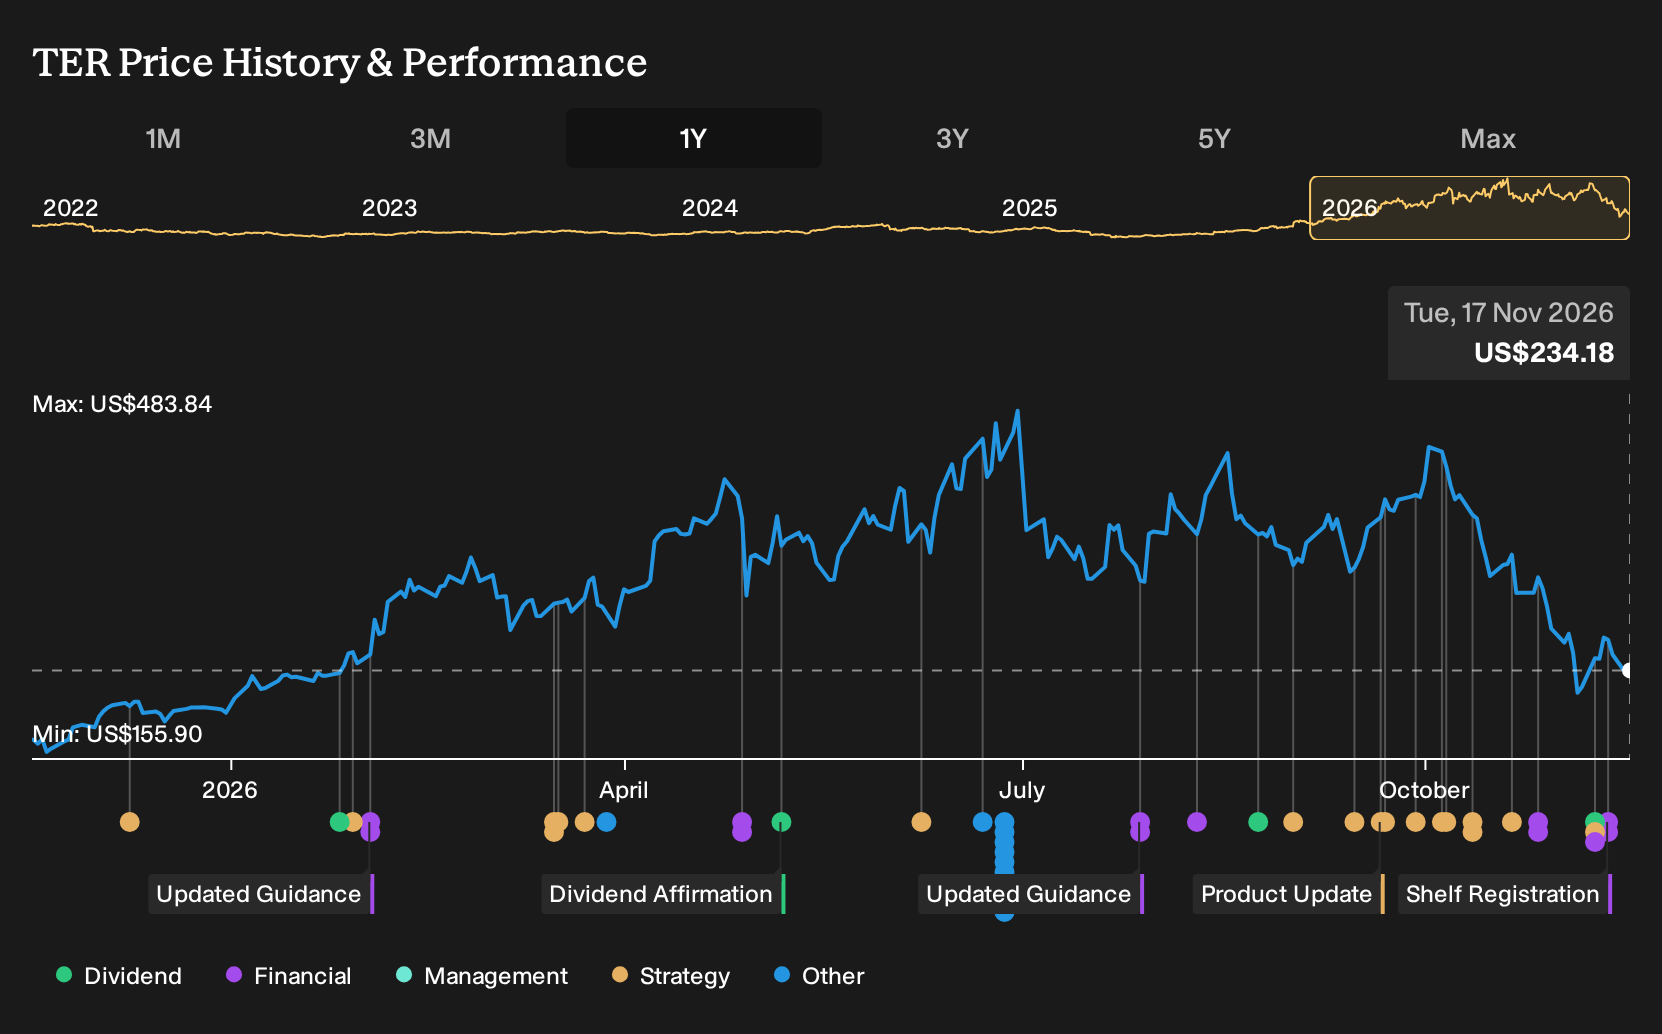
- Teradyne announced a quarterly cash dividend of US$0.13 per share, payable on December 16, 2026, and launched Omnyx Edge, an inline board test platform for physical and edge AI systems that covers compute, sensing, and motion boards.
- Omnyx Edge points to Teradyne leaning harder into physical AI and robotics testing, where complex board stacks and uptime requirements can support demand for high value automated test equipment and factory integration solutions.
- We will examine how Teradyne's investment narrative around AI test and robotics is affected by the new Omnyx Edge platform.
Teradyne Investment Narrative Recap
To own Teradyne, you need to believe AI driven test and robotics demand can justify higher R&D and go to market spending while still supporting attractive margins. The analyst consensus narrative on Simply Wall St focuses on earnings that are expected to grow about 22% a year, with more than 60% of revenue tied to AI focused data center demand.
In the near term, the biggest swing factor remains AI related capital spending, which could affect Semi Test, Product Test and Robotics orders. Mix pressure and new product costs are already guiding gross margin slightly lower, so Omnyx Edge and robotics traction need to scale cleanly or that margin risk may linger.
Omnyx Edge looks most relevant for the current catalyst story because it targets physical and edge AI, where Teradyne is already seeing momentum in Robotics and broader test. The platform spans intelligence, sensing and motion boards, which aligns with the push to broaden exposure beyond data center compute into factory and logistics applications.
For shareholders, Omnyx Edge is mainly about execution. Uptake on complex lines with high uptime requirements could help offset any softness if AI data center CapEx slows, while weak adoption would leave the firm more exposed to mix shifts and margin compression already highlighted in recent guidance.
Teradyne's analyst narrative assumes revenue reaches US$8.9b and earnings hit US$2.9b by 2029, based on 21.2% yearly top line growth and an earnings increase of about US$1.5b from US$1.4b today.
Uncover why Teradyne's fair value indicates a 78% potential upside to its current price, which could narrow quickly if sentiment improves.
Exploring Other Perspectives
One bullish twist on Teradyne focuses on margin resilience rather than margin risk. The most optimistic analysts were penciling in revenue of about US$10.7b and earnings of roughly US$3.6b by 2029 before this dividend and Omnyx Edge news. That outlook is much rosier, and it could shift again as you explore fresh viewpoints.
Explore 4 other Teradyne fair value estimates, including one that suggests up to 125% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Teradyne research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teradyne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teradyne's overall financial health at a glance.
Looking For More Investment Ideas Beyond Teradyne?
Once you have a view on Teradyne, it helps to widen the lens and compare it with other listed companies that share traits you care about, whether that is value, balance sheet strength, or income potential. The Simply Wall St Screener can surface a curated set of stocks that fit those preferences so you can test your thesis against real alternatives.
- If you are hunting for quality at a reasonable price, start with a focused basket of 37 high quality undervalued stocks that pair solid fundamentals with price tags that may not fully reflect them yet.
- For readers who care most about stability and financial resilience, filter for companies in the list of solid balance sheet and fundamentals (24 results) to see which businesses carry less debt and stronger cash positions.
- Income oriented investors can concentrate on cash flow streams instead of stories by reviewing the 7 dividend fortresses that combine higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com