


EN
Matthews reports earnings tomorrow: What to expect
Diversified solutions provider Matthews International (NASDAQ:MATW) will be reporting earnings this Thursday after market hours. Here’s what to expect.
Matthews missed analysts’ revenue expectations last quarter, reporting revenues of $246 million, down 29.6% year on year. It was an underwhelming quarter for the company, with a significant miss of analysts’ EPS estimates and full-year EBITDA guidance missing analysts’ expectations.
Is Matthews a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Matthews’s revenue to decline 20.7% year on year, improving from the 28.6% decrease it recorded in the same quarter last year.
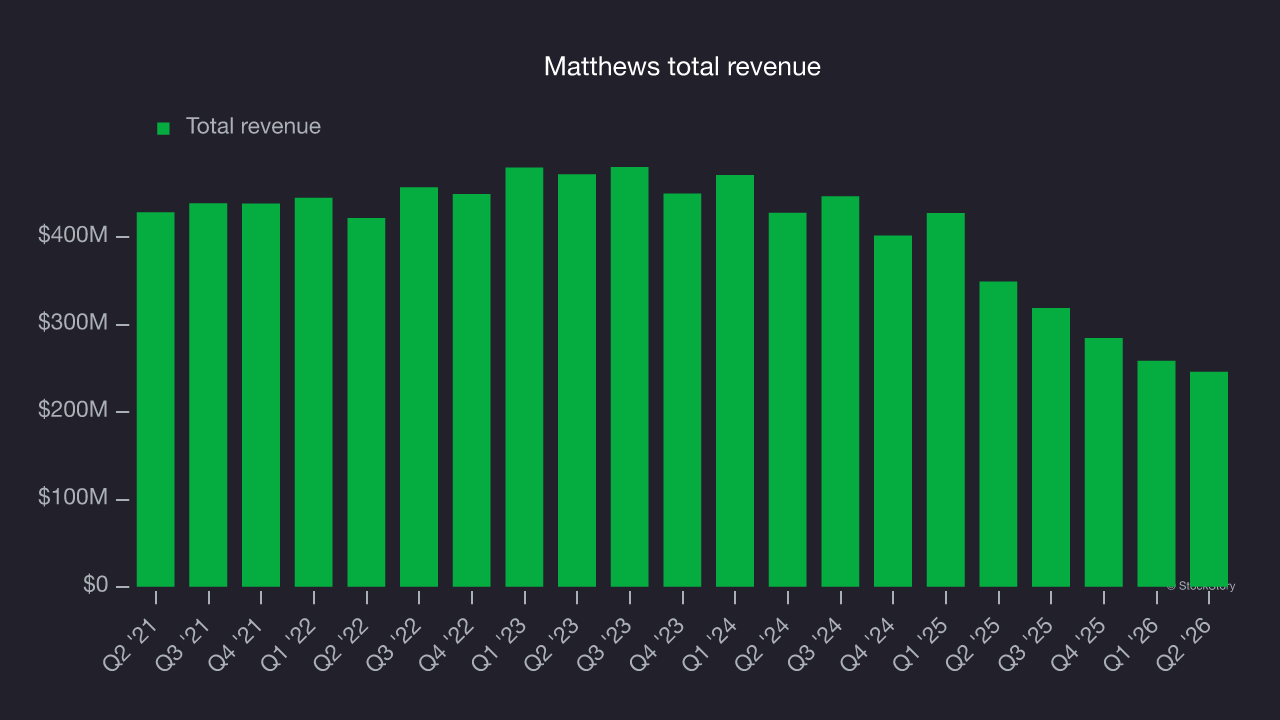
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Matthews has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Matthews’s peers in the consumer discretionary - specialized consumer services segment, some have already reported their Q3 results, giving us a hint as to what we can expect. WeightWatchers’s revenues decreased 11.2% year on year, meeting analysts’ expectations, and Frontdoor reported revenues up 6%, topping estimates by 1.1%. WeightWatchers traded down 6.8% following the results while Frontdoor was up 4.6%.
Read our full analysis of WeightWatchers’s results here and Frontdoor’s results here.
There has been positive sentiment among investors in the consumer discretionary - specialized consumer services segment, with share prices up 3.1% on average over the last month. Matthews is down 1.8% during the same time and is heading into earnings with an average analyst price target of $31.33 (compared to the current share price of $18.56).
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.