


EN
TBC Bank Group (LSE:TBCG) Stock Still Trades At A Discount As Its 5 Year Run Continues
TBC Bank Group has delivered a powerful run in recent years, and with the stock closing at £53.00 most investors are now asking whether that price still lines up with what its earnings can support. Recent share buyback and dividend moves only sharpen the question of how much of that earnings power is already reflected in the market value.
- Over the past 5 years, TBC Bank Group has returned about 380.8%, which puts a lot of weight on whether its current earnings profile can carry that kind of share price rerating.
- The record profit and new GEL 50 million buyback, combined with the latest dividend declaration, can influence how investors think about the sustainability and timing of future earnings and capital returns, especially given weaker results in the Uzbek segment.
- There is a second opinion on TBC Bank Group worth weighing. See what analysts think TBC Bank Group's shares could be worth.
The issue now is whether TBC Bank Group's current share price is adequately supported by the earnings it is generating today.
If you are weighing whether TBC Bank Group's earnings still justify its share price and want a comparison set, it can help to scan 14 high quality undervalued stocks.
Is TBC Bank Group Still Cheap on Earnings?
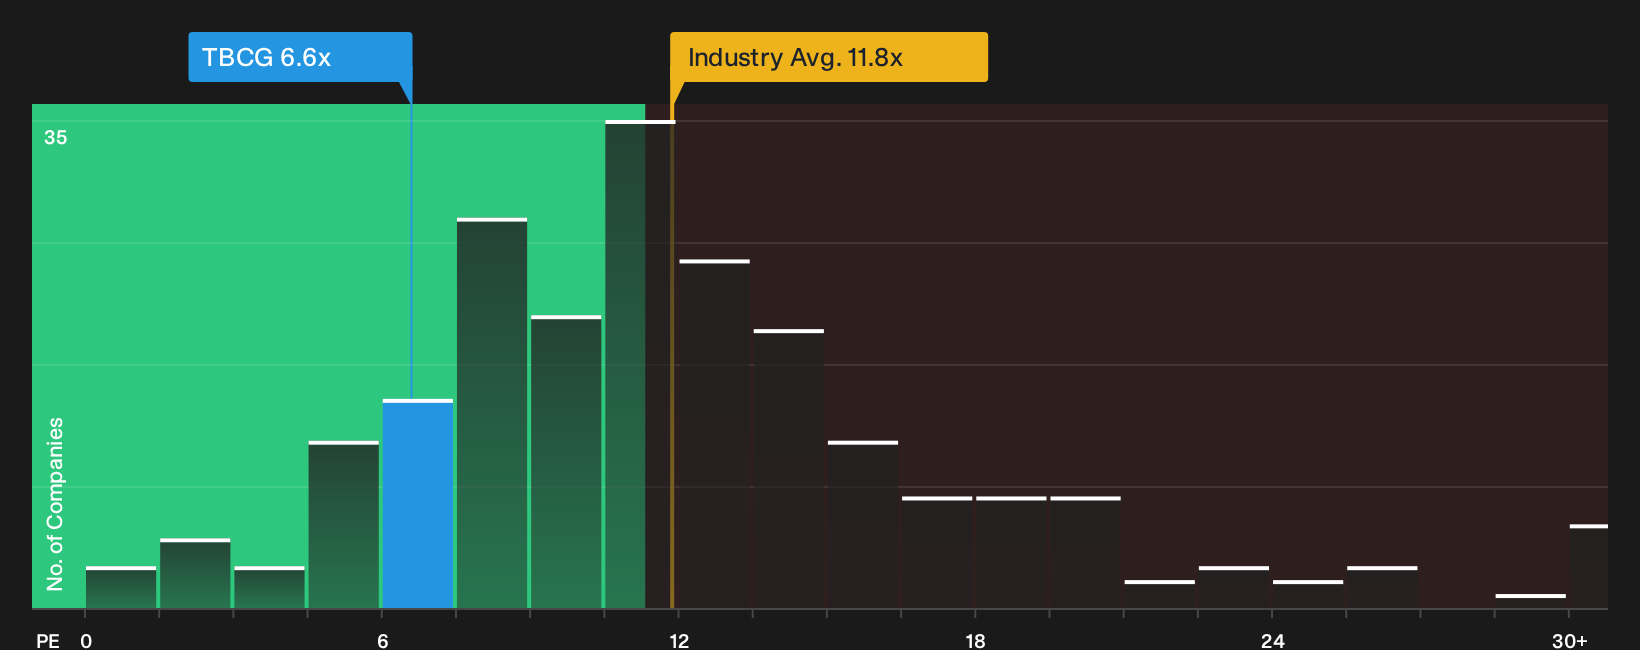
The P/E ratio works well for TBC Bank Group because the business is earnings driven and investors frame returns around profit rather than revenue or assets. At the current price, TBC Bank Group trades on about 6.6x earnings, compared with the wider banks sector on roughly 11.0x and a peer group near 7.2x. That puts the shares on a lower earnings multiple than both the sector and a more focused peer set.
Because the recent record profit in Georgia has sharpened interest in the story, a P/E below a tailored fair level suggests the stock is priced more like a cautious case than a strong one. The fair multiple here reflects what would be expected for a bank with TBC Bank Group's profitability, risk profile and scale, and the current 6.6x sits below that range, which screens as undervalued on this framework. Despite fresh buyback and dividend announcements, the earnings multiple still points to a discount against what the model implies for the bank's fundamentals. Explore the numbers behind TBC Bank Group's P/E valuation.
The TBC Bank Group Narrative: What Would Justify Today's Price?
Narratives on TBC Bank Group pick up where the P/E discussion leaves off and explain which paths for growth, margins and earnings would need to materialise for the stock to be worth materially more or materially less than today's price. Each scenario is tied to a specific mix of potential catalysts and risks. It then links that storyline to a fair value estimate so you can see over time which version of TBC Bank Group's future is tracking closer to reality on Simply Wall St's Community page.
One of the top narratives on TBC Bank Group: 8% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Rising digital monthly active users in Georgia and across the group, together with high engagement levels, create more touchpoints for selling additional products and services..."
Discover why this Narrative puts TBC Bank Group at 8% undervalued.
One more TBC Bank Group check sits beside the earnings multiple
Price ratios tell you what the market pays for today's profits, but analyst projections sketch where they expect TBC Bank Group to be a few years from now and give you a different yardstick to compare with. Explore where analysts expect TBC Bank Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com