


EN
Is Wall Street Bullish or Bearish on WEC Energy’s Stock?
WEC Energy Group, Inc. (WEC), headquartered in Milwaukee, Wisconsin, is a regulated utility holding company serving millions of customers across Wisconsin, Illinois, Michigan, and Minnesota. It generates, transmits, and distributes electricity and provides natural gas service, offering investors exposure to stable regulated earnings, infrastructure investment, and the Midwest energy transition. The company has a market capitalization of $38.64 billion.
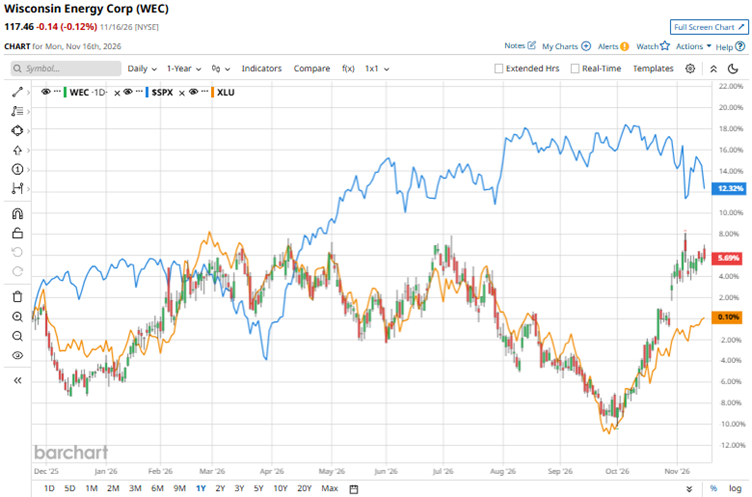
WEC Energy Group’s stock is only modestly higher because its long-term growth story seems strong, but investors are balancing it against the utility’s need for substantial financing. Over the past 52 weeks, the stock has gained 5.9%, while it has risen 7.6% over the past six months. The company’s shares reached a 52-week high of $120.15 on Nov. 5, but are down 2.2% from that level.
Meanwhile, the broader S&P 500 Index ($SPX) has gained 10.1% and marginally over the same periods, respectively, indicating the stock has underperformed the broader market over the past year. Next, we compare the stock with its own sector. The State Street Utilities Select Sector SPDR ETF (XLU) has increased 1.5% over the past 52 weeks and marginally over the past six months. As a result, the stock has outperformed its sector over these periods.
WEC Energy reported better-than-expected third-quarter results. Operating revenues increased 8.9% year-over-year (YOY) to $2.29 billion, while EPS rose 42.2% YOY to $1.18. More importantly, the company’s updated capital plan (for 2027-2031) identifies $10 billion in additional investments compared to the previous five-year plan, of which $8.40 billion was increased due to energy generation. The $47.50 billion capital plan assumes $21.20 billion spending on electricity generation for very large customers/bespoke agreements.
For the current quarter, Wall Street analysts expect WEC Energy’s diluted EPS to decrease 9.9% YOY to $1.28. However, EPS is expected to rise 6.5% YOY to $5.61 in fiscal 2026, followed by a 7.3% increase to $6.02 in fiscal 2027. The company surpassed consensus EPS estimates in each of the four trailing quarters.
Among the 19 Wall Street analysts covering WEC Energy’s stock, the consensus is a “Moderate Buy.” That’s based on seven “Strong Buy” ratings, 11 “Holds,” and one “Strong Sell.” The rating configuration has remained the same over the past three months.
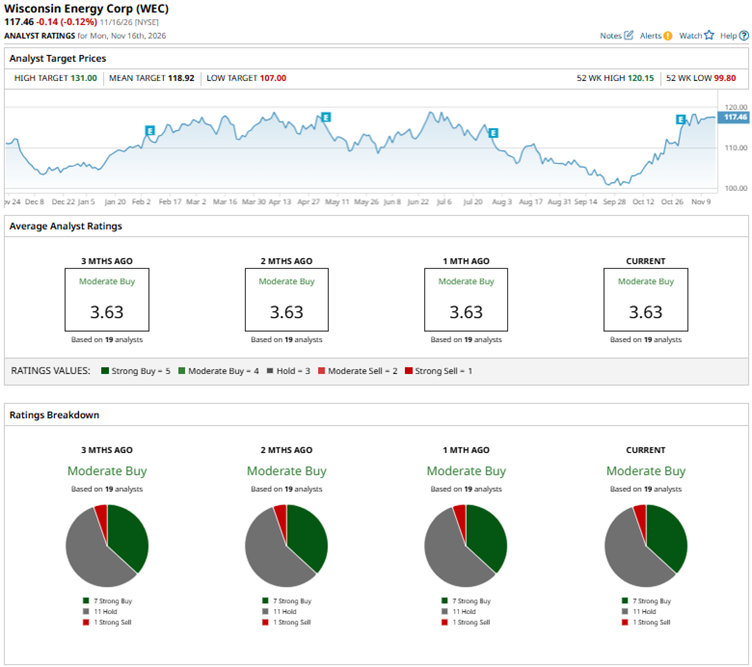
Last month, Scotiabank analysts maintained a bullish “Sector Outperform” rating on WEC Energy’s stock and raised the price target from $117 to $128. The stock’s mean price target of $118.92 implies 1.2% upside from current market prices. Moreover, the Street-high price target of $131 implies a potential upside of 11.5%.
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.