


EN
NVIDIA Trades Under 12 Times Forward Earnings Heading Into Its Report. Bargain or Trap?
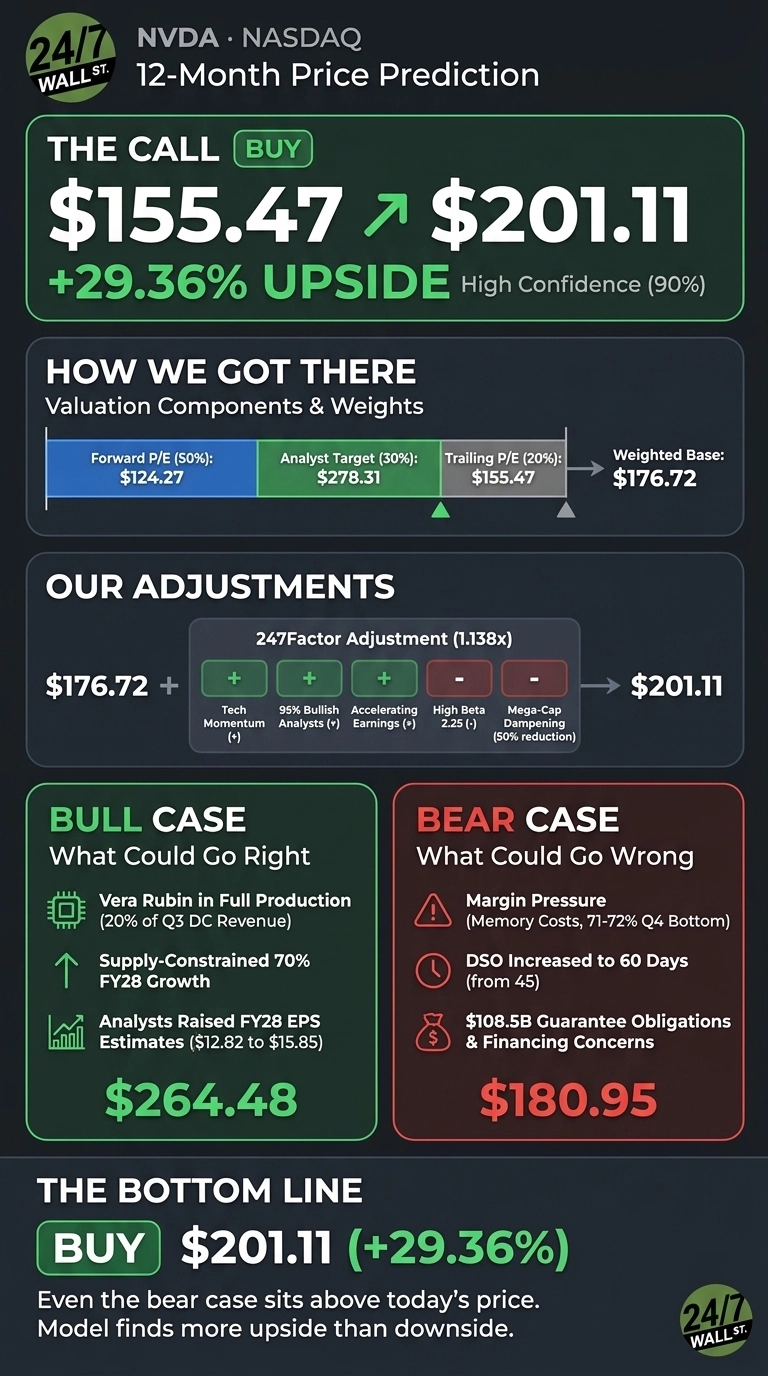
Shares of NVIDIA (NASDAQ:NVDA) go into today’s earnings report, expected after the close on November 17, at less than 12 times forward earnings. Our 24/7 Wall St. price target is $201.11, which implies 29.36% upside over the next 12 months.
Metric Value Current Price $155.47 24/7 Wall St. Price Target $201.11 Upside 29.36% Recommendation BUY Confidence Level 90%Our model rates NVIDIA a buy with high confidence. At a forward EPS estimate of $13.1542, the stock is priced like a mature hardware company, even though it is still guiding to about 70% revenue growth in fiscal 2028. I think the selloff has pushed the price below what the fundamentals support.
 24/7 Wall St.
A 27% Monthly Slide Sets Up a High-Stakes Report
NVIDIA has fallen 12.79% in the past week, 27.23% in the past month and 16.25% year to date. It traded at $225.01 in mid-August. The stock now sits about 36% below its 52-week high of $243.37 and only 4.7% above its low. The Nasdaq slid on Monday as NVIDIA fell ahead of results, and Reuters reports that options are pricing in an unusually large move after earnings (Reuters, WSJ).
The business keeps posting strong numbers. Second-quarter revenue reached $96.22 billion, beating the $92.07 billion consensus, and EPS of $2.22 beat the $2.09 estimate. Data Center revenue grew 117%.
For tonight, consensus calls for EPS of $2.4712 on revenue of $108.73 billion. That is in line with guidance of $108B ±2%.
Why Bulls See $264 or HigherOur bull case reaches $264.48. Vera Rubin is in full production. NVIDIA estimates its revenue opportunity at $40 billion per gigawatt for Rubin, compared with $25 billion for Blackwell.
Jensen Huang said, “Even though our demand is much greater than 70%, our supply allows us to confidently deliver 70%.”
Analysts have raised their fiscal 2028 EPS estimates from $12.8206 90 days ago to $15.8537. The average analyst target is $278.31, and 59 analysts rate the stock a Buy or Strong Buy.
Financing and Margin Risks Behind the DiscountOur bear case is $180.95. Management expects gross margins to bottom at 71% to 72% in Q4 because memory costs are going up. Days sales outstanding increased to 60 days from 45, guarantee obligations reached $108.5 billion, and NVIDIA has committed nearly $50 billion in AI labs.
That combination raises concerns about circular financing, and the company’s guidance excludes China data center compute. In management’s defense, the longer payment terms apply to investment-grade customers, and price increases should bring fiscal 2028 margins back to 72% to 73%. Institutional institutions also tended toward buying in Q3, with 16 buyers versus 7 trimmers.
How NVIDIA Compares to AMD and BroadcomAMD (NASDAQ:AMD) competes directly with NVIDIA in AI accelerators. It trades at about 191x trailing earnings, versus NVIDIA’s 31x, with a 49.5% gross margin against NVIDIA’s 71.07%.
Broadcom (NASDAQ:AVGO) is the main alternative in custom silicon. Its AI semiconductor revenue rose 221% to $16.70 billion. Both rivals are growing fast, but NVIDIA generates more revenue than either one and a higher gross margin than AMD. On that comparison, our target looks conservative.
The chip names get most of the attention, but the power, cooling, and networking suppliers behind every one of these data centers are a separate trade we laid out in a free report on seven AI infrastructure stocks that aren’t chipmakers.
Company Latest Quarter Revenue YoY Growth NVIDIA $96.22B 105.8% AMD $13.38B 44.68% Broadcom $29.59B 85.5% Bear Case Still Sits Above Today’s PriceOur 24/7 Wall St. price target of $201.11 carries a buy rating with 90% confidence. The deciding factor for me is that even our bear case sits above today’s price.
The key signal in tonight’s report is whether the 70% fiscal 2028 growth outlook stays intact. Margins falling below the guided bottom or growing financing exposure would weaken the case. At this valuation, the model finds more upside than downside.
Here is where our model places NVIDIA over the next several years, assuming current growth trends and market conditions hold.
Year 24/7 Wall St. Price Target 2026 $158.63 2027 $208.33 2028 $246.55 2029 $279.87 2030 $302.96These projections assume NVIDIA keeps executing on Vera Rubin. Results could beat these targets if supply constraints ease, or fall short if AI lab financing comes under pressure.