


EN
Ahead of Target Earnings, Here's What Barchart Data Says Comes Next for TGT Stock
Target (TGT) stock heads into its Nov. 18 earnings with an intriguing split — its recent price action signals confidence, but options positioning suggests caution is warranted. Consensus is for the retail behemoth to report $2.05 in earnings per share (EPS) for its fiscal third quarter, representing about 15.17% year-over-year growth.
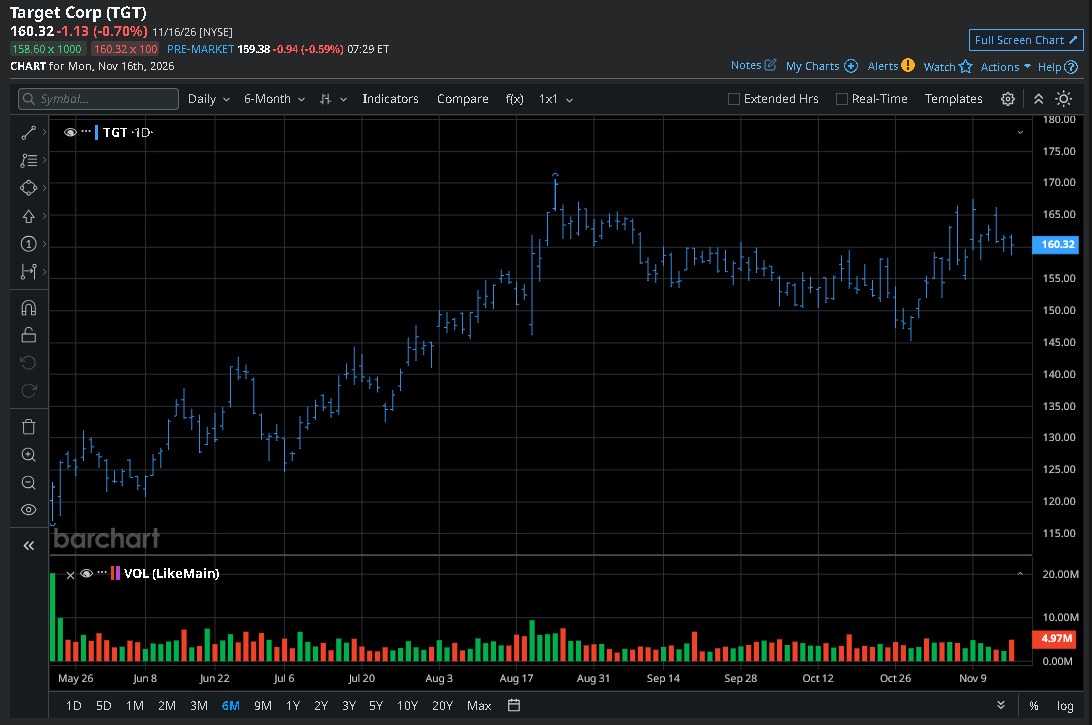
Heading into the quarterly print, Target shares are up a whopping 60% versus the start of this year.
Options Data Signals a Post-Earnings Dip in TGT Shares
Barchart’s latest data shows a put-to-call ratio of 1.3x for TGT options contracts expiring Nov. 20, indicating puts outnumber calls by 30%. That signals defensive positioning, although puts can be used to protect existing holdings only and not express outright bearish sentiment.
That said, the lower price on those options contracts is set at about $148 as of this writing, suggesting Target stock could sink as much as 7.73% within days after the earnings event.
Investors should also note, however, that TGT stock currently sits decisively above major moving averages (MAs), indicating the bulls remain firmly in control across multiple timeframes.
Why Are Options Traders Bearish on Target Stock?
Valuation concerns offer a plausible explanation for the muted options market sentiment for TGT heading into the earnings event on Wednesday.
Given the exciting year-to-date surge, traders likely believe the release will trigger profit-taking, effectively turning it into a classic sell-the-news event. Plus, the derivatives market may be pricing in freight costs, heavier promotions, and the investment needed to sustain growth as well.
For shareholders, the decisive question is whether holiday guidance shows Target can attract shoppers without surrendering too much profit on each sale.
On the flip side, however, Target shares currently pay a healthy dividend yield of 2.89%, which makes them more compelling as a long-term holding heading into 2027.
What’s the Consensus Rating on Target?
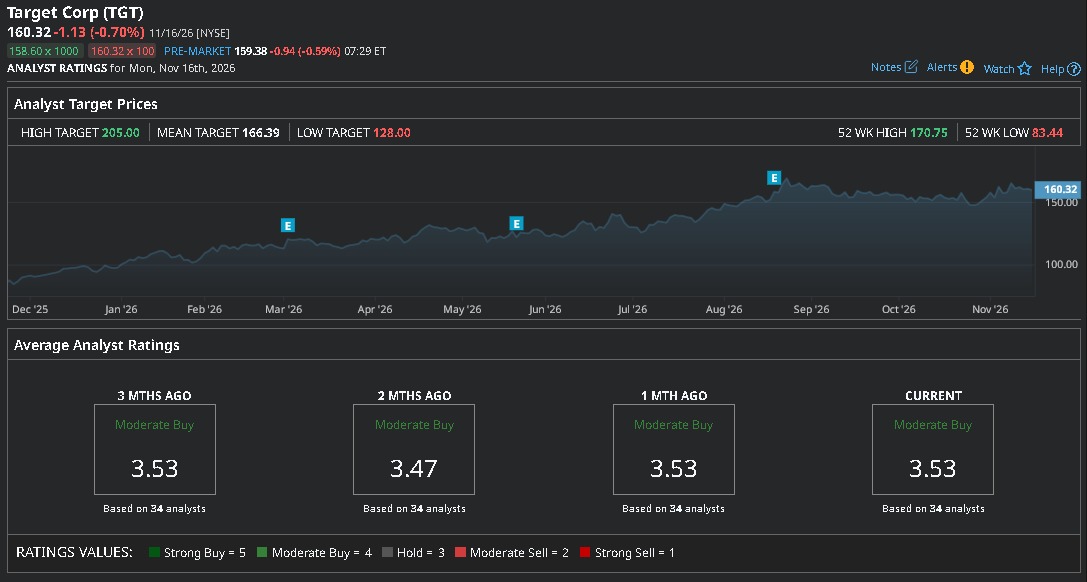
Wall Street analysts also agree that there isn’t likely a lot of upside left in TGT shares. While the consensus rating on Target remains at “Moderate Buy,” the mean price target of about $166 suggests potential upside of about 4% from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.