


EN
Is consumer resilience fueling a rebound in US stocks? US retail data exceeded expectations, leading to the fiercest wave of technology stock cuts in the market in just 20 years
The Zhitong Finance App learned that the newly announced US retail sales for October provided strong support for the resilience of US economic growth driven by the AI investment boom, yet there was no significant relief or some relief from the increasing pressure on the Federal Reserve interest rate faced by a wide range of technology stocks, including AI computing power and semiconductors. This is why American consumers are resilient and can provide fundamental support for continuously adjusted US technology stocks, yet it is difficult to push technology stocks dominated by AI computing power and semiconductor weight to a new round of valuation expansion.
US consumption data and macroeconomic growth resilience in a broad sense are forming a tug-of-war with drastic allocation adjustments in technology stocks: the Bank of America survey showed that the net overallocation ratio of technology stocks fell from 37% to 12%, the biggest monthly decline since 2006, but only 3% of respondents expected a recession, indicating that capital is mainly reevaluating AI capital expenditure and return on investment. Steady consumption raised the possibility that profits would stabilize, but there was no simultaneous reduction in the discount rate of technology stocks; the rise in US bond yields after the retail announcement and the NASDAQ ETF rebounded some of the pre-market gains, which also showed that interest rates were still an important constraint on the rebound.
Consumer resilience can create conditions for the recovery of the US stock technology sector, and a continued rebound trajectory requires companies to capitalize on growth with profits and cash flow — companies that can handle consumer demand and maintain profit margins, and AI suppliers with more solid order delivery and financial guarantees to have a better foundation to transform the market rebound trend into a fundamental revaluation.
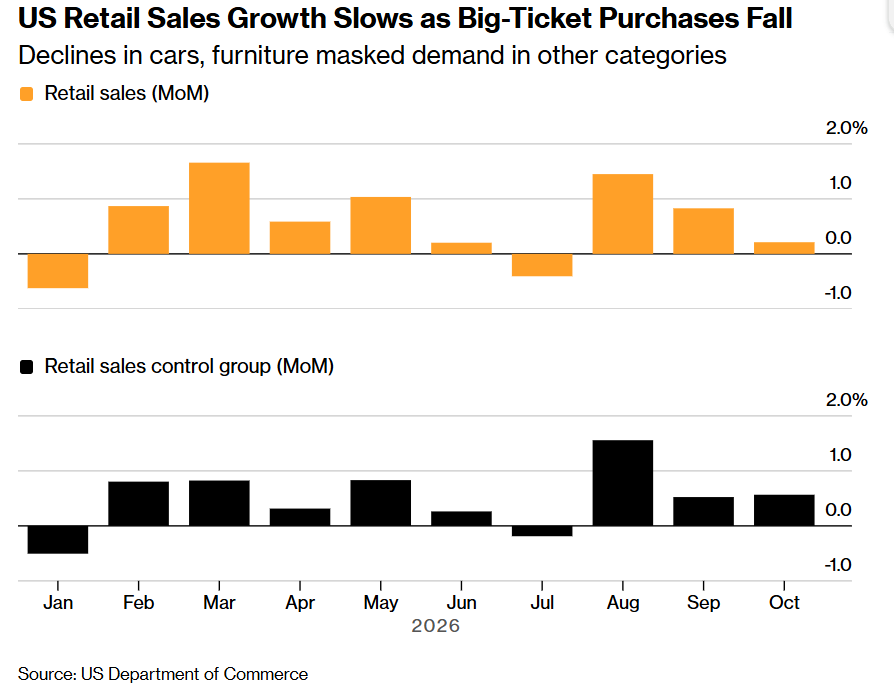
Retail and restaurant sales announced on November 17 reached US$748.2 billion, up 6.8% year on year and 0.2% month on month. Although the total growth rate was lower than 0.8% in September, the performance was stronger after excluding automobiles. Control Group sales and previous value increases are particularly beneficial to consumption growth expectations in the fourth quarter.
Retail and restaurant sales in the US rose 0.2% month-on-month in October, slightly higher than economists' median expectations of 0.1% compiled in an institutional survey; the previously announced increase in retail sales for September remained at 0.8% month-on-month, with no revisions. Although the total growth rate has slowed, consumption performance has become more resilient after excluding some highly volatile projects.
Specifically, retail sales after excluding automobiles and parts increased 0.6% month-on-month, higher than expected 0.4%. The previously announced month-on-month increase for the same category in September was revised up from 0.9% to 1.1%. At the same time, sales after excluding automobiles and gasoline increased by 0.5%, higher than the expectations of about 0.3% to 0.4% shown in surveys by different agencies; the month-on-month increase for the same type was also revised from 0.2% to 0.5% in September, indicating that previous basic demand was stronger than the initial value.
0.2% masks consumer resilience: the real surprise was in the control group and previous value revisions
What is more worthy of investors' attention is that retail “control group” sales, which provide an important basis for estimating GDP commodity consumption, increased 0.6% month-on-month, exceeding expectations of 0.4%, and the increase was drastically revised from 0.1% to 0.5% in September. This indicator excludes food services, car dealers, building materials, and gas station sales. The stronger than expected performance for the month and the revised data for the previous month indicate that US consumption is clearly weakening based on the slowdown in total retail sales growth alone.
US commodity consumption entered the fourth quarter on a more stable basis compared to previous market optimism, demonstrating the strong resilience of US economic growth, which relies on consumption expansion, and reinforces the expectations of a “soft landing” for the US economy.
According to official data and media surveys, the main reason for exceeding expectations came from core subcategories. The significance of the control group is that it provides an important input for estimating commodity consumption in GDP. Excluding automobiles, gasoline, building materials, and restaurants, this indicator increased 0.6% in October, compounded by an increase of 0.1% to 0.5% in September, which meant that the consumption base when entering the fourth quarter was more stable than previously estimated. The decline in automobile sales may explain part of the overall deceleration, but it is not enough to support the judgment that “American consumers have shrunk across the board.” Retail data is the amount of sales not adjusted for inflation, and its resilience ultimately needs to be converted into actual consumption growth through corresponding price indicators.
Segments showed clear differentiation: out of 13 industries, 7 grew, 5 declined, and 1 remained flat. Other retailers grew 4.7%, health and personal care and gas stations all increased 1.5%, non-store retail increased 1.2%, building materials grew 0.5%, restaurants increased 0.2%, and general merchandise stores grew 0.1%; furniture fell 2.3%, automobiles and parts fell 1.6%, clothing and sports and entertainment products all fell 0.7%, food and beverage stores fell 0.2%, and electronics products remained the same as home appliances. Large, interest-rate sensitive spending is weak, and online channels and some daily expenses are more stable.
Household purchasing power is also stratified. Brian LeBlanc, head of economic analysis at PNC Financial, pointed out that active credit card account balances grew at a year-on-year rate of more than 9%, and young households had thinner savings buffers and higher credit dependency. This means that retail resilience can support revenue expectations, but whether retailers can maintain profits also depends on promotion intensity, customer structure, and ability to pass on costs.
The macroeconomic growth of the United States has been underpinned, and stock market valuations are still bound by interest rates
Immediate transactions after the data was released showed that interest rate pressure temporarily weighed growth. As of 8:44 p.m. EST on November 17, at around 22:00 Beijing time, the two-year US Treasury yield rose from about 4.82% to 4.849% before the data was released, and the 10-year term rose from 5.12% to 5.14%; the pre-market decline of the S&P 500 ETF (SPY.US) increased from 0.1% to 0.2%, and the US stock ETF (QQQ.US) tracking the Nasdaq 100 index narrowed from 0.3% to 0.2%. Assets related to the NASDAQ index are still trying to be repaired, but the marginal reaction after the retail announcement was partly due to rising yields and stock rebounding.
There is a clear macroeconomic basis for this reaction: CPI and core CPI rose 0.4% and 0.3% month-on-month respectively in October, and consumer resilience made the Fed lack a reason to shift to easing due to rapidly weakening demand. Prior to the retail announcement, the market had taken into account the probability of a 25 basis point rate hike of about 95.4% in December; the US dollar index had risen above 103.50 during the Asian session. As far as the stock market is concerned, revenue expectations are supported, but forward profit discount rates and financing costs are still high, particularly limiting AI infrastructure companies that are slow to repay cash flow and rely on continuous financing.
This round of repairs still faces significant adjustments. The Philadelphia Semiconductor Index rebounded about 17.2% from November 5 to 11, then fell back to about 9.0% as of the 16th; it fell 5.28% in a single day on Monday, and the NASDAQ 100 fell 2.67%. The cumulative retracement of about 34% from the June high level was about 34%, and the technical bear market is still deep. Asia is also not free from pressure: China's Taiwan Weighted Index and South Korea's KOSPI fell sharply by about 6% and 3.6% respectively on Monday, then fell by 2.31% and 2.59% on Tuesday. Leadership transitions, export restrictions, and concerns about AI return on investment cannot simply be attributed to the end of the AI infrastructure frenzy or pessimistic expectations of an economic recession.
Consumption has not stalled, and the AI theme is still on a revaluation trajectory: capital is beginning to distinguish between economic resilience and actual AI computing power returns
The Bank of America survey revealed just this difference: fund managers cut allocations on technology, yet they are not generally betting on a recession. According to the November 6-12 survey, the net overallocation ratio of technology stocks fell from 37% to 12%, down 25 percentage points, the biggest monthly decline since 2006; this measures the difference between the ratio of overallocated and underallocated respondents.
Consumer resilience can support corporate revenue, but it has failed to simultaneously ease interest rate constraints on highly valued stocks: after the data was released, two-year and ten-year US Treasury yields rose, and the NASDAQ 100 ETF returned some pre-market gains, reflecting that the market is still weighing growth support and financing costs. Meanwhile, the Bank of America survey showed that the net overallocation ratio of technology stocks fell from 37% to 12%, the biggest monthly decline since 2006, yet investors have not shown enough panic.
Market repricing of popular stocks linked to the resilience of US consumption and AI computing power can be described as occurring simultaneously: the former reduces concerns that aggregate demand will rapidly stall, while the latter still depends on whether computing power procurement, project delivery, and customer repayments can support long-term profits. Whether the recovery in US stocks can continue is whether improvements in corporate profits can cover interest rate pressure, and whether AI growth expectations can be verified by continued cash flow.
According to the Bank of America survey, only 3% expect a recession in the next year, and the cash ratio will drop to 3.6%; net 38% believe that companies are overinvested, and 52% expect AI hyperscale cloud vendors to announce capital expenditure cuts in the next six months. As a result, the Bank of America strategist team led by senior Wall Street strategist Hartnett still believes that the cooling of positions has not reached the level of panic sufficient to support reverse buying. Strong consumer and technology stock allocations can be established at the same time, because capital is revaluing the return on AI investments rather than completely denying the US economy.
Nvidia's target price adjustments further reflect this repricing. Goldman Sachs, Citibank, and UBS lowered their target prices from $300 to $220, $285 to $225, and $300 to $240, respectively, all retaining the buy rating. Goldman Sachs placed more emphasis on the impact of leadership uncertainty on valuation multiples; UBS also revised its 2028 revenue forecast to reflect potential constraints on business scale due to factors such as export policies. There is no contradiction between long-term optimism and lowering the prices they are willing to pay, and consumption data cannot directly eliminate these company-level discounts.
SemiAnalysis, a well-known semiconductor industry chain research agency, downgraded the capital expenditure forecast for AI accelerators by 28% to US$758 billion in 2028, 40% to US$923 billion in 2030, and reduced the cumulative shipping area forecast for logic silicon wafers by 17% from 2026 to 2030. This is a correction to the original growth path, and the new model still anticipates significantly higher spending in 2030 than 2026.
SemiAnalysiss' latest forecast report shows the latest AI industry chain investment logic: application revenue must cover computing power costs, financing must support computer room construction, and power access and system delivery determine when chip orders are converted into revenue. SemiAnalysis emphasizes that the latest forecast model adjustments involve revenue growth, financing and deployment constraints, and are not solely triggered by Hwang In-hoon's departure.
SemiAnalysis cut the global AI accelerator spending forecast by 28% to US$758 billion in 2028 and 40% to US$923 billion in 2030; however, the new model still expects spending to continue to grow from US$392 billion in 2026. It should be noted that what has been revised down here is the previously anticipated expansion path, and the caliber is focused on accelerators, and cannot be expanded to the full data center capital expenditure.
The agency also anticipates that 5.8 gigawatts of the US data center capacity originally scheduled to be put into operation from the second half of 2027 to the first half of 2028 will be extended, but it emphasizes revenue growth and the financing environment as the more important reasons for the adjustment. Analysts at the agency said that in line with the forecast model, investors are demanding that the scale of future purchases be re-matched with payment requirements, financing capacity, and actual delivery schedule.
The improvement in retail data is the macro basis for corporate revenue, and the continued rebound in AI stocks also requires verification of profit and financing conditions. Currently, retail and payment companies that can turn consumer resilience into cash flow, and AI vendors with clear delivery arrangements, repayment capabilities, and financial guarantees are more noteworthy. If inflation gradually eases and financing costs fall, consumer resilience can more easily be transformed into joint improvements in profits and valuations; the performance of the US stock market after the release of historical data, especially technology stock trends, is still at a stage where technology stocks are trying to recover and interest rate restrictions have not yet been relaxed.