


EN
OneWater misses Q3 CY2026 revenue estimates
Boat and marine products retailer OneWater Marine (NASDAQ:ONEW) fell short of the market’s revenue expectations in calendar Q3 2026 [fiscal Q4 2026], with revenue falling 7.4% year on year to $426 million. On the other hand, the company’s full-year revenue guidance of $1.83 billion at the midpoint came in 0.8% above analysts’ consensus estimates. Its non-GAAP profit of $0.13 per share was 71.1% above analysts’ consensus estimates.
For more on OneWater, read our free full research report.
OneWater Q3 CY2026 highlights:
- Revenue $426 million vs S&P analyst consensus of $432.6 million (7.4% year-on-year decline, 1.5% miss)
- Adjusted EPS $0.13 vs S&P analyst consensus of $0.08 (71.1% beat)
- Adjusted EBITDA $17.59 million vs analysts’ consensus estimates of $15.83 million (4.1% margin, 11.2% beat)
- Adjusted EPS guidance $0.88 at the midpoint for fiscal 2027, missing analysts’ consensus estimates by 22.4%
- EBITDA guidance $87.5 million at the midpoint for fiscal 2027, above analysts’ consensus estimates of $83.13 million
- Operating margin 3.6%, up from -28.3% in the same quarter last year
- Same-store sales fell 3.8% year on year (23% in the same quarter last year)
- Market capitalization $151.7 million
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $1.78 billion in revenue over the past 12 months, OneWater is a small retailer, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with suppliers.
OneWater’s demand was weak over the last three years. Its revenue fell by 2.8% annually as it didn’t open many new stores.
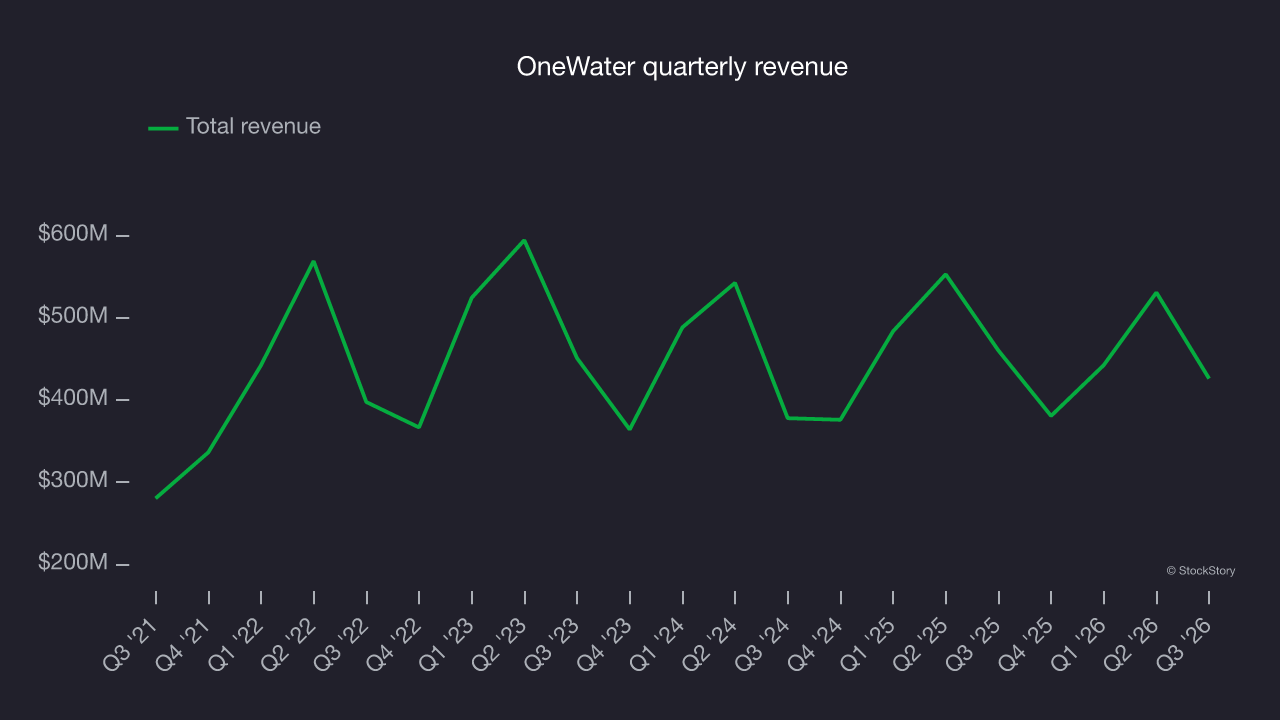
This quarter, OneWater missed Wall Street’s consensus estimates and reported an uninspiring 7.4% year-on-year revenue decline, generating $426 million in revenue.
Looking ahead, sell-side analysts expect revenue to grow 2.4% over the next 12 months, according to S&P. While this projection indicates its newer products will catalyze better top-line performance, it is still below average for the sector.
Store performance
Number of stores
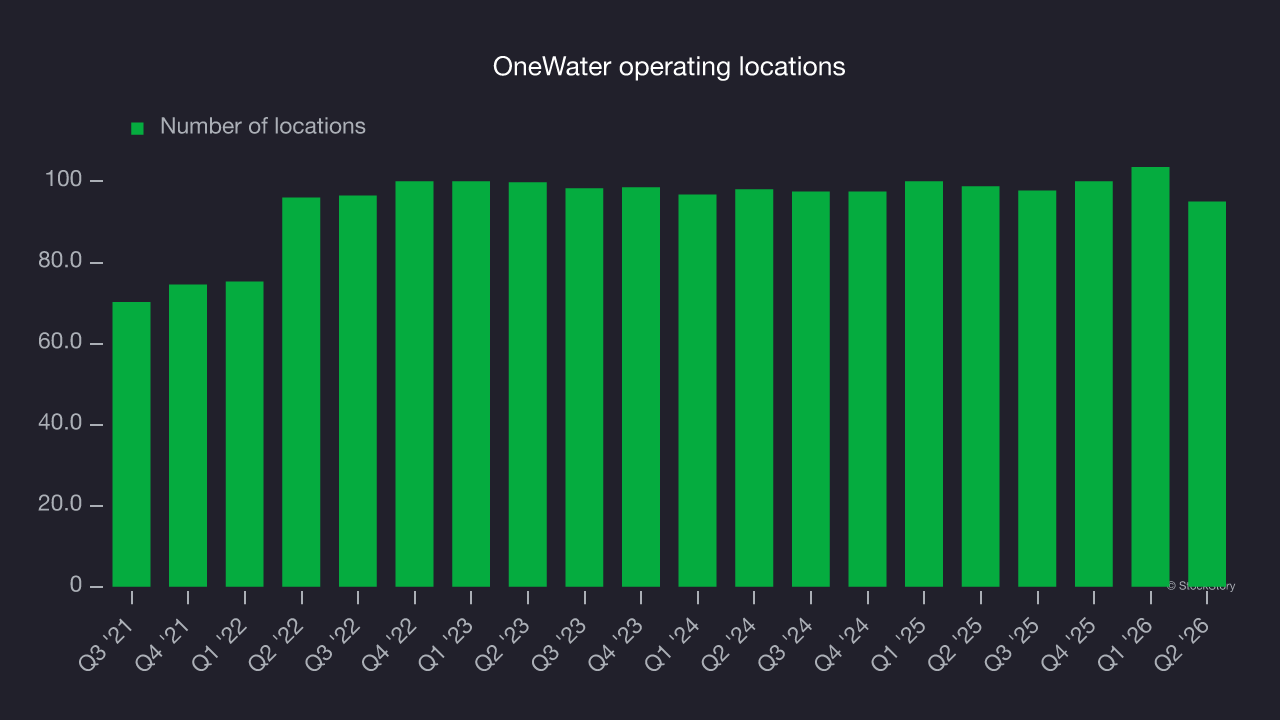
Over the last two years, OneWater has kept its store count flat while other consumer retail businesses have opted for growth.
When a retailer keeps its store footprint steady, it usually means demand is stable and it’s focusing on operational efficiency to increase profitability.
Note that OneWater reports its store count intermittently, so some data points are missing in the chart below.
Same-store sales
The change in a company’s store base only tells one side of the story. The other is the performance of its existing locations and e-commerce sales, which informs management teams whether they should expand or downsize their physical footprints. Same-store sales provide a deeper understanding of this issue because they measure organic growth at brick-and-mortar shops open for at least a year.
OneWater’s demand has been healthy for a retailer over the last two years. On average, the company has grown its same-store sales by 3.1% per year. Given its flat store base over the same period, this performance stems from not only increased foot traffic at existing locations but also higher e-commerce sales as demand shifts from in-store to online.
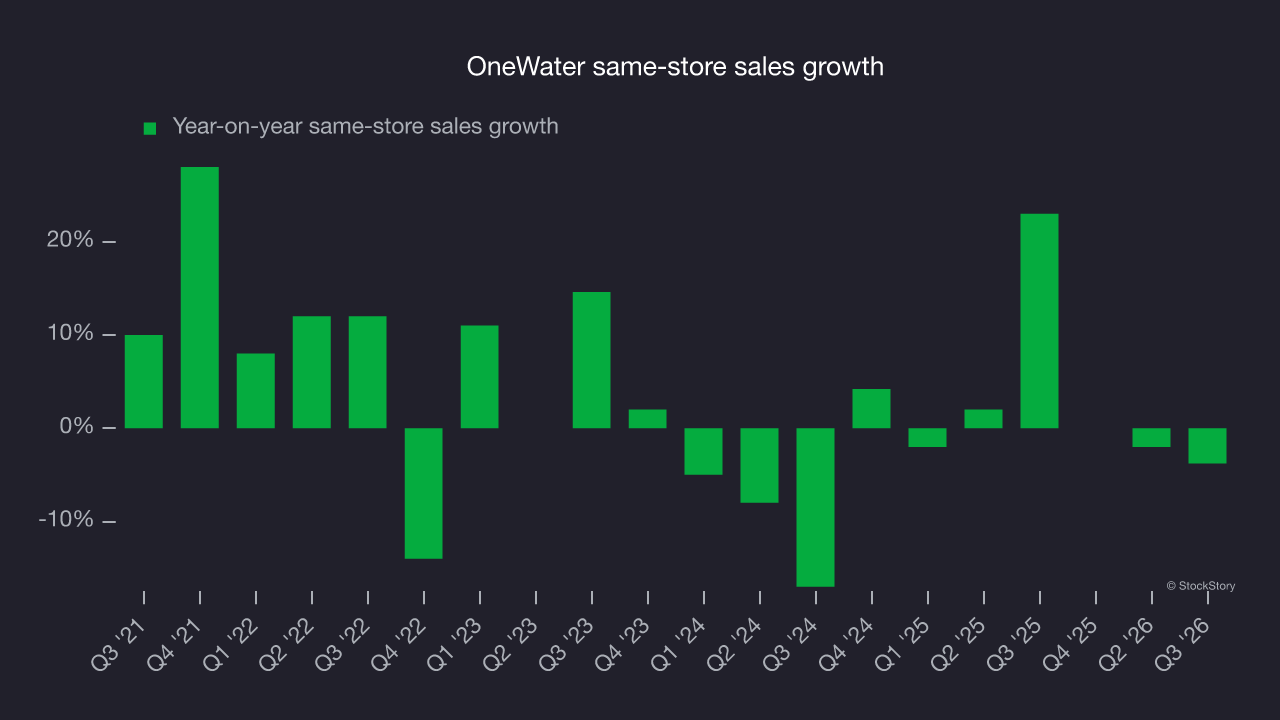
In the latest quarter, OneWater’s same-store sales fell by 3.8% year on year. This decline was a reversal from its historical levels.
Key takeaways from OneWater’s Q3 results
Earnings were a bright spot for OneWater in Q3: EPS beat analysts’ consensus estimates, and EBITDA topped Wall Street’s consensus by a wide margin. But revenue missed expectations, and the 2027 EPS guide was below expectations. The quarter was mixed overall. Shares remained flat at $9.07 immediately after the results.
OneWater’s latest quarter matters, but longer-term fundamentals and valuation matter much more when deciding whether the stock is a buy. Read the full research report here (it’s free).