


EN
Enel (BIT:ENEL) Stock Looks Fairly Valued Following Its 92% Run
Enel has delivered a strong multi year share price performance, and the question now is whether that climb can be backed up by what the utility is earning today. With the stock recently closing at €9.76, the key issue for you is how much of its earnings story is already embedded in that price.
- Over the past 5 years Enel shares have returned 92.1%. This raises the question of whether the current earnings profile can support the expectations that kind of gain often reflects.
- Recent news around Enel Green Power's focus on storage, digitalisation and large scale energy projects can influence how investors think about future earnings durability and the timing of cash flows that underpin today's valuation.
- There is a second opinion on Enel worth weighing. See what analysts think Enel's shares could be worth.
For investors, the debate is whether Enel's current earnings are strong and resilient enough to make the present share price look well supported.
To stress test what Enel's recent gains might mean for you, it can help to line its earnings story up against other power grid technology players in the 44 power grid technology and infrastructure stocks.
Where Does Enel Sit on Earnings?
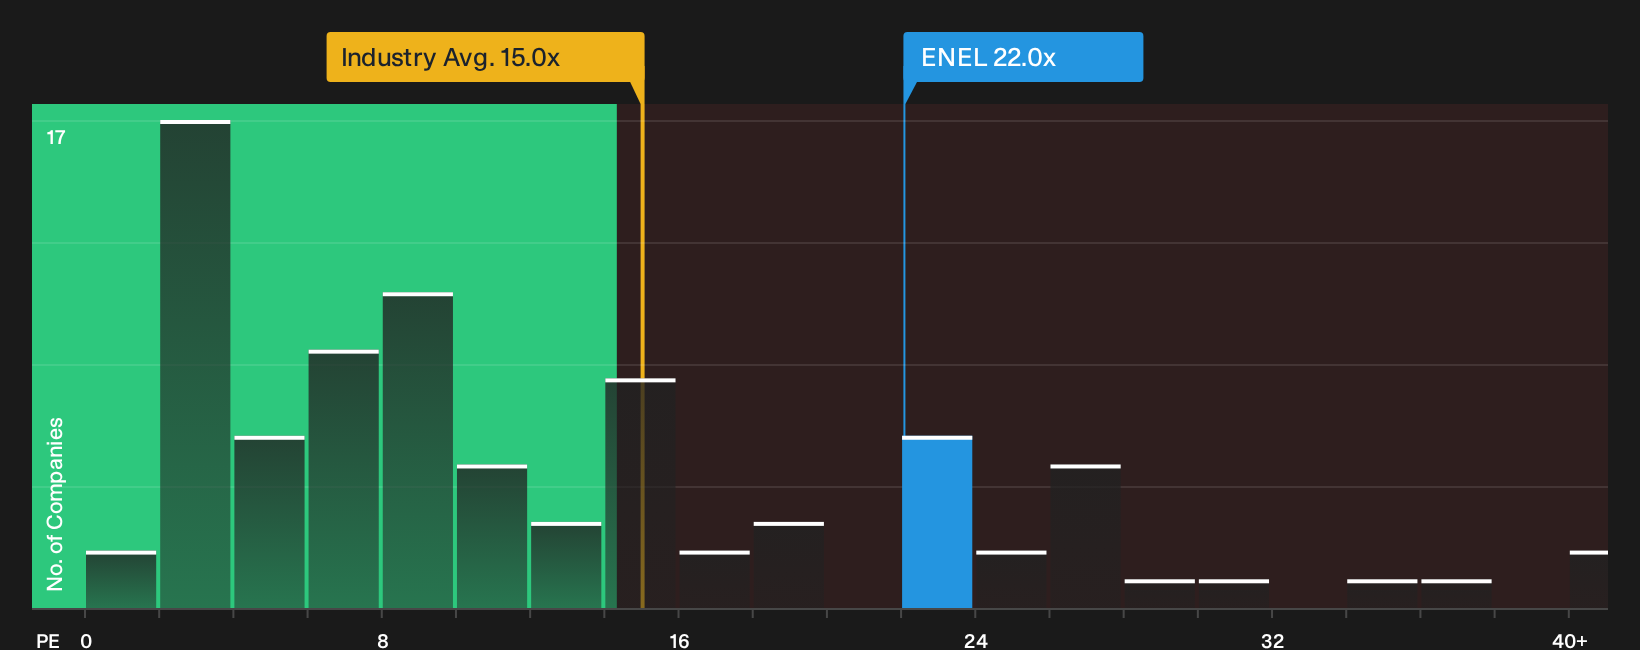
The P/E works well for Enel because earnings remain a central yardstick for regulated utilities. On this measure, the stock trades on about 22.0x earnings, compared with roughly 14.4x for the wider Electric Utilities sector. That points to investors assigning a richer price to each euro of profit than the sector average.
Against closer peers, Enel changes hands at a similar level to the group, with the peer basket around 19.4x and a tailored fair P/E a little above the current figure. Because Enel Green Power is pushing into storage and grid modernisation projects, the current rating suggests the market is willing to pay a modest premium for that earnings mix rather than a steep one. If you hold or are considering Enel, the key question is whether the quality and resilience of future profits justify paying roughly this P/E compared with both direct rivals and more vanilla utilities. Explore the numbers behind Enel's P/E valuation.
The Enel Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Enel's P/E puzzle leaves off by spelling out which assumptions about future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today's price, and they sit on the Community page. Rather than a single multiple or model, each one unpacks the drivers behind its view of fair value so you can compare those inputs with Enel's results as they come through.
One of the top narratives on Enel: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Enel is increasing the share of earnings from regulated grids and Tier 1 markets, with networks already contributing just over 40% of EBITDA and RAB around €49 to €50b…"
Discover why this Narrative puts Enel at roughly fairly valued.
Enel's price is only one clue; the next is what professionals think the earnings profile could look like a few years from now
There is a whole extra layer to Enel once you compare today's valuation with how research analysts currently map out the business a few years ahead. Explore where analysts expect Enel to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com