


EN
Interpretation of US IPOs | Ningtai Mold (NTMJ.US): From a small factory in Jiangyan to NASDAQ, the 30-year test of a mold factory in the US
Ningtai Mold, which has the resources of two well-known customers, LG Electronics (Taizhou Lejin Electronic Chiller) and TCL Home Appliance (Hefei), has begun a new listing journey in the US.
The Zhitong Finance App observed that after secretly submitting the form to the SEC on November 12, 2025, Ningtai Mold submitted a public prospectus (F-1 document) to the SEC on May 26 this year to apply for listing on the NASDAQ under the “NTMJ” code.
According to the prospectus, Ningtai Mold plans to issue 6.25 million Class A common shares in this IPO, with a pricing range of 4 to 5 US dollars per share. Even when estimated at a lower limit of 4 US dollars, the total amount raised reached 25 million US dollars, which just hit the regulatory red line set by NASDAQ for Chinese issuers with a “minimum public offering amount not less than 25 million US dollars.”
If the price is set at the upper limit of $5, the maximum amount raised can be up to $31.25 million. This distribution structure shows that Ningtai Model intends to anchor pricing above the compliance bottom line, not only to ensure listing eligibility, but also to leave room for subsequent valuation games.
However, Ningtai Mold's performance is not optimistic. In 2025, the company's revenue was US$18.6762 million, up 20.11% year on year, but net profit for the period was about US$16.675 million, down 4.46% year on year. Obviously, this is a “increase in revenue does not increase profit” questionnaire.
Industry coverage continues to expand, with 62 customers in 2025
As a “veteran” in the industry, Ningtai Mold has been deeply involved in the field of molds and injection molding products for nearly 30 years.
Back in 1996, Wang Changxuan, the founder of the company, started in Jiangyan, Taizhou, focusing on the development and manufacture of high-precision molds and injection molding products. Wang Changxuan led the company to quickly gain a foothold in the Taizhou mold and home appliance support industry with 6 years before the company was founded.
By around 2004, Ningtai Mold customers expanded into the “fast track”, and the company began business contacts with Chunlan Air Conditioning, LG, Yueda Kia, etc., laying a solid foundation for further cooperation.
With the acceleration of customer demand, Ningtai Mold settled in a new factory in Jiangyan in 2014, achieving simultaneous growth in production capacity and delivery capacity.
After the bottleneck in production capacity was overcome, the company's ambition to accept large orders increased significantly. In 2015, Ningtai Mold officially entered the TCL Hefei home appliance supply chain, and the customer layout ushered in a major expansion.
Since then, the company has continued to improve its quality system, successively passing ISO9001 basic quality management system certification and IATF16949 automotive grade system certification in 2016. This means that Ningtai Mold has obtained an “entry ticket” for the automobile supply chain, and the business boundary has expanded from the specific household appliance model system to the automotive sector.
Around 2017, Ningtai Mold obtained import and export qualifications, and began to have overseas test orders from South Korea and India, officially starting the company's “overseas” path.
Since then, the development of Ningtai Mold has entered a steady period. The production capacity of the company's two core businesses, molds and injection parts, has continued to be released, and the scale has steadily climbed. The industry coverage has also expanded to various fields such as consumer electronics, home appliances, automobiles (interior/exterior and structural parts), and die-casting support. In 2025, the company's total number of active customers increased to 62.
It was also in this year that Ningtai Mold set up a red chip structure and sounded the “trumpet” of sprinting to a US stock IPO. From Jiangyan to NASDAQ, the growth story of this Taizhou mold factory has finally reached a critical point where it needs to be tested by the capital market.
Custom injection mold revenue surged 68.5%, becoming the main driving force for total revenue growth
If we thoroughly analyze Ningtai Mold's performance of “increasing revenue without increasing profit” in 2025, we can see that this is a typical true picture of traditional manufacturing enterprises operating under “fluctuating project structures+major customer dependency”.
According to the prospectus, Ningtai Mold's total revenue in 2025 increased by 20.1% to 18.6762 million US dollars, mainly driven by a 68.5% increase in custom injection mold revenue.
During the reporting period, due to increased demand from the largest customer, LG Electronics (Taizhou Lejin Electronic Chillers), this led to a 13.7% increase in sales of custom injection molds. Combined with an increase in the value of single molds, the average unit price increased by 48.2%.
After achieving a “sharp rise in volume and price”, the share of custom injection molds in the company's total revenue increased from 29.86% to 41.88% in 2025, becoming the main engine driving the company's revenue growth.
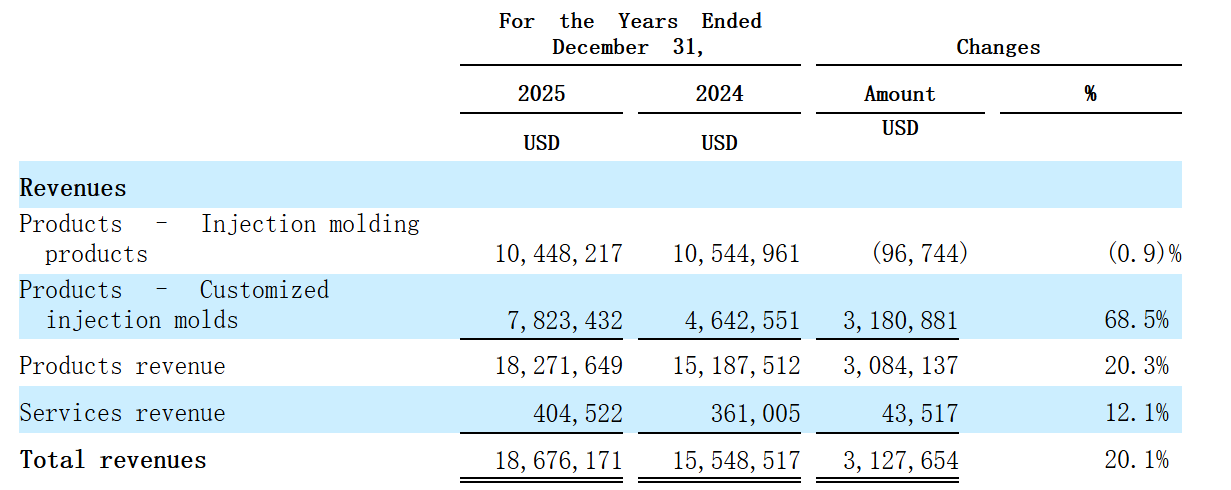
The revenue of the injection molding business during the reporting period was US$10.4482 million, a slight decrease of 0.9% over the previous year, and its share of total revenue fell from 67.20% to 55.94%, showing an overall steady trend.
However, due to the increase in the revenue share of the low-margin custom injection mold business and the expansion of production personnel to undertake projects such as LG Taizhou, this caused the overall gross margin of Ningtai Mold to drop from 20.97% to 17.54% during the reporting period, a drop of more than 3 percentage points, and a decrease in profitability.
On this basis, the increase in sales expenses led to an increase in operating expenses, which further suppressed the company's profit release space. During the reporting period, transportation costs rose significantly due to the increase in orders, which led to a 50.5% increase in the company's sales expenses, which led to a 16.5% increase in total operating expenses to about US$1.8 million.
It can be seen from this that Ningtai Mold's revenue growth in 2025 was mainly driven by the growth in demand from a single major customer, and changes in revenue structure and growth in sales expenses together affected the company's profit side.
But that's not the whole story. Dismantled from the bottom of the business model, Ningtai Mold's business resilience may face torture. Custom injection molds are a typical project manufacturing business. The delivery cycle is long, and revenue is confirmed once at the inspection point. Naturally, there is a “pulse” rather than a “linear growth”. Once projects are settled centrally at a certain stage and new projects fail to keep up in time, the growth of this business may come to an abrupt halt.
However, the injection molded parts business is a standardized product, with a stable shipping pace and relatively high gross margin, which is a more reliable profit base than the custom injection mold business. Although revenue from this business declined only slightly in 2025, if growth is not regained in the future, the company's basic market may continue to lose blood.
In addition to this, high dependence on a single customer will also be a potential risk for Ningtai Mold to achieve steady operation. According to the prospectus, although Ningtai Mold had 62 active customers in 2025, the revenue share from the largest customer “Taizhou Lejin Electronic Chiller” was as high as 67.8%, approaching 70%, a further increase of more than 7 percentage points from 60.3% in 2024. Obviously, reducing customer concentration has become a pain point that Ningtai Mold urgently needs to solve.
The four dimensions of implementation progress have become the key to the company's valuation
In addition to business management challenges, Ningtai Mold also has a breaking point. From an industry perspective, China is already the world's largest mold producer, and the industry's output value continues to rise steadily, from about 343.2 billion yuan in 2023 to about 380 billion yuan in 2025. The market anticipates that in 2026, the market is expected to further increase to 397.5 billion yuan, an increase of 4.6% over the previous year.
The huge market of 300 billion dollars has maintained steady growth, indicating that there are still incremental opportunities in the market, and the field of household appliance molds is one of them. According to Ningtai Mold's prospectus, the home appliance mold market is about 45 billion yuan in 2025, and is expected to grow to about 65 billion yuan in 2030, with a compound annual growth rate of about 7.5%.
However, the home appliance mold field is the basic plate of Ningtai Mold. Behind the company's largest customer, Taizhou Lejin Electronic Chiller, is the global home appliance giant LG, and the company previously deeply served TCL Household Appliances (Hefei). This shows that its deep accumulation in the field of home appliances is expected to benefit from the continuous growth of the industry.
While deeply involved in the field of home appliances, the highlight of Ningtai Mold is that it already has a presence in other industries. The downstream products of the company already cover consumer electronics, automobile manufacturing, pressure die casting and other industries. If the company continues to expand into other industries in the future, it may open up room for future growth.
It is worth noting that the mold industry's own upgrading wave may also become an opportunity for Ningtai Mold to grow. Currently, the industry is experiencing three trends. One is the evolution of the manufacturing end to intelligence to reduce production costs; the second is product-end refinement and high-end upgrading, and demand for complex structural parts and multi-material molding increases the added value of molds; the third is that overseas travel has changed from “optional” to “mandatory”, and demand for mold support from manufacturing destinations such as Southeast Asia and India is being released.
If Ningtai Mold can seize the above trends, its growth logic may be able to switch from “highly dependent on a single customer” to a “precision manufacturing platform that adapts to industrial upgrading,” and the fund-raising plan in the prospectus just provides a road map for this transition.
According to the prospectus, the net capital raised by Ningtai Mold will mainly be used for three areas: upgrading and procurement of production equipment, expansion of production facilities, and investment in R&D. This shows that the company has begun to increase investment in high-precision machining centers, CNC machine tools, etc. on the manufacturing side, and the company's R&D expenses will be invested in mold design and development, new material/new process testing, and promote the high-end upgrading of the company's products.
Overall, after relying too much on a single customer and causing an imbalance in the business structure, Ningtai Mold has shown a phased “increase in revenue without increasing profit”. Whether this situation can be broken depends on the company's implementation progress at the four levels of diversification and expansion of the industry, intelligent upgrading on the manufacturing side, upgrading high-end products, and overseas results. This will not only determine the company's performance in the next few years, but will also determine its valuation level after listing. The market is waiting to see what step Ningtai Mold can take.