


EN
Cui Dongshu: The national passenger car industry will stock 3.34 million vehicles for 60 days at the end of October 2026
The Zhitong Finance App learned that Cui Dongshu, Secretary General of the Passenger Transport Federation, published an article stating that at the end of October 2026, the national passenger car industry had inventory of 3.34 million vehicles, an increase of 130,000 units over the previous month and a decrease of 70,000 units from October 2025, which is characterized by a continuous recovery in inventory in September-October. The forecasting team was optimistic about the market forecast for 2025, and satisfaction continued to plummet to a low level starting in October 2025. Optimism in October 2026 was 23%, and satisfaction was 21% after October in early November. Expectations were low but satisfaction was poor, mainly because the impact of high oil prices was too great.
Based on inventory at the end of October 2026 and a comprehensive estimate of domestic retail sales for the next 3 months, the number of future sales days is 60 days. Compared with 50 days in October 2023, 49 days in October 2024, and 61 days in October 2025, the overall inventory days in October this year are still under relative pressure.
Judging from the analysis of inventory change characteristics of companies that only produce new energy vehicles, the inventory of 200,000 units was in early 2023, and then entered a period of rapid inventory growth. In April 2025, the inventory of companies that only produce new energy vehicles reached 880,000 units. This is a recent peak. In October 2026, the total inventory of companies that only produce new energy vehicles rose to 980,000 units, an increase of 100,000 units over the previous month, and 200,000 units from the peak inventory of 780,000 in November 2025, reaching a record high.
1. Passenger car retail trends in the narrow sense of the word in recent years
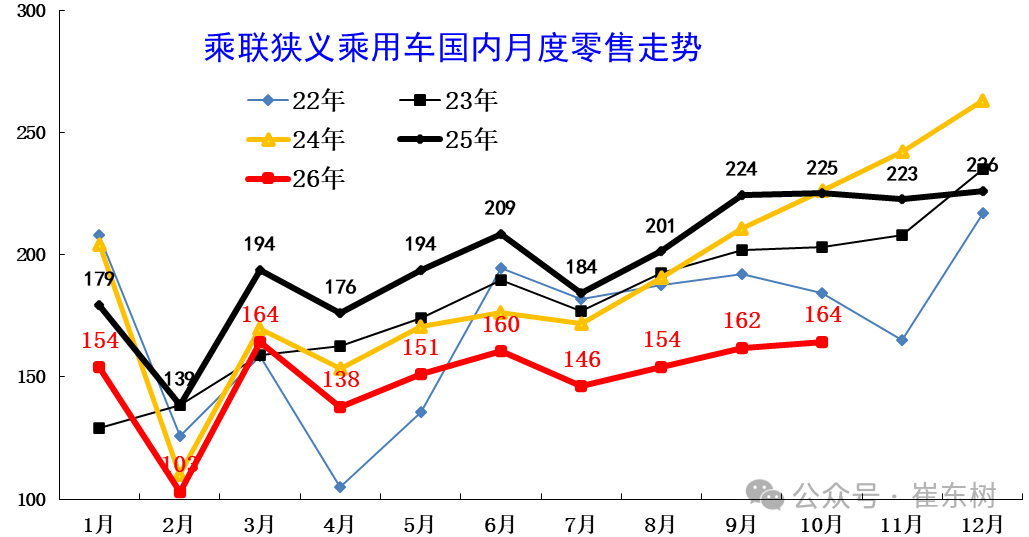
The national passenger car market retailed 1.64 million vehicles in October, and continued to grow at a low level in August-October, but not higher than retail sales in March. There are many reasons for the low sales volume in October, mainly due to high oil prices. The underlying reason is low consumption capacity and desire.
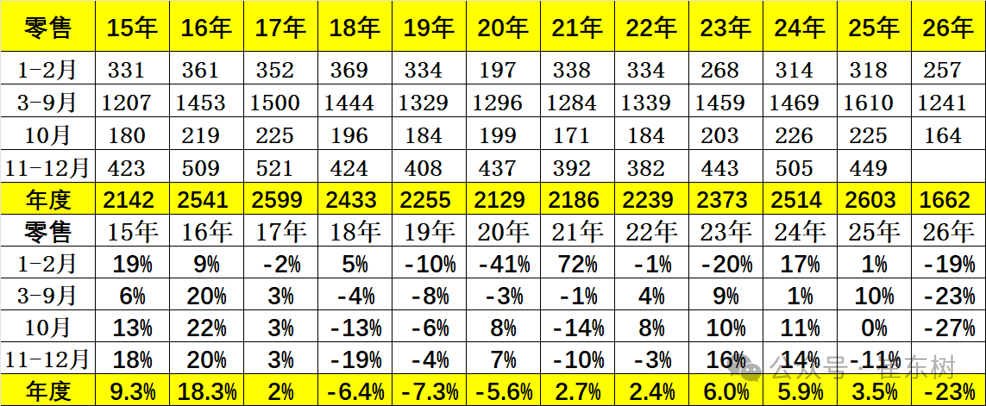
In October 2026, the national passenger car market retailed 1.643 million vehicles, down 27% year on year, up 1% month on month; from January to October, the total retail sales of passenger cars was 16.62 million units, down 23% year on year.
In October 2026, the domestic passenger car market showed a trend of continuous total pressure, month-on-month strengthening, and extreme structural differentiation.
2. Passenger car wholesale trends in the narrow sense of the word in recent years
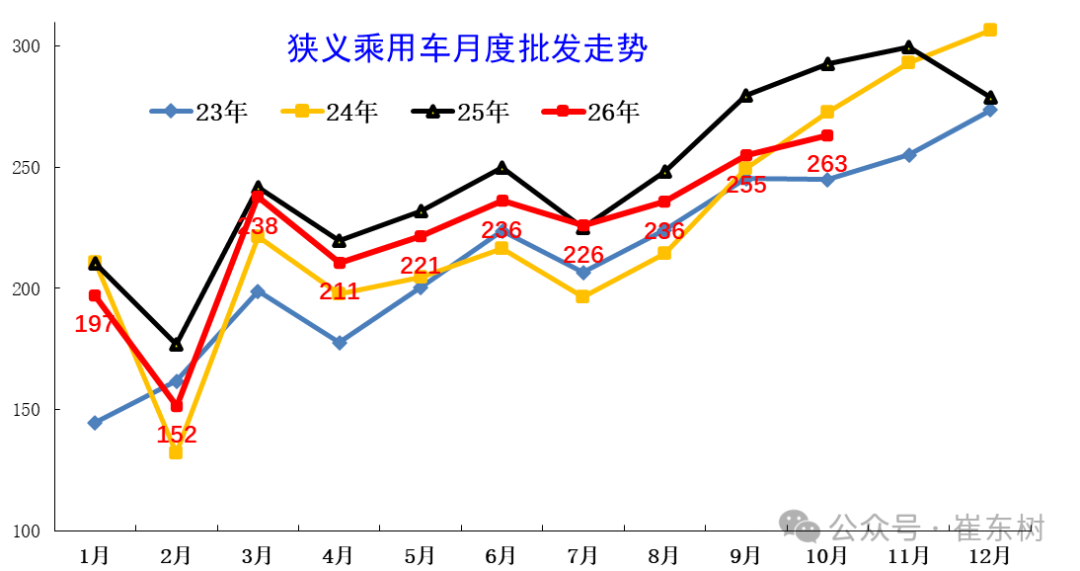
Passenger car manufacturers across the country wholesale 2.63 million vehicles in October, a significant decline over the same period. The trend in October of previous years was relatively strong. The domestic economy was sluggish but export growth was high this year, so the overall return was stable. Due to strong exports, few domestic wholesalers, and good inventory removal results, channel pressure has improved markedly.
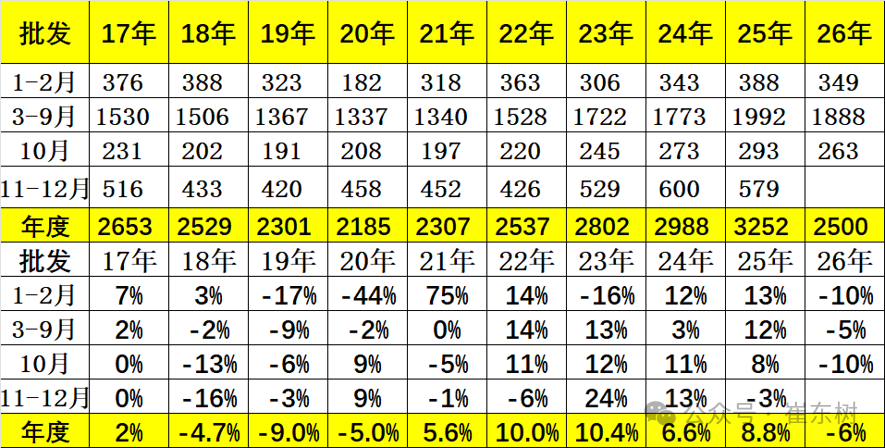
In October, passenger car manufacturers across the country sold 2.633 million vehicles, down 10.2% year on year and up 3.3% month on month. Encouraged by the surge in exports, the year-on-year growth rate of passenger car wholesale in October was 17 percentage points higher than the retail growth rate.
3. Recent trends in passenger car production in the narrow sense
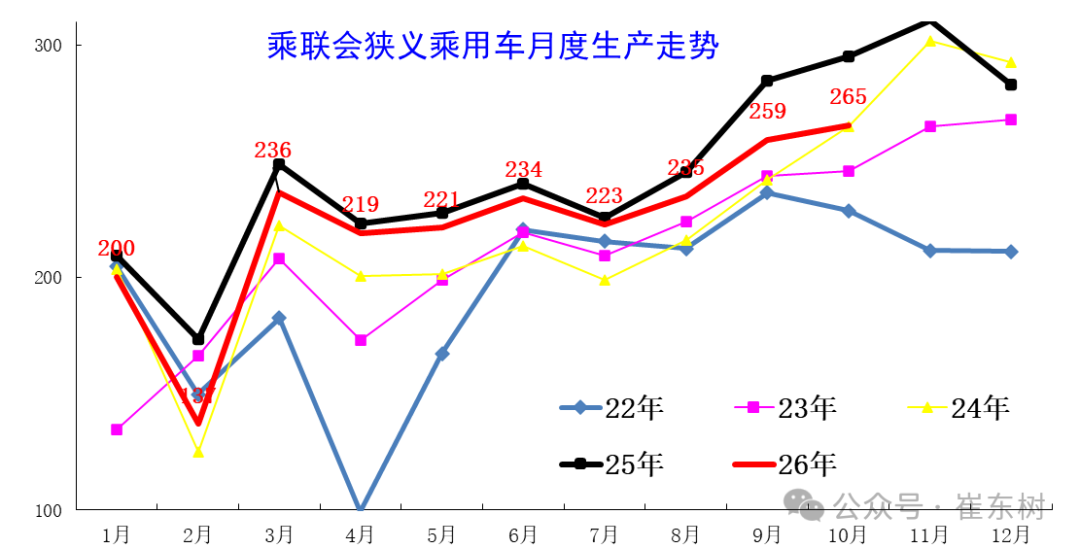
Passenger car production will be drastically reduced in 2026. Production increased steadily in September-October, which is a big contrast to the strong increase in 2025. Exports continued to strengthen this year, leading to a relatively high in October production during the year, but the year-on-year trend declined significantly.
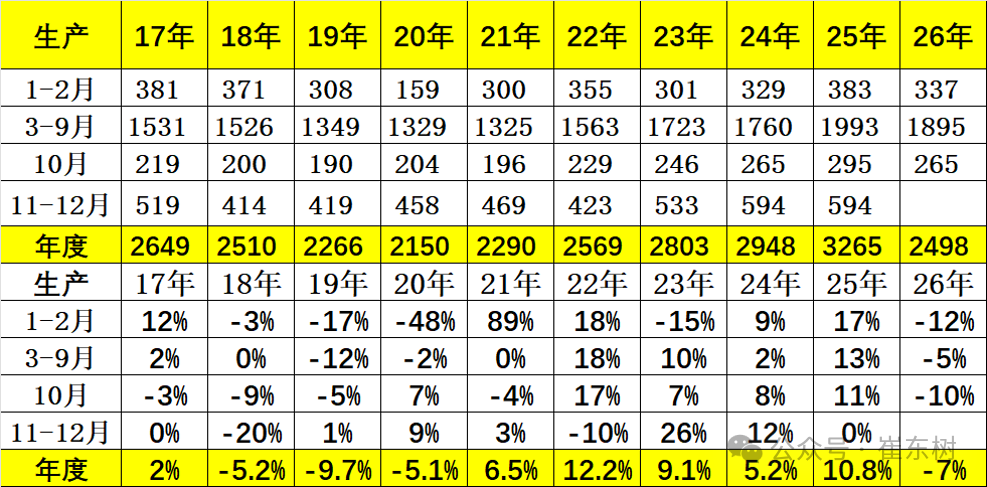
Passenger car production in October was 2.65 million units, down 10% year on year, with a cumulative decrease of 7% in 2026. The decline was significant in October 2025 under the ultra-high base figure.
4. Recent passenger car export trends in the narrow sense
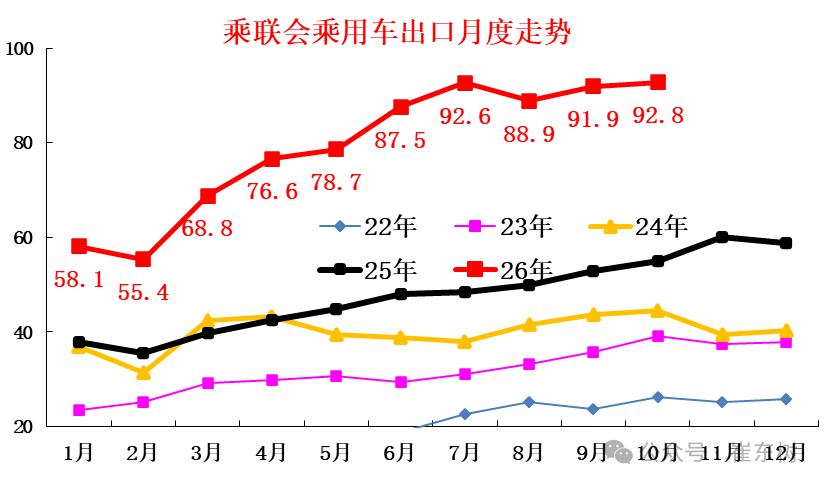
Exports rebounded slightly in October compared to September, but basically strengthened for 4 consecutive months. The month-on-month rapid month-on-month upward trend changed, and the market gradually entered a stable period.
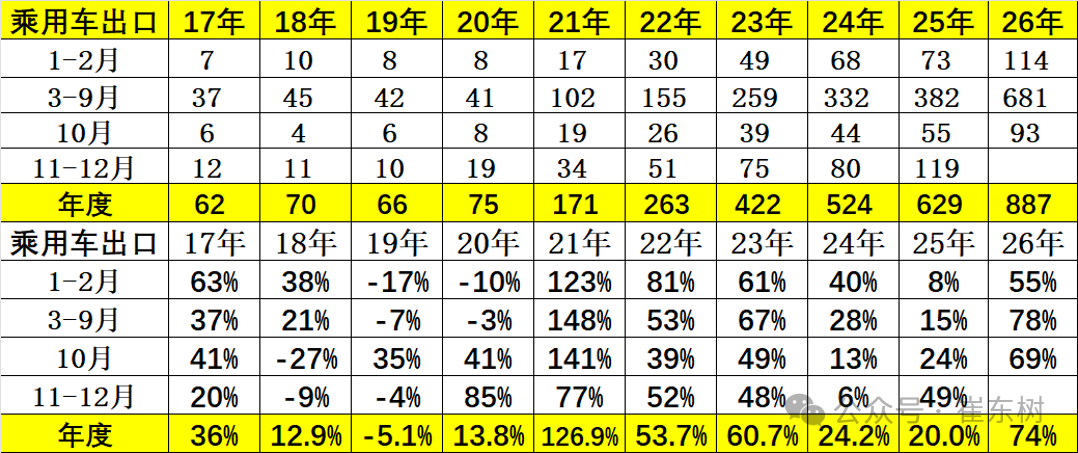
Passenger car exports (including complete vehicles and CKD) reached 928,000 units in October, up 68.5% year on year and 1.0% month on month, accounting for 35% of passenger car manufacturers' sales volume (36% last month, 19% in the same period in 2025).
5. National passenger car industry inventory tracking
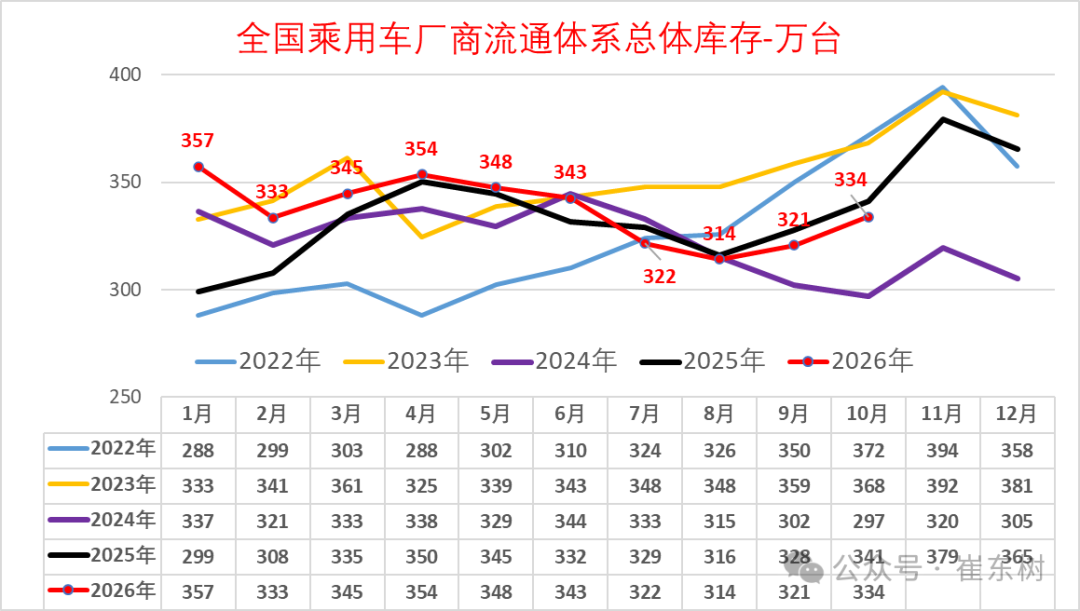
At the end of October 2026, the national passenger car industry inventories were 3.34 million units, an increase of 130,000 units over the previous month and a decrease of 70,000 units from October 2025, which is characterized by a continuous recovery in inventory in September-October. The launch of the trade-in policy in 2025 brought about overall optimism among manufacturers. The sales volume driven by trade-in was high, and manufacturers were relatively cautious in production, resulting in continuous inventory removal from May to October. Since the market has seriously fallen short of expectations since November last year, inventories hit a new high of nearly two years in November. Since then, the decline in production has been strong, but the decline in retail sales in the first half of the year also exceeded expectations. As a result, inventories were high in the first half of the year. Production cuts in July-October were strong, and inventories dropped significantly compared to the same period. The characteristics of this year's inventory changes are relatively mild to those of the past few years.
6. National passenger car manufacturer inventory tracking
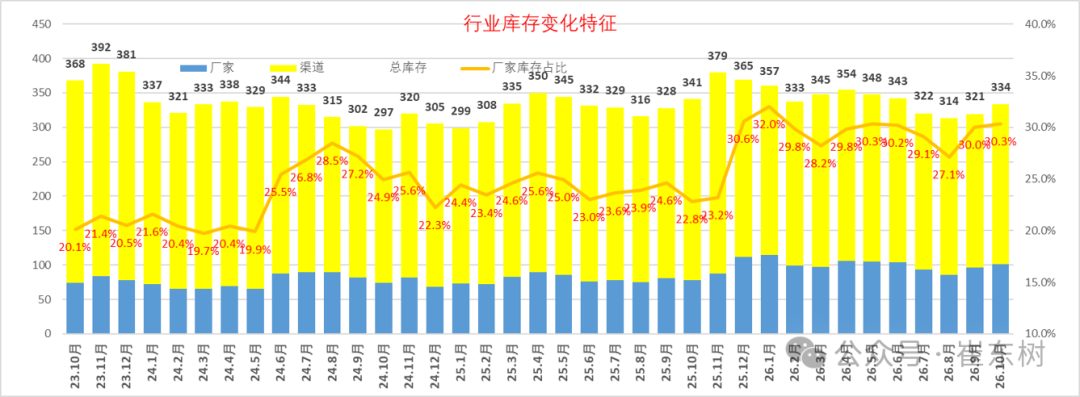
Since 2023, the overall inventory of the passenger car industry has remained relatively stable. It fell back to around 2.97 million units in October 2024, rebounded to 3.79 million units in November 2025, then declined. Inventory in October 2026 fell to 3.34 million units, of which the manufacturer's inventory accounted for 30.3%, and the inventory from manufacturer vacations in September was made up in October.
Due to good market expectations in the early stages, manufacturers are enthusiastic about production, and overall industry inventory pressure is relatively uncontrollable. Currently, the share of manufacturers' inventory is gradually increasing, the market is seriously sluggish, manufacturers are cutting production, and the inventory pressure to absorb strong sales in the next few months is generally manageable.
7. National Passenger Vehicle Market Forecast Index and Satisfaction Index
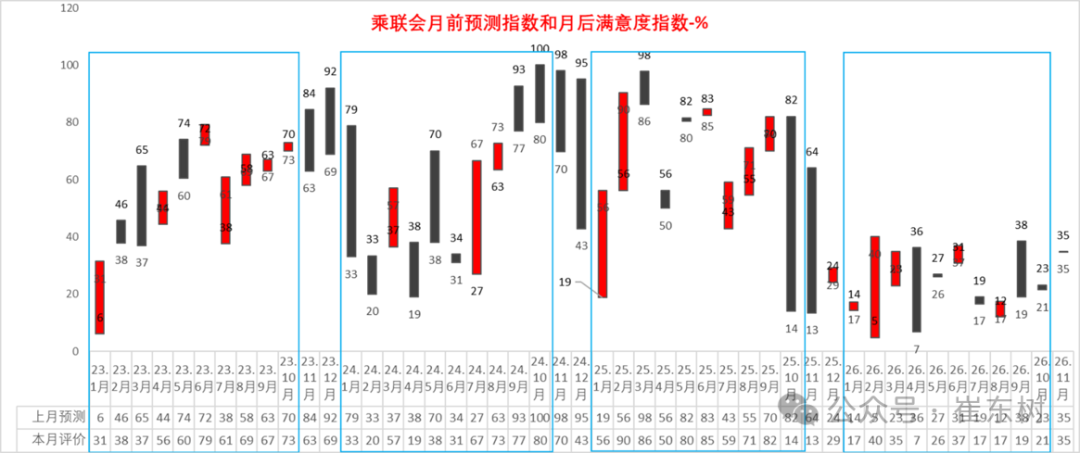
Monthly market performance is evaluated according to how the PMI index is set and evaluation results. According to the forecast summary estimates of the manufacturer's insiders, the prediction team of the Chengdu Branch has been very optimistic and gradually pessimistic since the beginning of 2025. The forecasting team was very optimistic about the market forecast from January to October 2025, and satisfaction continued to plummet to a low level starting in October 2025. Optimism in October 2026 was 23%, and satisfaction was 21% after October in early November. Expectations were low but satisfaction was poor, mainly because the impact of high oil prices was too great.
The team's optimism about the November market rose to 35%. This is a high forecast index for judging market optimism recently, but it is lower than 38% in September, which shows that everyone is more cautious.
From the current inventory level of 3.34 million vehicles and expectations to judging market growth in the next few months, there is no pressure to absorb the industry's inventory. In view of the current situation where sales continue to fall short of expectations, car companies need to promptly track changes in the policy environment and market, carefully set the pace of production and sales, carefully increase inventory according to the dealer inventory structure, and clean up historical inventory in a timely manner.
8. Overall inventory characteristics of the national passenger car market
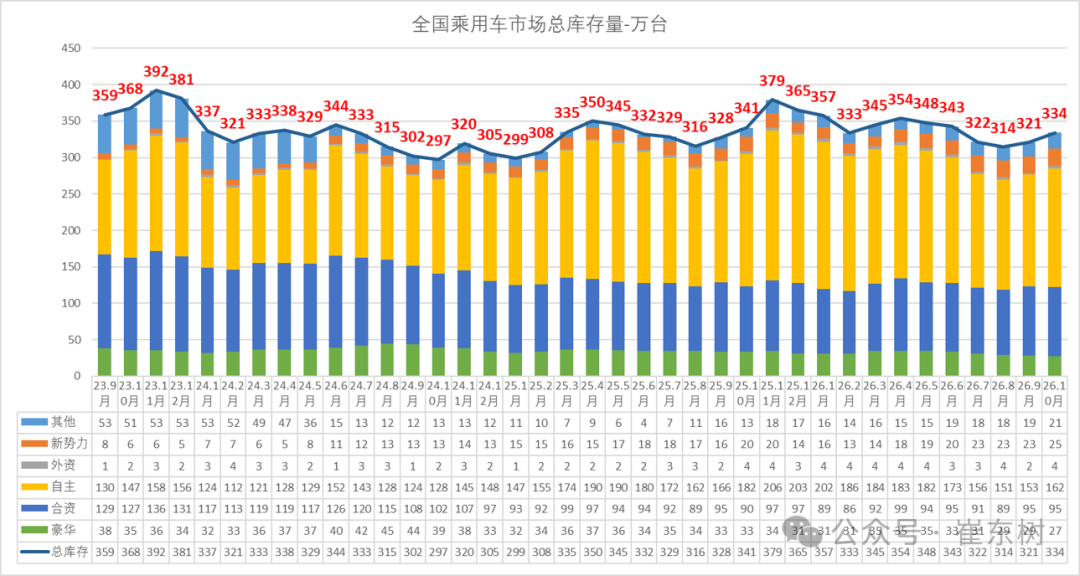
As the share of new energy vehicles increased, fuel vehicle sales declined, and the corresponding inventory pressure gradually decreased. Looking at the inventory cycle, from 3.25 million units in April 2023, then rebounded to 3.92 million units in November 2023, then declined to a low inventory level of 2.97 million units in October 2024.
The inventory cycle from 2025 to early 2026 is still increasing, and the pressure on the industry continues to increase, reaching a recent high of 3.79 million vehicles in November 2025. The car market declined significantly in 2026. Due to the severe contraction of fuel vehicles, although inventories declined, the pressure on inventories was not effectively relieved.
9. US passenger car industry inventory comparison
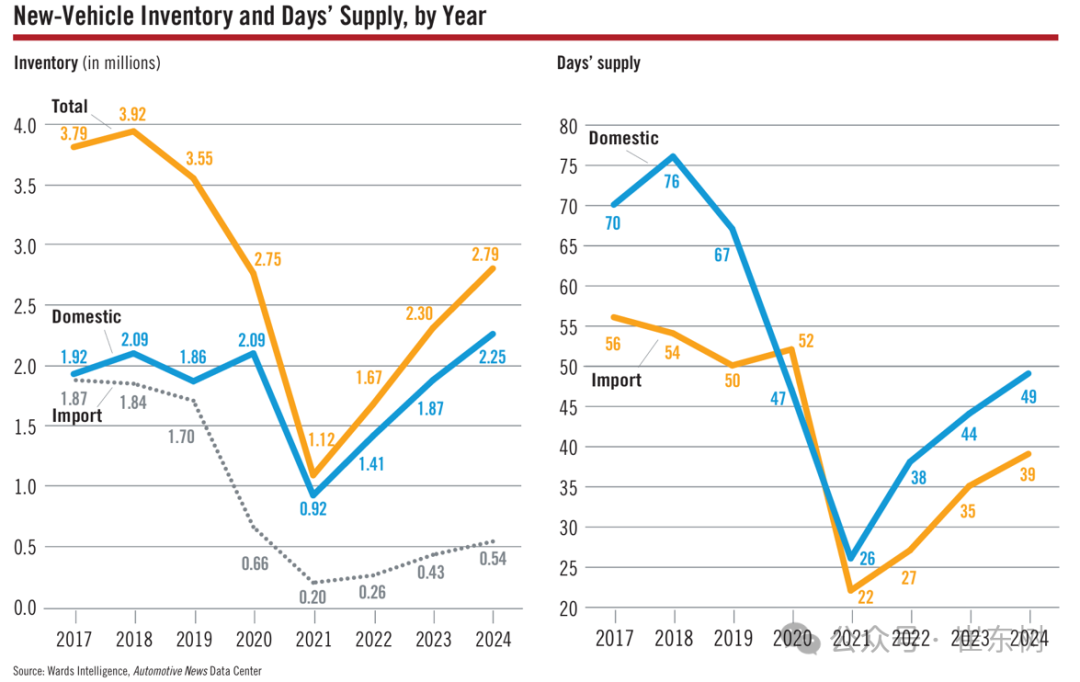
The US inventory is currently in 40-50 days, and the overall inventory pressure is low. This is also a reference target for the Chinese car market.
10. The number of inventory days in the national passenger car market declined slightly
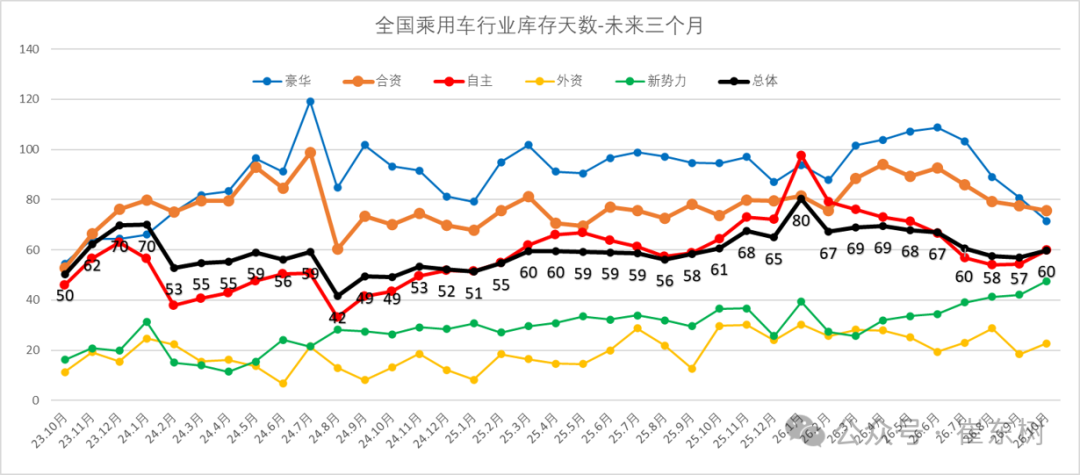
The estimated number of inventory days is based on the sales volume for the next 3 months, but since retail sales in October are lower than expected, the corresponding number of inventory days will also change as a result, that is, how much inventory will be at the end of October, mainly depending on sales expectations for the next 3 months. As the market recovery arrived as scheduled in 2025, the production trend was strong. The characteristics of inventory removal in the early stages changed, and the reverse internal volume brought about inventory control in the industry, and inventory growth was relatively moderate. In the fourth quarter of 2025, although the expiration of the tax exemption policy was promoted, the trend actually fell short of expectations. The peak number of days in industry inventory rebounded to 80 days, and production cuts were strong in 2026. Therefore, based on inventory at the end of October 2026 and the current inventory based on a comprehensive estimate of domestic retail sales volume for the next 3 months, the number of future sales days is 60 days. Compared with 50 days in October 2023, 49 days in October 2024, and 61 days in October 2025, the overall number of inventory days in October this year is still relatively under pressure.
11. The national inventory of new energy passenger vehicles continues to rise
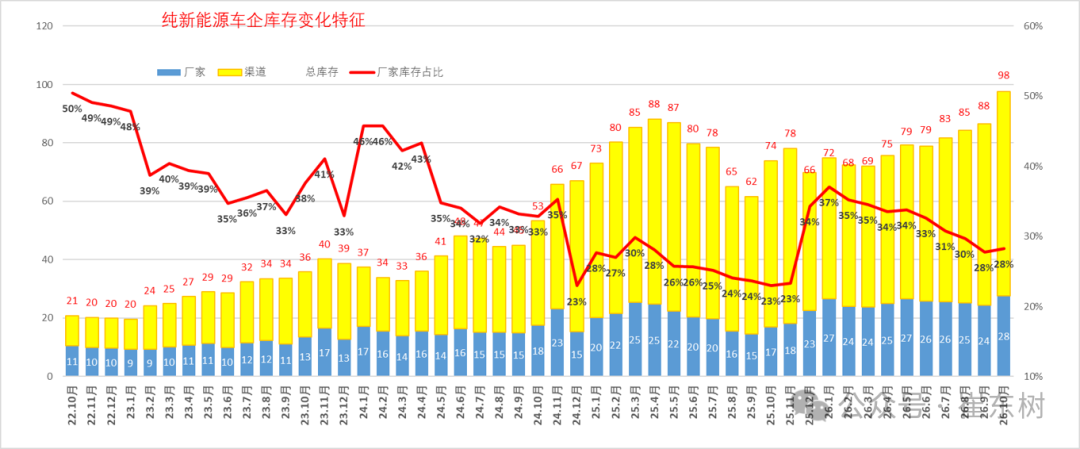
Judging from the analysis of inventory change characteristics of companies that only produce new energy vehicles, the inventory of 200,000 units was in early 2023, and then entered a period of rapid inventory growth. In April 2025, the inventory of companies that only produce new energy vehicles reached 880,000 units. This is a recent peak. With the push of internal scrutiny, industry inventories fell to 620,000 units in September 2025, and the total inventory of companies that only produce new energy vehicles rose to 980,000 units in October 2026, an increase of 100,000 units over the previous month, and 200,000 units from the peak inventory of 780,000 vehicles in November 2025, reaching a record high. Recently, the manufacturer and channel inventories of new energy dealers faced lower than expected retail sales in the market, and the overall pressure on industry inventories was high.