


EN
“Double Eleven” continues to spread good news, Mao Geping (01318) ushered in a critical moment to realize brand value
The 18th “Double Eleven” has come to an end. According to Star Map data, the total e-commerce sales of the entire network reached 1776.4 billion yuan, up 4.8% year on year. Comprehensive e-commerce platforms accounted for 8.2% of personal care and beauty sales. The industry as a whole has moved from the extensive phase of competing for traffic and discounts to a cycle of improving the quality of competing for efficiency and brand power.
Against the backdrop of a slowdown in market growth, perfume makeup, a track that has been controlled by major international brands for a long time, sends a signal worth re-examining the market: the high-end Chinese beauty brand Mao Geping (01318) handed over an extremely valuable contrarian growth report card. Among them, the three “main battlefields” all ranked at the top of the category. The “omni-channel flowering” performance not only confirmed the balance and depth of the company's online operation capabilities, but also verified the “price-for-volume” consumption war of the industry as a whole Lack of value.
The big promotion bucked the trend and accelerated, and the high-end brand strength and business quality continued to be realized
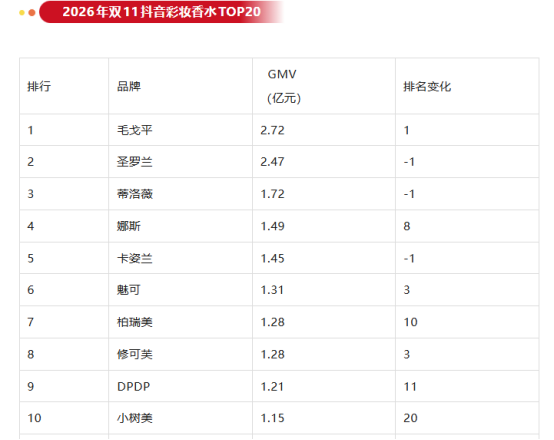
In a macro environment where traffic dividends peaked, platforms collectively tightened their fronts, and discounts returned to rationality, the beauty circuit was clearly divided, and Mao Geping became one of the few players who bucked the trend and accelerated. Third-party data shows that during the Double Eleven promotion period, the company's online omni-channel GMV recorded high double-digit growth, with Tmall's GMV growth rate exceeding 30%, and the Douyin channel's GMV growth rate exceeding 60%. The rankings of all major platforms are progressing steadily. Especially on the Douyin channel, Mao Geping put pressure on Saint Laurent (YSL) to win first place in the cosmetics category.
In fact, this rich “category number one” is hard to come by — international brands have long dominated the high-end beauty circuit. As a high-end local representative, Mao Geping has benefited from the rise in cultural identity and cultural self-confidence. The performance of key nodes such as Double Eleven is an important window for verifying their brand potential.
According to Qingyan data, the total cosmetics transaction volume of Shuang11's online mainstream channel this year was 84.929 billion yuan, a slight decrease of 0.54% year on year. Among them, Douyin makeup perfume GMV was 7.326 billion yuan, down 13.29% year on year. Against the backdrop of market contraction, most of the TOP20 brands recorded a decline, but Mao Geping took first place in this category on the Douyin channel, becoming one of the few brands on the list that bucked the trend and grew positively.
Source: Blue Eyes Intelligence
What is more noteworthy is that this year's Double 11 makeup list presents a “two-sided growth” structure: on the one end are high-end brands with strong brand power and strong professionalism, such as Mao Geping, Saint Laurent, and NARS, and on the other end are affordable up-and-coming brands that rely on low customer orders and low decision costs. Brands in the middle zone are squeezed at both ends. Mao Geping is on the former side, which means that its growth was not exchanged for price cuts, but was actually supported by brand value — at the height of the industry's price war, the gold content of this increase was significantly higher than the GMV figure itself.
Through communication between the Zhitong Finance App and the company's management, during this round of major promotions, the price of the main products promoted by the company remained stable. The level of discounts and the strength of the giveaways were bound within the established framework, and the overall price market was strong. At the same time, the company continued its consistent style of restraint in spending and confirmed that expenses were well controlled.
According to information, most of the GMVs of Douyin's top 20 makeup brands come from the brand's own operation, accounting for more than 40%. Mao Geping is representative of the self-operated drive, that is, he does not rely too much on talent traffic, increases cost efficiency, settles user assets in his own hands, and the certainty of big promotions is also stronger. However, stable, superposition and controllable pricing will eventually be reflected on the profit side.
In other words, the current expansion of Double Eleven is not about exchanging price for volume, but rather high-quality growth that can be settled into actual profit. This is also a key area where Mao Geping, as a high-end brand, distinguishes Mao Geping from other brands in terms of profit margin.
The outstanding performance in the channel dimension further outlines Mao Geping's pattern of balanced strength on multiple platforms: all Tmall cosmetics ranked TOP3, domestic products ranked first, and Dabao remained in the TOP2 in the industry throughout the entire cycle; the Douyin channel had the most outstanding performance, with the store's TOP1, Dabo TOP2, and self-broadcast TOP2, and continued to rise to the top of the Douyin makeup list throughout the promotion cycle; the Jingdong channel achieved a steady upward ranking. The beauty industry ranked TOP22, up 4 places year on year, and the cosmetics industry ranked TOP 5, up 3 places year on year; Vipin Also reaping rank improvements, beauty industry rankings TOP16, up 2 places year on year, makeup industry ranking TOP2, up 2 places year on year.
For Mao Geping, the explosion of this big promotion was not a one-day success, but rather a centralized release of its long-accumulated brand assets and business quality. As a leader in high-end domestic beauty, Mao Geping has successfully built his own “pricing power core”. On the product side, the company has sharpened its sword for ten years, creating an insurmountable benchmark for product strength. On the one hand, its product matrix is becoming more and more perfect. The total number of SKUs increased to 493 in the first half of the year. Retail sales of powder, caviar cushion, and new primer exceeded 300 million yuan, 200 million yuan, and 100 million yuan respectively; the annual retail sales of caviar mask exceeded 1 billion yuan, and the retail sales of dark cream was about 290 million yuan. The complete skincare product line “Yuneng Shaoyan Friday Series” was launched in the second half of the year. The ability to create new products and continue to be popular has been repeatedly tested.
On the other hand, in the medium to long term, the company is rooted in the unique Oriental lighting and visual aesthetic system, and integrates aesthetic expression throughout the entire chain of product formulations, appearance processes, and color schemes. This deep aesthetic design ability not only built a very high brand barrier, but also brought strong bargaining power to the company. During this big promotion period, Mao Geping still insisted on price anchoring, mainly promoting the repurchase of evergreen products, and still “carried on” brand strength and product strength.
Supporting Mao Geping's contrarian growth logic, there is also a highly collaborative online and offline channel system. The company has formed a collaborative pattern of “expanding scale online and building a brand offline” through refined online operation and offline high-end scene creation, and channel value has been deeply unleashed. At the user asset level, as of the end of June, the total number of online and offline members reached 26.8 million, an increase of 37.3% over the previous year, and a comprehensive repurchase rate of 27.2%. The continuous expansion of the customer base and the strengthening of loyalty have laid the most solid foundation for its long-term sustainable growth.
There is plenty of room for long-term growth, or the revaluation of scarce values
After understanding the fundamentals and looking at the pricing given by the capital market, Mao Geping's current investment value becomes more and more clear.
From an industry perspective, Mao Geping is in a structurally favorable position. According to Frost & Sullivan data, Mao Geping's share of China's high-end makeup market in 2025 was 9.56%, ranking second, and the only Chinese brand in the top ten. This time, Double Eleven is a reflection of this share advantage: in Douyin, the fastest-growing makeup market, Mao Geping surpassed YSL to the top of the category, which means that the company has achieved a positive rebound in the high-end price band that international brands have long monopolized.
Research by Guojin Securities also pointed out that the mass price belt is becoming increasingly competitive, and high-end domestic goods must rely on cultural identity and brand narratives to broaden customer base boundaries, and Mao Geping is the most successful example of this path so far. In the first half of 2026, retail sales of cosmetics per unit above the limit increased 6.3% year on year. However, the growth was clearly concentrated on high-end brands with brand power and efficacy endorsements. Mao Geping's revenue growth rate in the first three quarters and Double Eleven's online GMV growth rate all greatly outperformed the industry market, and the logic of the increase in share is clearly visible.
CITIC Securities estimates in the Double Eleven data tracking that it maintains the company's 26E/27E profit forecast of 1,46/1.76 billion yuan, and the price-earnings ratio corresponding to the current market value of about 22.8 billion yuan is only 15.6/13.0 times. The valuation is at the 10% quantile since the company went public, and the dividend rate is expected to continue to increase throughout the year. The current stock price corresponds to a dividend rate of about 3.4%, thus reaffirming its “firm recommendation.” According to the Guangfa Securities Research Report, the company has deep brand assets, a stable mentality for core products, and is optimistic that peak season growth will continue, maintaining Mao Geping's “buy” rating and reasonable value of HK$73.68 per share.
Goldman Sachs also recently released a report stating that Double Eleven's performance exceeded expectations. The company insisted on price discipline to guarantee profit margins, a two-wheel drive for makeup and skincare, and orderly overseas expansion. Management's initiation of a buyback shows confidence, the long-term growth logic is stable, and the “buy” rating is maintained.
Many leading institutions invariably gave Mao Geping a positive “buy/increase” rating in the context of widespread pressure on the industry. The core logic points to the same fact — this is a growth target where fundamentals are scarce and valuations have fully declined.
Taken together, Mao Geping's investment value is reflected in a clear contrast: on the one hand, continuous revenue growth of more than 20%, top profitability in the industry, and scarce brand power leading makeup in the Double Eleven promotion, on the other end, historical undervaluation of 10% since listing and rising shareholder returns. On the high-end beauty circuit, which has long been dominated by international brands and the penetration rate of domestic products is still low, Mao Geping is steadily fulfilling its position as a “scarce high-end domestic product” with professional makeup artist genes, diverse product matrices, and omni-channel collaboration. After the annual test of Double Eleven once again confirmed the resilience of its brand, the market's repricing of this standard may have only just begun.