


EN
A $1 Billion Reason Why SKHY Stock Is in Focus Today
South Korean memory-chip giant SK Hynix (SKHY) announced an initiative worth 1.4 trillion won ($1.05 billion) on Nov. 16 aimed at strengthening the country’s semiconductor supply chain.
The investment, along with new supplier-financing commitments and a major testing-facility project, underscores SKHY’s long-term confidence in semiconductor demand and its leadership in advanced memory.
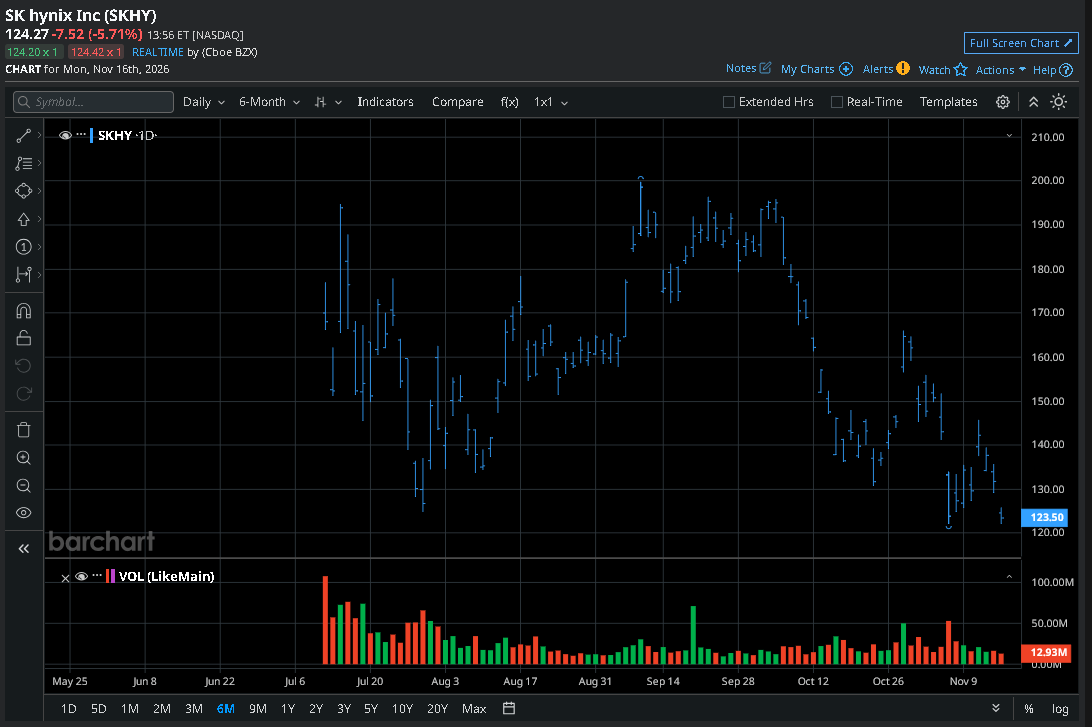
At the time of writing, SK Hynix stock is down more than 35% versus its year-to-date high.
What the Announcement Means for SK Hynix Stock
Over the next five years, SKHY’s investment package will help domestic semiconductor materials, components, and equipment suppliers expand their capabilities.
Crucially, the initiative is designed to offer upfront research funding, low-cost financing, technical consulting, and compensation for development efforts even when projects do not ultimately result in commercial success.
By supporting domestic peers, SK Hynix may reduce supply bottlenecks, materially improve tech-development timelines, and strengthen manufacturing competitiveness over time.
That said, SKHY shares remain decisively below major moving averages (MAs), indicating bears remain firmly in control, at least for the near term.
Should You Invest in SKHY Shares Today?
On Monday, SK Hynix also revealed plans to invest 443.2 billion won in Trinity Fab, a next-gen semiconductor testing center being built within its Yongin cluster. Once operational, the facility will allow suppliers to validate technologies under production-like conditions using 12-inch wafers, potentially boosting qualification timelines by as much as 50%.
Together with an additional 2 trillion won supplier-financing program, the moves signal SK Hynix is investing not only in its own growth but also in the resilience of its broader supply network.
In short, the company’s willingness to pour capital aggressively through industry cycles reinforces one of the strongest bullish arguments for owning SK Hynix shares.
Wall Street Remains Bullish on SK Hynix
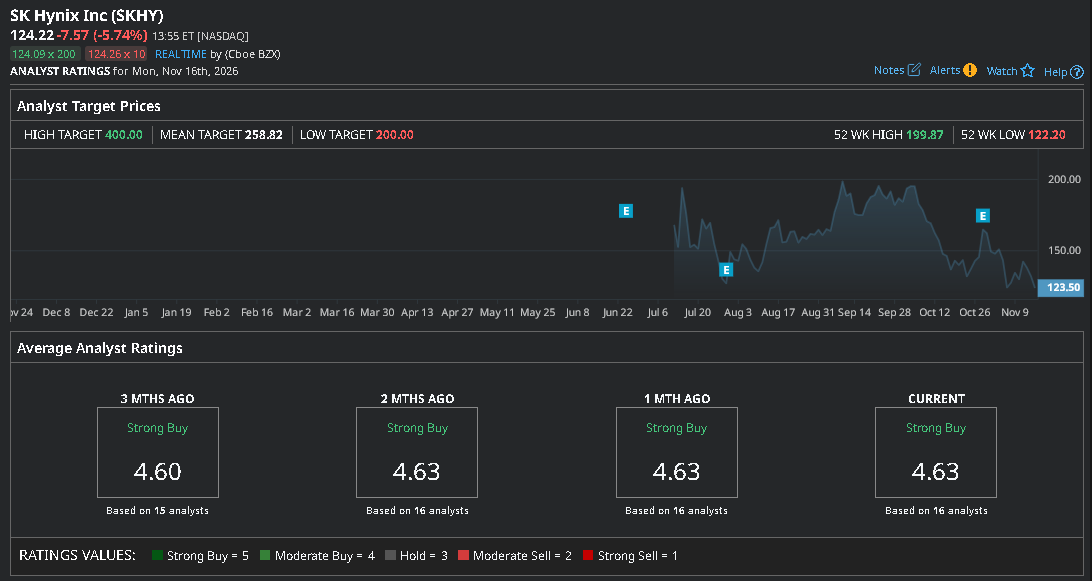
Despite recent underperformance, Wall Street firms remain largely constructive on SKHY stock, believing it will stage a meaningful comeback in 2027.
According to Barchart, the consensus rating on SK Hynix sits at “Strong Buy”, with the mean price target of about $259 indicating potential for a 2x rally from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.