


EN
Powell delivers strong Q3 CY2026 numbers
Electrical energy control systems manufacturer Powell (NYSE:POWL) announced better-than-expected revenue in calendar Q3 2026 [fiscal Q4 2026], with revenue up 33.1% year on year to $396.7 million. Its GAAP profit of $2.23 per share was 43.3% above analysts’ consensus estimates.
For more on Powell, read the full research report, available free.
Powell Q3 CY2026 highlights:
- Revenue $396.7 million vs S&P analysts’ consensus estimates of $331.4 million (33.1% year-on-year growth, 19.7% beat)
- EPS (GAAP) $2.23 vs analysts’ consensus estimates of $1.56 (43.3% beat)
- Operating margin 25.3%, up from 21.2% in the same quarter last year
- Free cash flow margin 2%, down from 19.9% in the same quarter last year
- Backlog $2.7 billion at quarter end, up 92.9% year on year
- Market capitalization $5.2 billion
Brett A. Cope, Powell’s chairman and chief executive officer, stated, “Our fourth quarter marked a strong finish to an exceptional year of progress for Powell. We generated $710 million of new orders(2) in the quarter, with the Oil and Gas market making a substantial contribution, bringing total Fiscal 2026 new orders(2) to a record $2.6 billion. The quarter included two mega(5) orders, one in the LNG end market and the other in the data center market, each reflecting the scale of our project capabilities and the trust our customers place in our team. Our employees continued to drive productivity improvements across our operations while navigating macro inflationary pressures and advancing our plans to thoughtfully expand capacity. This disciplined approach contributed to a full-year Fiscal 2026 gross margin of 31.3%, a 190-basis-point improvement compared with the prior year. At the same time, we ended the year with record backlog(4) of $2.7 billion and a full-year book-to-bill ratio(3) of 2.0x.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Over the last five years, Powell grew its revenue at a strong 21.7% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
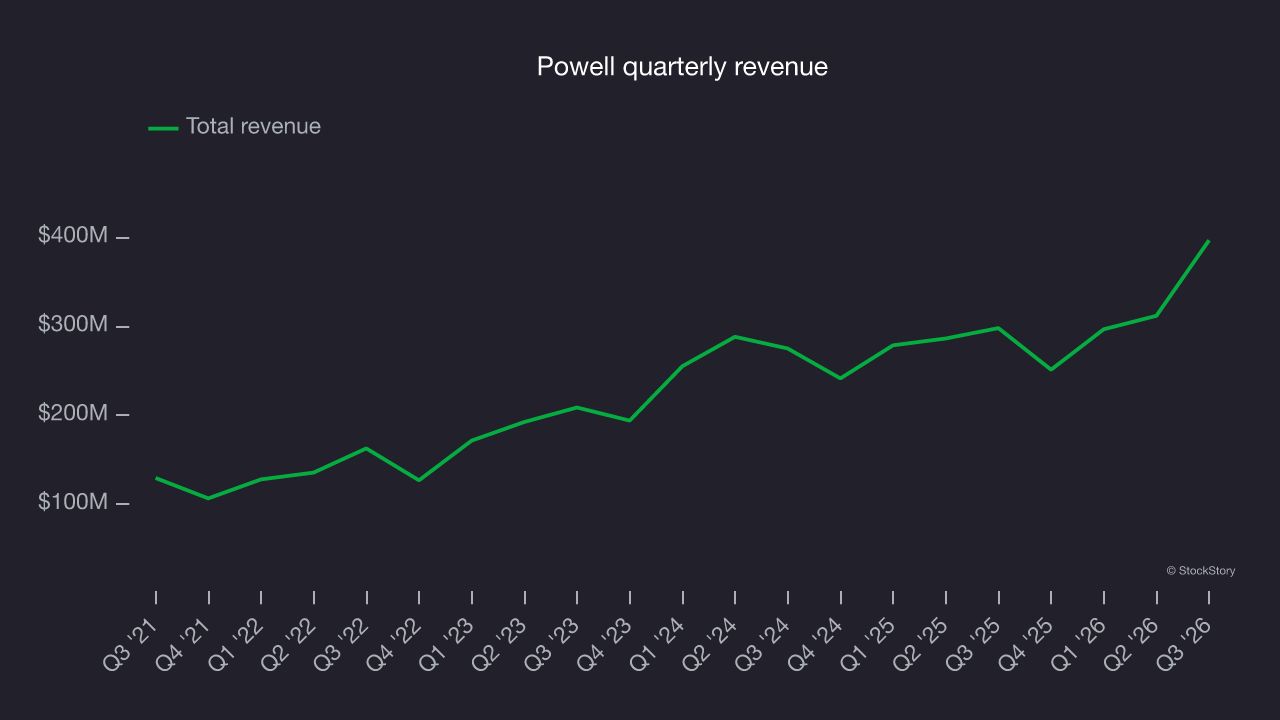
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Powell’s annualized revenue growth of 11.4% over the last two years is below its five-year trend, but the results still suggest healthy demand. 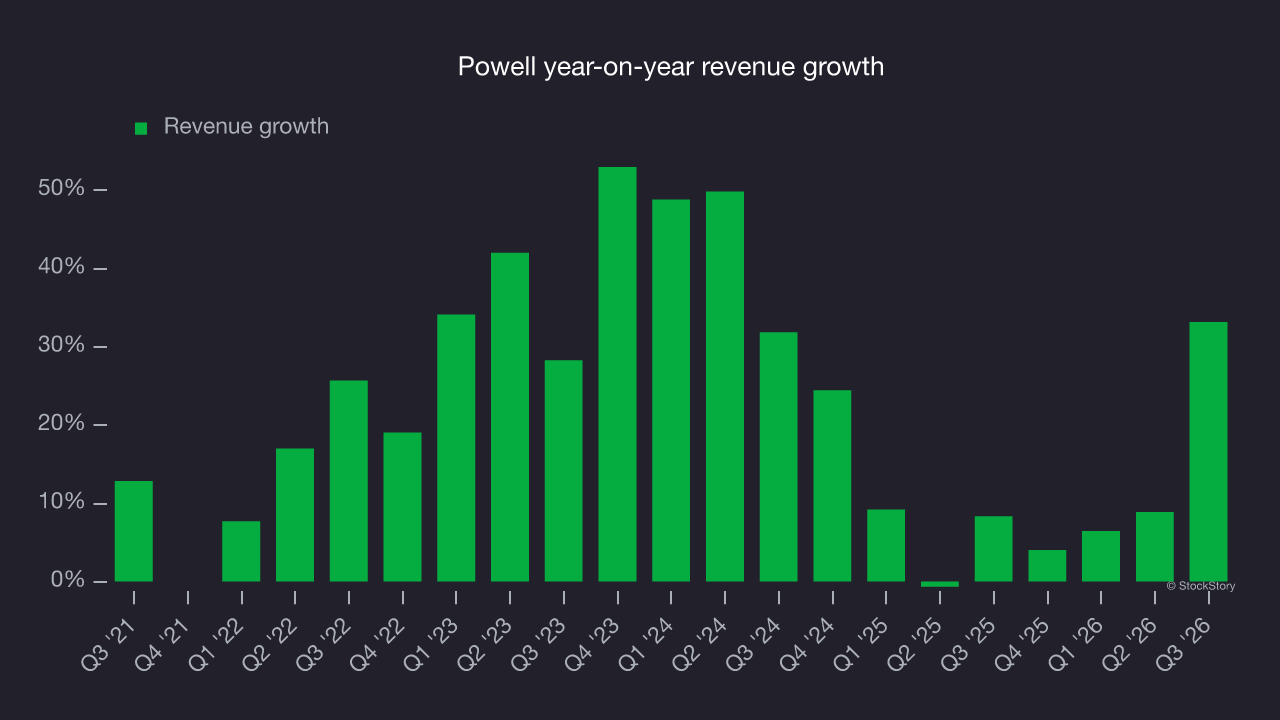
Powell also reports its backlog, or the value of its outstanding orders that have not yet been executed or delivered. Powell’s backlog reached $2.7 billion in the latest quarter and averaged 46.7% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating that the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for Powell’s products and services but raises concerns about capacity constraints. 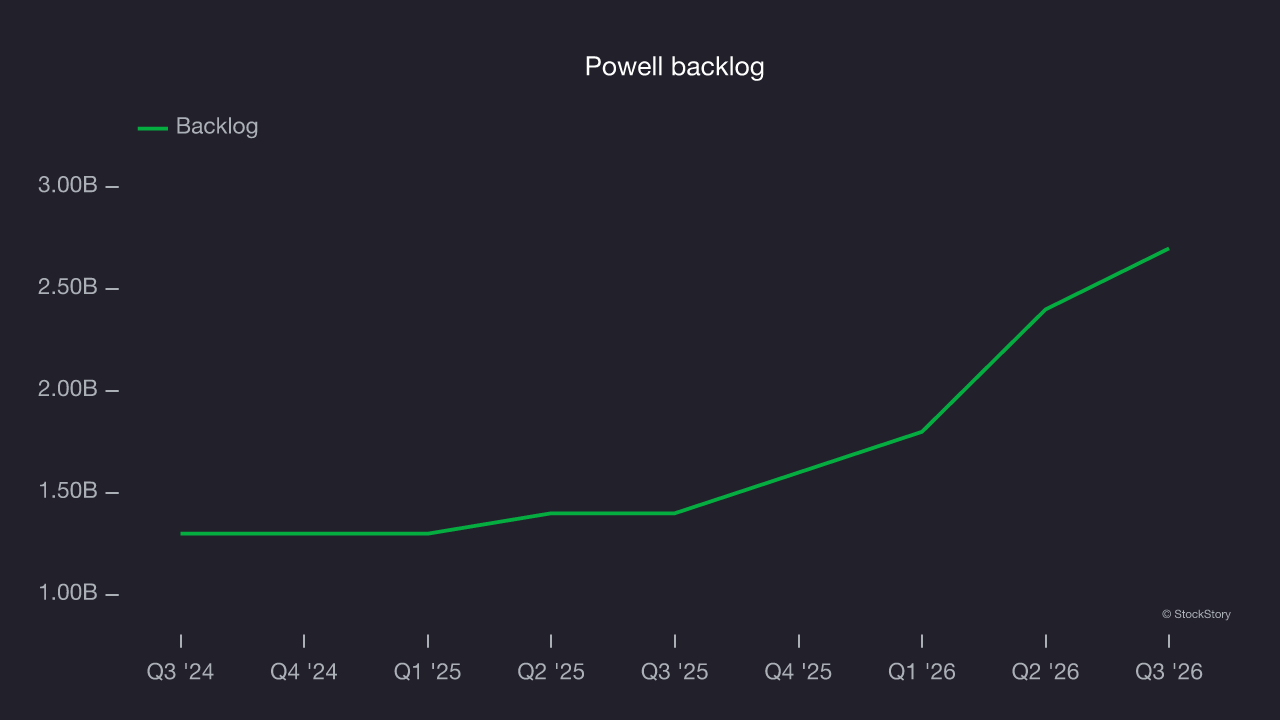
This quarter, Powell reported strong year-on-year revenue growth of 33.1%, and its $396.7 million of revenue exceeded Wall Street’s consensus estimates by 19.7%.
Looking ahead, sell-side analysts expect revenue to grow 15.4% over the next 12 months, according to S&P, an improvement versus the last two years. This strong projection implies its newer products and services will fuel better top-line performance.
Operating margin
Over the last five years, Powell’s operating margin rose by 19.7 percentage points. This improvement shows its costs declined relative to revenue. Its trailing 12-month operating margin was 21.1%.
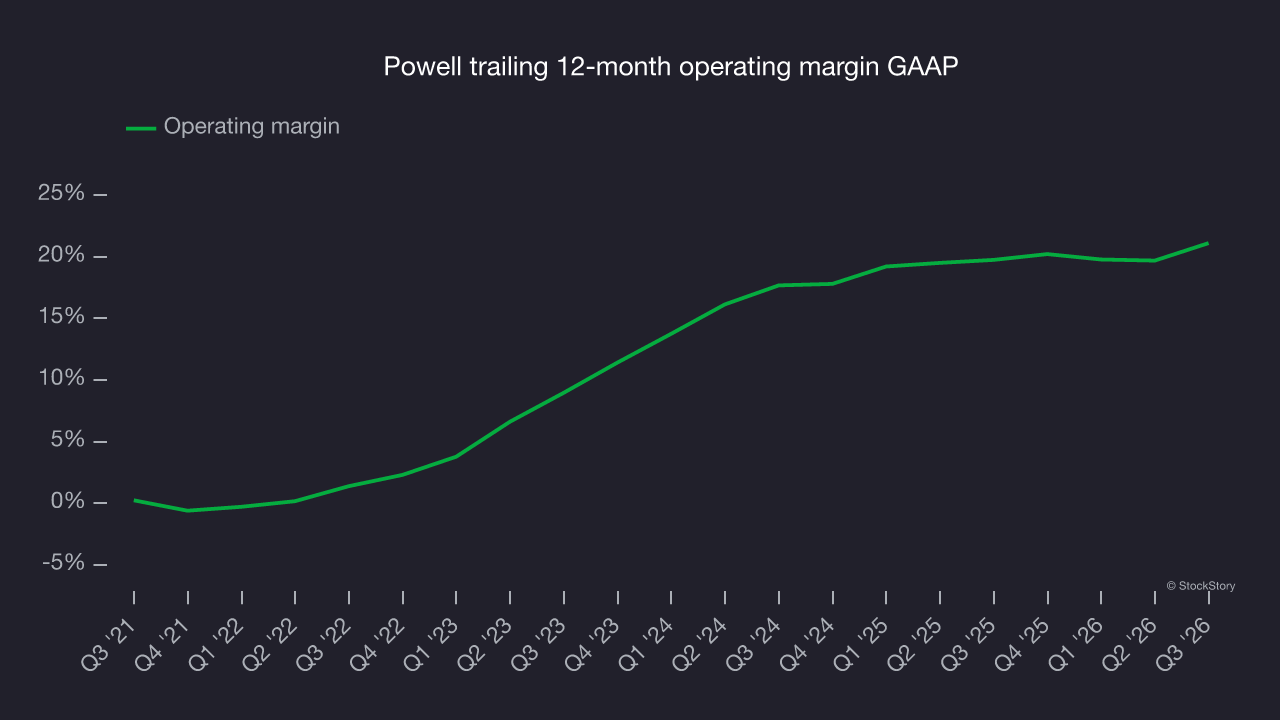
This quarter, Powell generated an operating profit margin of 25.3%, up 4.1 percentage points year on year. The increase was a positive sign, and the larger rise in operating margin than in gross margin indicates greater efficiency in expenses such as marketing, R&D and administrative overhead.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Powell’s EPS grew at a 213% compounded annual growth rate over the last five years, higher than its 21.7% annualized revenue growth. This shows the company became more profitable on a per-share basis as it expanded.
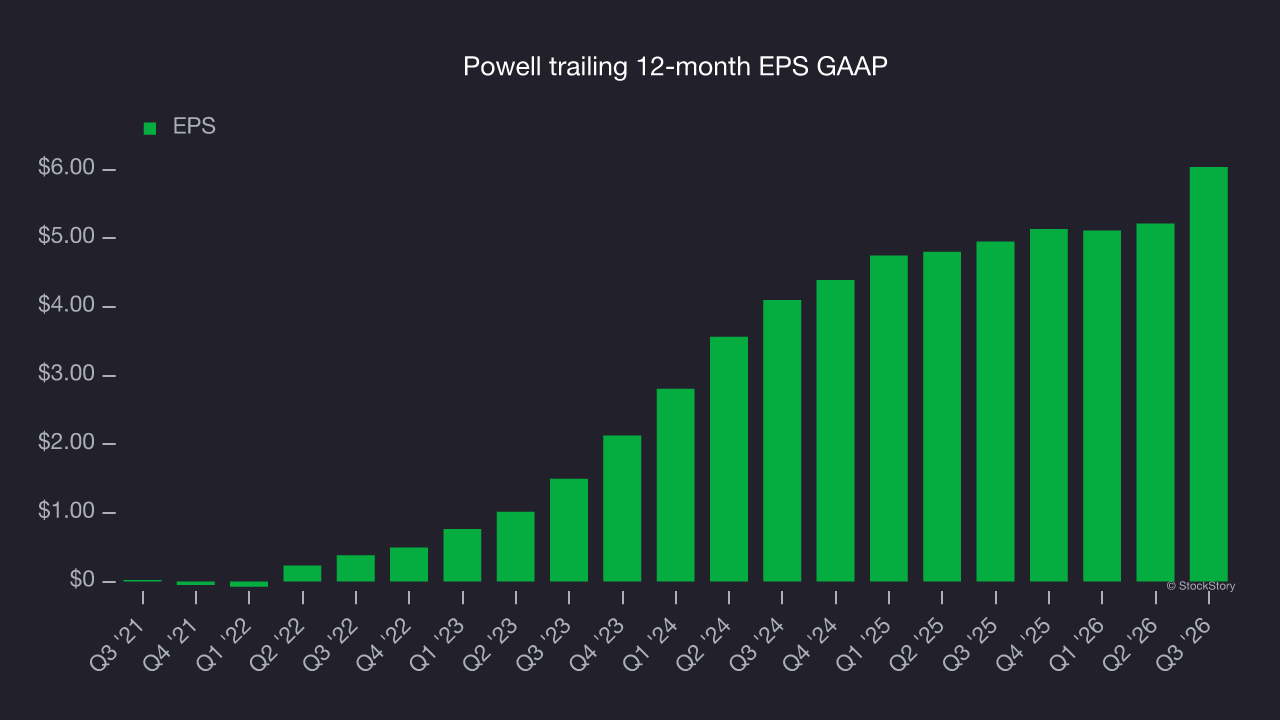
A closer look at Powell’s earnings helps explain its performance. As mentioned earlier, Powell’s operating margin expanded by 19.7 percentage points over the last five years. This was the most relevant factor aside from revenue growth behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, analyzing EPS over a more recent period can provide insight into an emerging theme or development for the business.
Powell’s two-year annual EPS growth of 21.4% was lower than its five-year trend. Growth remained solid, but an acceleration would be welcome.
In Q3, Powell reported EPS of $2.23, up from $1.41 in the same quarter last year. EPS easily cleared analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Powell’s full-year EPS to grow 11.2% from $6.03 to $6.71, according to S&P.
Key takeaways from Powell’s Q3 results
A wide revenue beat was a key positive for Powell this quarter, with EPS also topping analysts’ consensus estimates. Those results gave the quarter some clear strengths. Shares remained flat at $151.80 immediately after the release.
Powell had a solid quarter, but one earnings result doesn’t necessarily make the stock a buy. What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on Powell, read our full research report here (it’s free).