


EN
Dear Starbucks Stock Fans, Mark Your Calendars for November 17
Starbucks (SBUX) is heading into one of its most closely watched holiday traffic events of the year, with Red Cup Day returning on Tuesday, Nov. 17. The annual promotion gives customers a free limited-edition reusable red cup with the purchase of a qualifying handcrafted holiday or fall beverage at participating U.S. stores, while supplies last.
The event could give Starbucks a meaningful boost in store traffic as customers turn out for the collectible cup and seasonal drinks. This year’s promotion covers any size of qualifying hot, iced or blended beverage, including popular favorites such as Peppermint Mocha, Pumpkin Spice Latte and Sugar Cookie Latte, along with newer offerings such as the Tiramisu Velvet Latte and Tiramisu Velvet Cold Brew. Starbucks has also said it will have more baristas in cafés to handle the expected demand.
For investors, the timing is important because Starbucks launched its holiday menu on Nov. 5, featuring new seasonal beverages, returning favorites, and holiday food and merchandise, setting the stage for a broader seasonal sales push. With Red Cup Day potentially driving a surge in customer visits and beverage purchases, investors will be watching closely for signs that Starbucks can translate its holiday momentum into stronger traffic and sales as the crucial holiday quarter progresses.
About Starbucks Stock
Starbucks Corporation is a globally recognized leader in the retail coffee and specialty beverages industry, operating an extensive network of company-owned and licensed cafés and retail locations. Headquartered in Seattle, Washington, the company leverages its premium brand positioning, global footprint, and diversified product offerings to drive consumer engagement and scale. Starbucks carries a market cap of $121.3 billion, reflecting its status and global significance.
Starbucks stock has delivered a strong performance in 2026, gaining about 29.1% year to date (YTD) and 28.2% over the past year. The shares are also trading just 2.5% below their 52-week high of $111.50, which was reached on Nov. 5, highlighting the strength of the recent rally and renewed investor confidence in the coffee giant.
The stock’s momentum reflects growing optimism around Starbucks’ turnaround strategy under CEO Brian Niccol. The company’s fiscal fourth-quarter results provided further support for the bullish sentiment, with global comparable-store sales increasing 7.2% and U.S. comparable sales rising 7.7%. Starbucks also reported its fifth consecutive quarter of comparable-sales growth and third consecutive quarter of margin expansion, suggesting that the “Back to Starbucks” strategy is beginning to translate into more consistent customer traffic and improved profitability.
Meanwhile, the upcoming Nov. 17 Red Cup Day could provide another near-term catalyst. The annual promotion typically drives customers into Starbucks stores for limited-edition reusable cups and seasonal beverages. With the company already seeing improving traffic and comparable sales, a strong response to this year’s holiday event could reinforce the view that Starbucks is entering the critical holiday season with healthier consumer momentum.
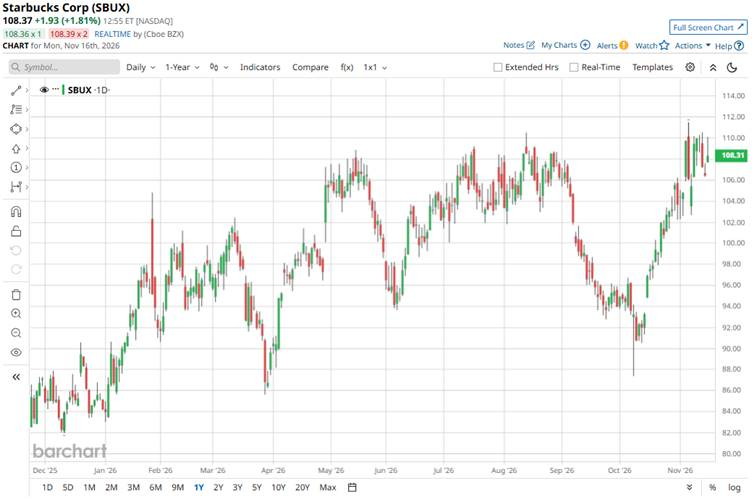
The stock is still trading at a premium to its industry peers at 33.33 times forward earnings.
SBUX Enters the Holiday Season With Strong Traffic and Earnings Momentum
Starbucks reported its latest quarterly results on Oct. 29. The results provided further evidence that CEO Brian Niccol’s “Back to Starbucks” turnaround is gaining traction, with the company delivering another quarter of strong comparable-store sales growth alongside significant margin and earnings improvement.
In the fiscal fourth quarter ended Sept. 27, 2026, global comparable coffeehouse sales increased 7.2% year-over-year (YOY), driven by a 1.8% increase in comparable transactions and a 5.2% increase in average ticket. North America comparable sales rose 7.9%, while U.S. comparable sales increased 7.7%, supported by a 2.4% increase in U.S. transactions.
However, consolidated fourth-quarter net revenue declined 4% YOY to $9.1 billion, but the decline was largely related to Starbucks’ transition of its China retail operations to a licensed joint-venture model rather than a deterioration in its core business.
Profitability improved substantially with fourth-quarter non-GAAP operating margin increased 460 basis points to 14%, while adjusted EPS increased 54% to $0.80, exceeding expectations.
Meanwhile, the full-year fiscal 2026 results provide an even clearer picture of the turnaround. Global comparable coffeehouse sales increased 6.2% YOY, consisting of a 3.2% increase in comparable transactions and a 3.0% increase in average ticket. U.S. comparable sales rose 6.5%, with transactions increasing 3.4%, while North America comparable sales increased 6.6%, driven by a 3.6% increase in transactions. International comparable sales increased 3.7%, with both transactions and average ticket contributing to growth.
Full-year consolidated revenue increased 2% to $37.9 billion. Moreover, full-year adjusted EPS increased 28% to $2.72. Net earnings attributable to Starbucks increased to approximately $2.5 billion from $1.9 billion a year earlier.
Store expansion remained another positive. Starbucks opened 617 net new coffeehouses during fiscal 2026, ending the year with 41,607 stores globally. The company opened 303 net new stores in the fourth quarter alone.
For fiscal 2027, management expects the turnaround to continue translating into higher profitability. Starbucks is targeting North America comparable-store sales growth of approximately 4%, non-GAAP operating margin of 13.5% to 14%, and non-GAAP EPS of $3.15 to $3.25, compared with $2.72 in fiscal 2026. The company also expects to add approximately 1,200 net new coffeehouses globally. Reported consolidated revenue is expected to decline approximately 1%, largely reflecting the China business transition and other structural factors, rather than a deterioration in underlying store performance.
Analysts expect the company’s EPS to climb 18.4% YOY to $3.22 in fiscal 2027 and rise another 16.5% to $3.75 in fiscal 2028.
What Do Analysts Expect for Starbucks Stock?
Recently, Stifel resumed coverage of Starbucks with a “Buy” rating and a $115 price target, signaling confidence that the company’s turnaround can support another year of strong earnings growth.
Plus, UBS maintained its “Neutral” rating on Starbucks while raising its price target to $110 from $105. Analyst Dennis Geiger’s move followed Starbucks’ fiscal fourth-quarter results and reflected stronger near-term sales momentum and the company’s improving outlook, while the analyst remains overall cautious.
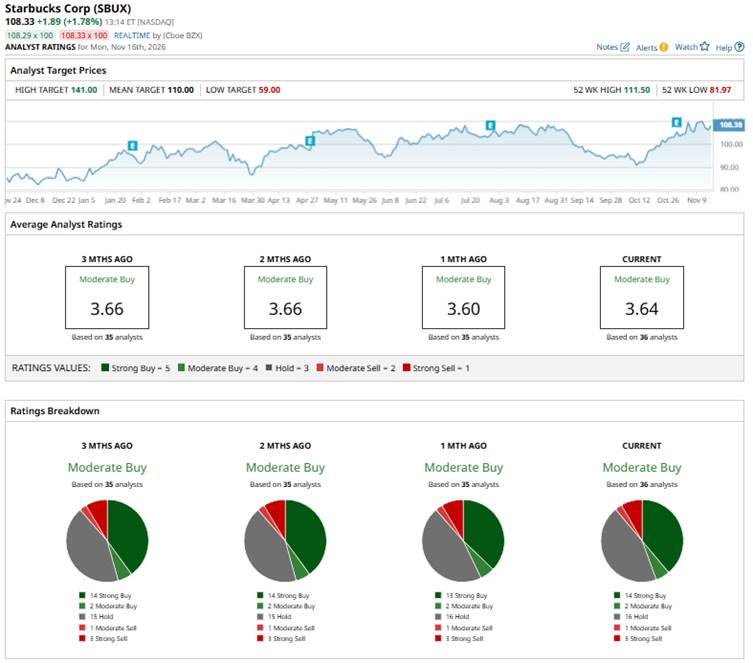
SBUX has a consensus rating of a “Moderate Buy” overall. Of the 36 analysts covering the stock, 14 advise a “Strong Buy,” two give a “Moderate Buy,” 16 suggest a “Hold,” one analyst gives it a “Moderate Sell” rating, and three rate it as a “Strong Sell.”
While SBUX’s average analyst price target of $110 indicates a 3.3% upside ahead, the Street-high target of $141 signals that it can still rise as much as 32.5% from current levels.
On the date of publication, Subhasree Kar did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.