


EN
AECOM issues FY 2027 Adjusted EBITDA guidance above consensus, stock soars 6.1%
Infrastructure consulting service company AECOM (NYSE:ACM) fell short of the market’s revenue expectations in calendar Q3 2026 [fiscal Q4 2026], with revenue falling 7.1% year on year to $3.88 billion. Its non-GAAP profit of $1.63 per share was 2.4% above analysts’ consensus estimates.
For more on AECOM, read the full research report for free.
AECOM Q3 CY2026 highlights:
- Revenue $3.88 billion vs S&P analysts’ consensus estimates of $4.01 billion (7.1% year-on-year decline, 3.3% miss)
- Adjusted EPS $1.63 vs S&P analysts’ consensus estimates of $1.59 (2.4% beat)
- Adjusted EBITDA $358.1 million vs analysts’ consensus estimates of $352.3 million (9.2% margin, 1.7% beat)
- Adjusted EPS guidance $6.25 at the midpoint for fiscal 2027, in line with analysts’ consensus estimates
- EBITDA guidance $1.37 billion at the midpoint for fiscal 2027, above analysts’ consensus estimates of $1.33 billion
- Operating margin 5.8%, in line with the same quarter last year
- Free cash flow margin 7.1%, up from 3.2% in the same quarter last year
- Backlog $28.02 billion at quarter end, up 12.8% year on year
- Market capitalization $9.06 billion
"Our underlying cash flow was very strong, resulting in full year free cash flow that was ahead of our prior guidance," said Gaurav Kapoor, AECOM's chief financial and operations officer. "Our business remains highly cash generative, benefiting from a high-quality client base and strong culture across our teams. Combined with our continued strong balance sheet, we operate with confidence, as reflected in the 10% increase to our quarterly dividend we announced today."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. AECOM’s revenue grew at a sluggish 2.5% compounded annual growth rate over the last five years, falling short of our benchmarks.
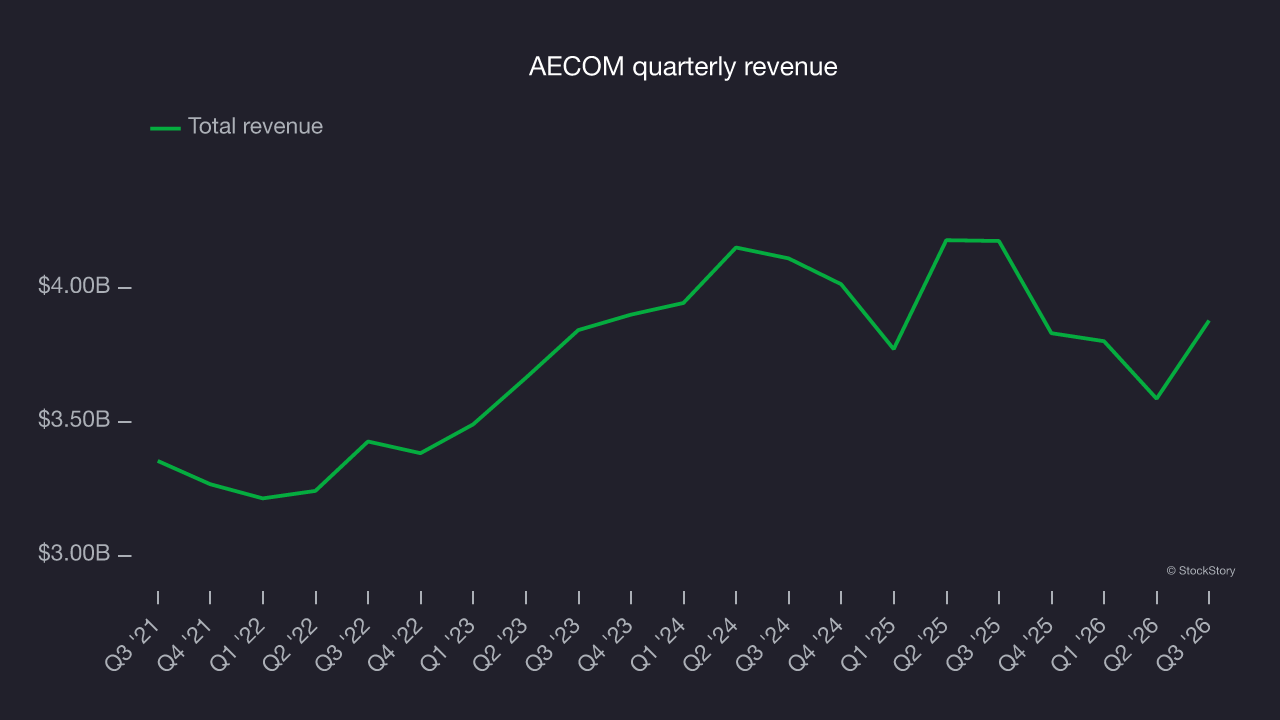
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. AECOM’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 3.2% annually. AECOM’s decline is a warning sign, especially when its industry was growing rapidly, with many engineering and design services businesses posting double-digit growth.
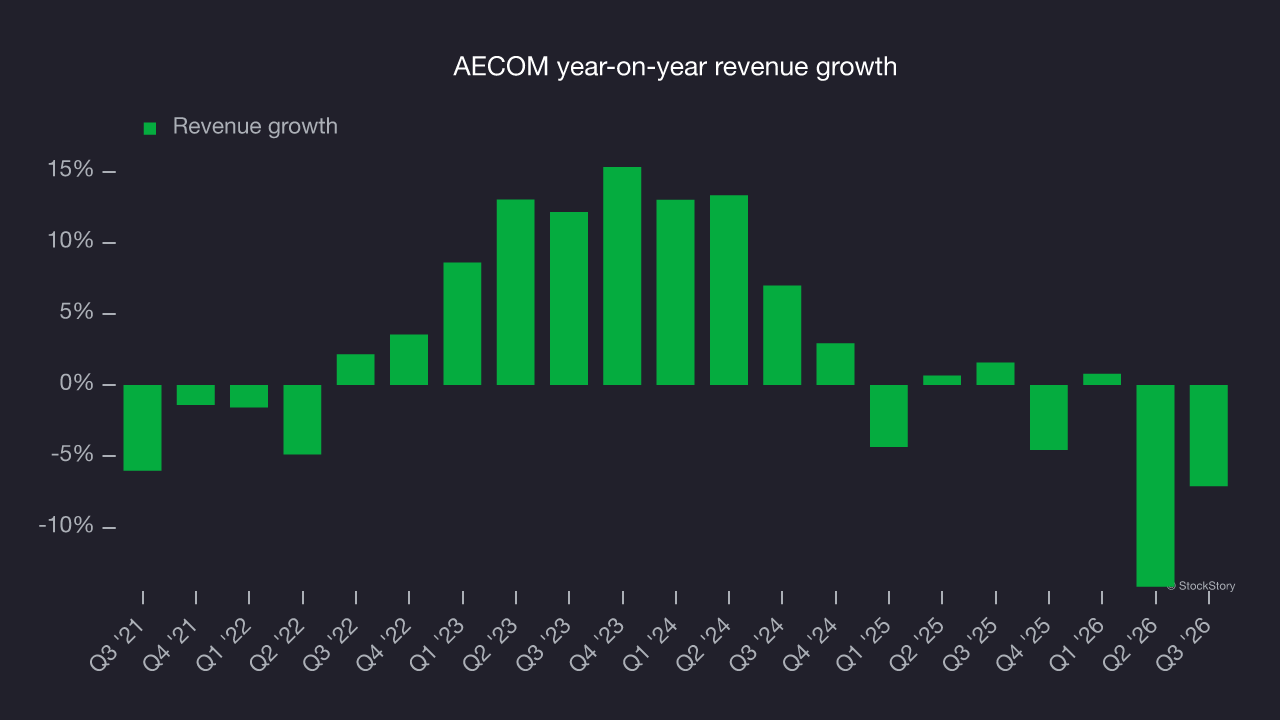
We can better understand the company’s revenue dynamics by analyzing its backlog, or the value of its outstanding orders that have not yet been executed or delivered. AECOM’s backlog reached $28.02 billion in the latest quarter and averaged 1.8% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating that the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for AECOM’s products and services but raises concerns about capacity constraints.
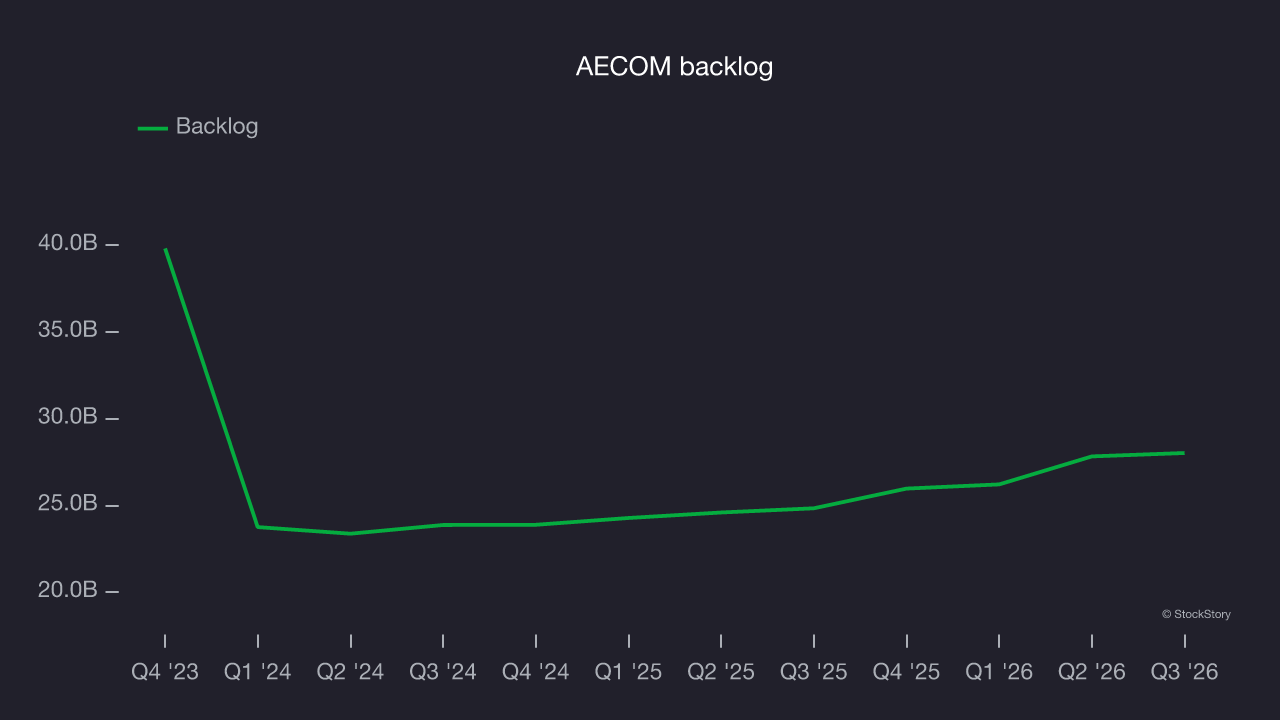
This quarter, AECOM missed Wall Street’s consensus estimates and reported an uninspiring 7.1% year-on-year revenue decline, generating $3.88 billion of revenue.
Looking ahead, sell-side analysts expect revenue to grow 7.8% over the next 12 months, according to S&P, an improvement versus the last two years. This projection is particularly healthy for a company of its scale and indicates its newer products and services will spur better top-line performance.
Operating margin
AECOM’s operating margin was broadly unchanged over the last five years. Its costs have broadly tracked its revenue, leaving its long-term profitability largely unchanged. Its trailing 12-month operating margin was 4.1%.
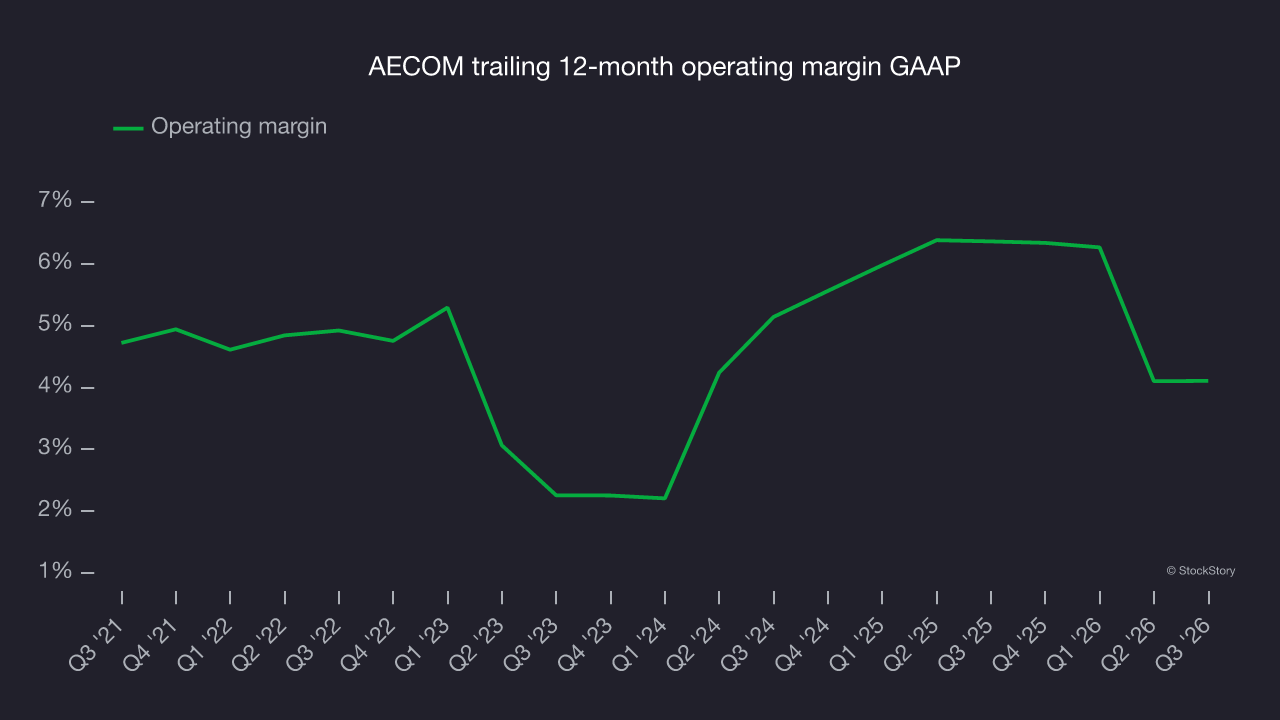
In Q3, AECOM generated an operating profit margin of 5.8%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
AECOM’s EPS grew at a 7.2% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement lagged that of peers.
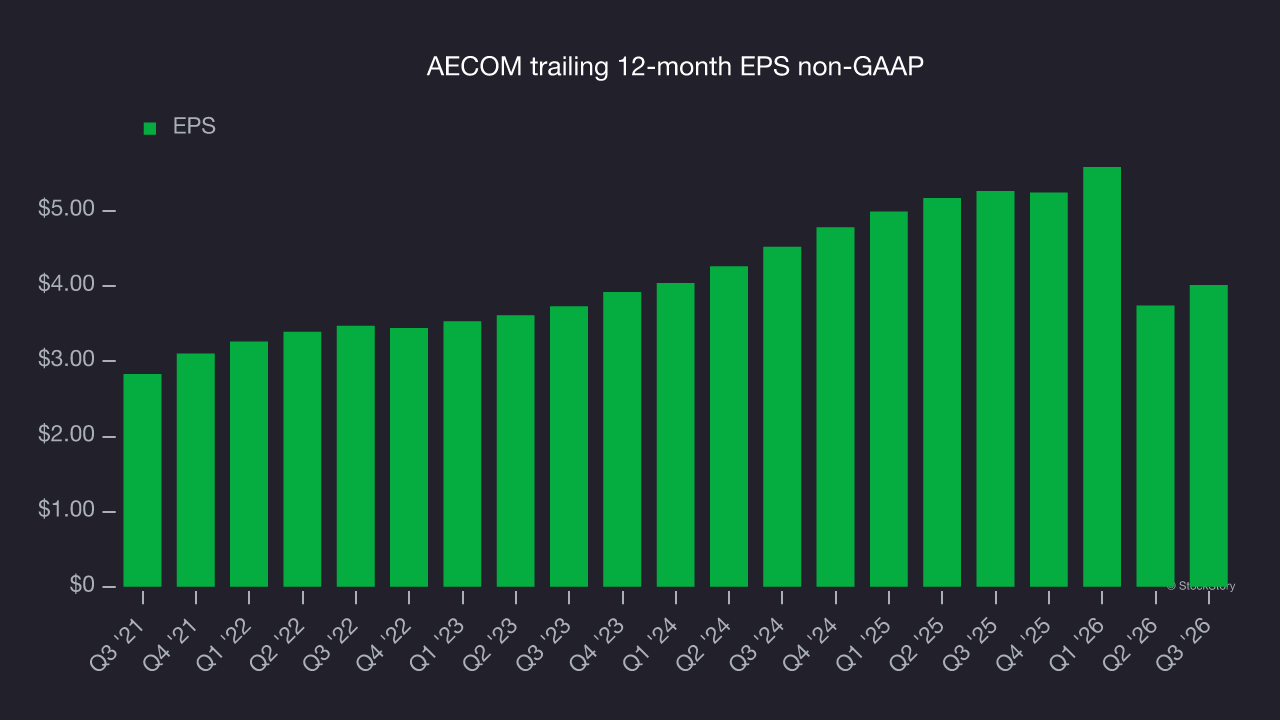
A closer look at AECOM’s earnings helps explain its performance. A five-year view shows that AECOM has repurchased its stock, shrinking its share count by 11.9%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but because of financial engineering, as buybacks boost per share earnings.
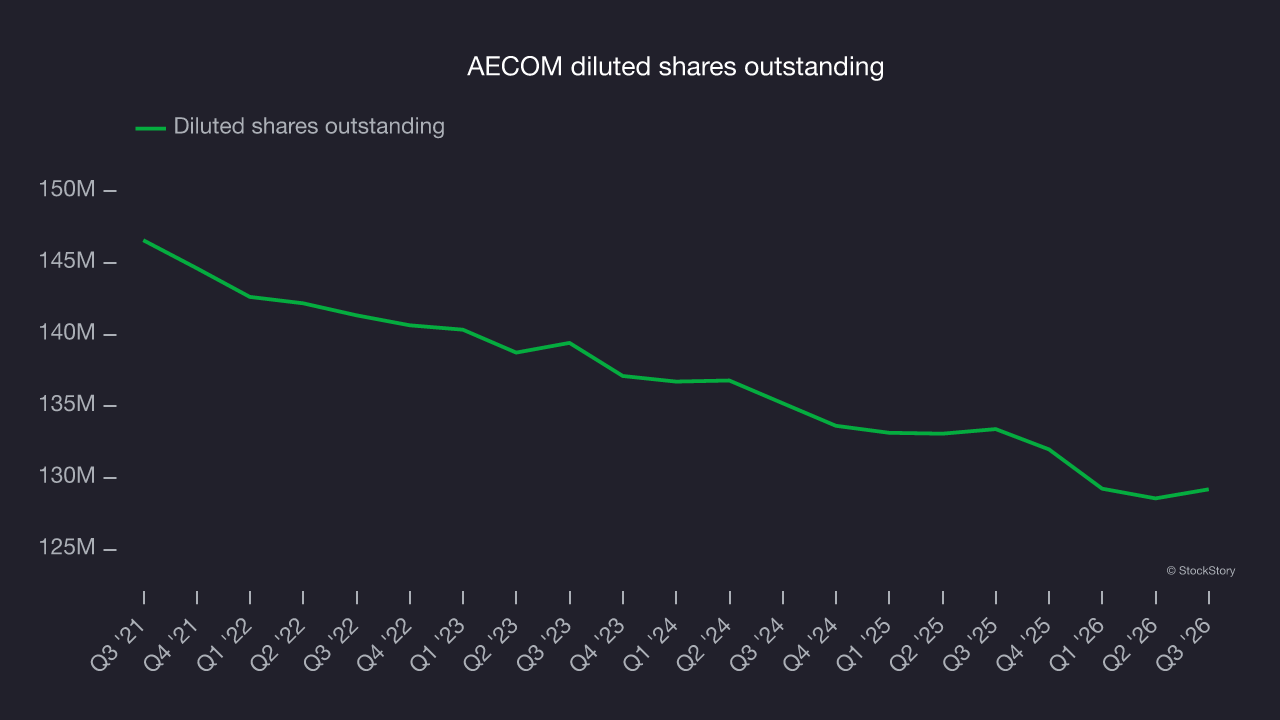
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
AECOM’s annual EPS declines of 5.8% over the last two years show it has continued to underperform. These results were poor by any measure.
In Q3, AECOM reported adjusted EPS of $1.63, up from $1.36 in the same quarter last year. This result beat analysts’ consensus estimates by 2.4%. Over the next 12 months, Wall Street expects AECOM’s full-year EPS to grow 55.4% from $4.01 to $6.23, according to S&P.
Key takeaways from AECOM’s Q3 results
AECOM delivered a solid quarter: EBITDA beat Wall Street’s consensus estimates and full-year EBITDA guidance also topped analysts’ consensus estimates, but revenue missed expectations. Shares surged 6.1% to $76.88 immediately after the results.
AECOM’s latest quarter matters, but longer-term fundamentals and valuation are far more important when deciding whether to buy the stock. For more on AECOM, read our full research report here (it’s free).