


EN
What Early Wheaton Precious Metals Buyers Saw
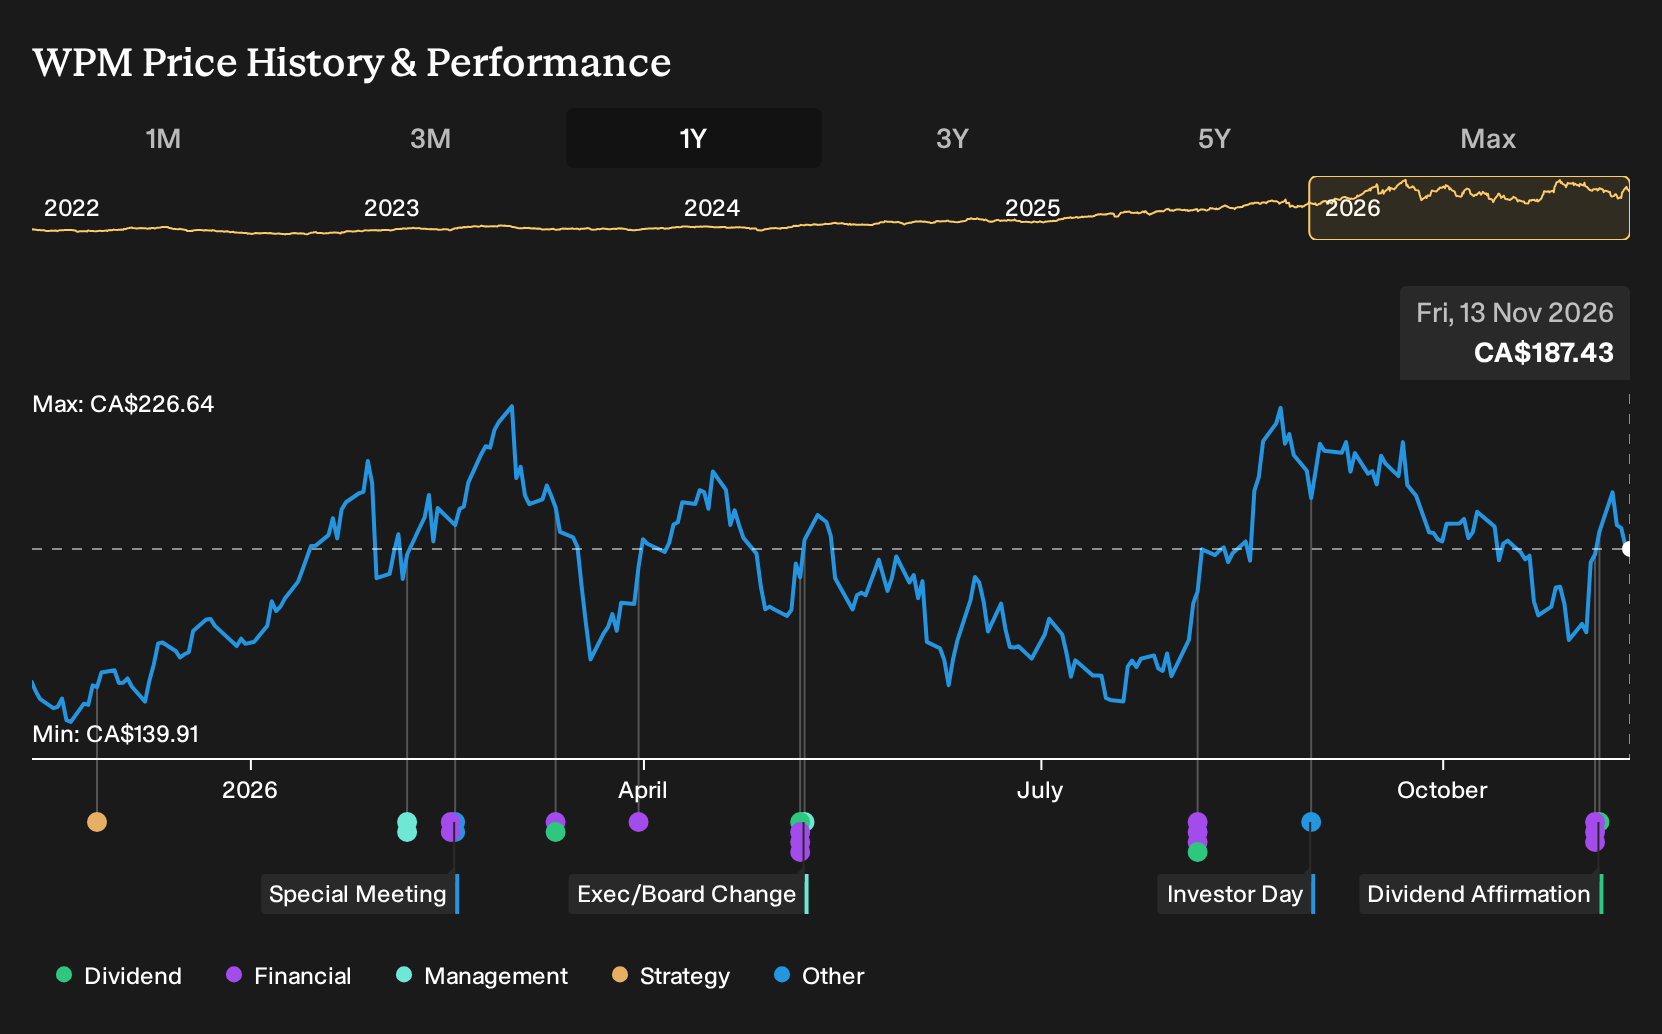
If you had decided to buy Wheaton Precious Metals on 13 November 2025 and simply hold through to 13 November 2026, the outcome was clear. Holding Wheaton Precious Metals over the past year would have returned 31.2%, including dividends. What was less clear at the start was how to weigh surging interest in decarbonization metals against worries about crypto siphoning off capital. Were early buyers really paying for growth, or for perceived safety in a volatile world?
Wheaton Precious Metals has already moved. Pinpoint other ways to investigate the theme among 10 top silver producer stocks.
The Argument You Would Have Been Weighing On Wheaton Precious Metals
The shares cost CA$148 at the start of the period. Anyone looking at Wheaton Precious Metals then had to decide whether that tag reflected a metal streamer on the cusp of a structural shift or one facing shrinking demand for its core products.
On the bullish side, one view saw a Fair Value of CA$192, a price implied by expectations of strong decarbonization metal demand and safe haven interest. That Narrative leaned on Wheaton Precious Metals using its CA$1.1b cash and undrawn CA$2b credit to secure more large, high quality streams.
A bearish camp argued for a Fair Value of CA$126, a level tied to more cautious assumptions. This view focused on risks that crypto and other digital assets would pull capital away from gold and silver, leaving Wheaton Precious Metals exposed if investor demand for physical metals weakened over time.
What The Results Changed For Wheaton Precious Metals
The biggest proof point for Wheaton Precious Metals was operational. Record Q3 2026 revenue of US$771.7m and higher net income than a year earlier backed the bullish view that volumes and pricing could support growth. The catch was profitability quality. Net margin moved from 77.1% in Q3 2025 to 53.2% in Q3 2026, which kept the evidence mixed and cut both ways.
The practical takeaway is simple. When a story leans on margin strength, do not just watch revenue. Track net margin alongside volume and pricing each quarter to see whether the profitability mix is holding up at other metal streamers you study.
What You Would Be Paying For In Wheaton Precious Metals Today
With Wheaton Precious Metals now at CA$187, the cautious Narrative from Simply_Free_Rider, an investor in the Simply Wall St Community, places its Fair Value below the current market level.
The focus is on whether the 2030 volume plan and price deck hold together. A buyer today would need to judge if the large project slate delivers roughly on time while metal prices and the gold or silver mix track Wheaton’s own assumptions.
"One thing to keep in mind. Wheaton calculates those GEOs at $4,800 gold and $80 silver, set in its guidance of 16 February, right after the January peaks, and still used in its October presentation."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 44% below our estimate - uses high sales per square foot and flexible inventory buys to chase mall traffic.
- Company 2 - 46% below our estimate - applies regional mine teams and AI tools to tighten planning and stabilise output.
- Company 3 - 38% below our estimate - faces rising regulatory costs as lower ore grades reshape the economics of key projects.
Those are three of them. See all 6 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com