


EN
Will Share Donation Change Berkshire Hathaway Stock Narrative
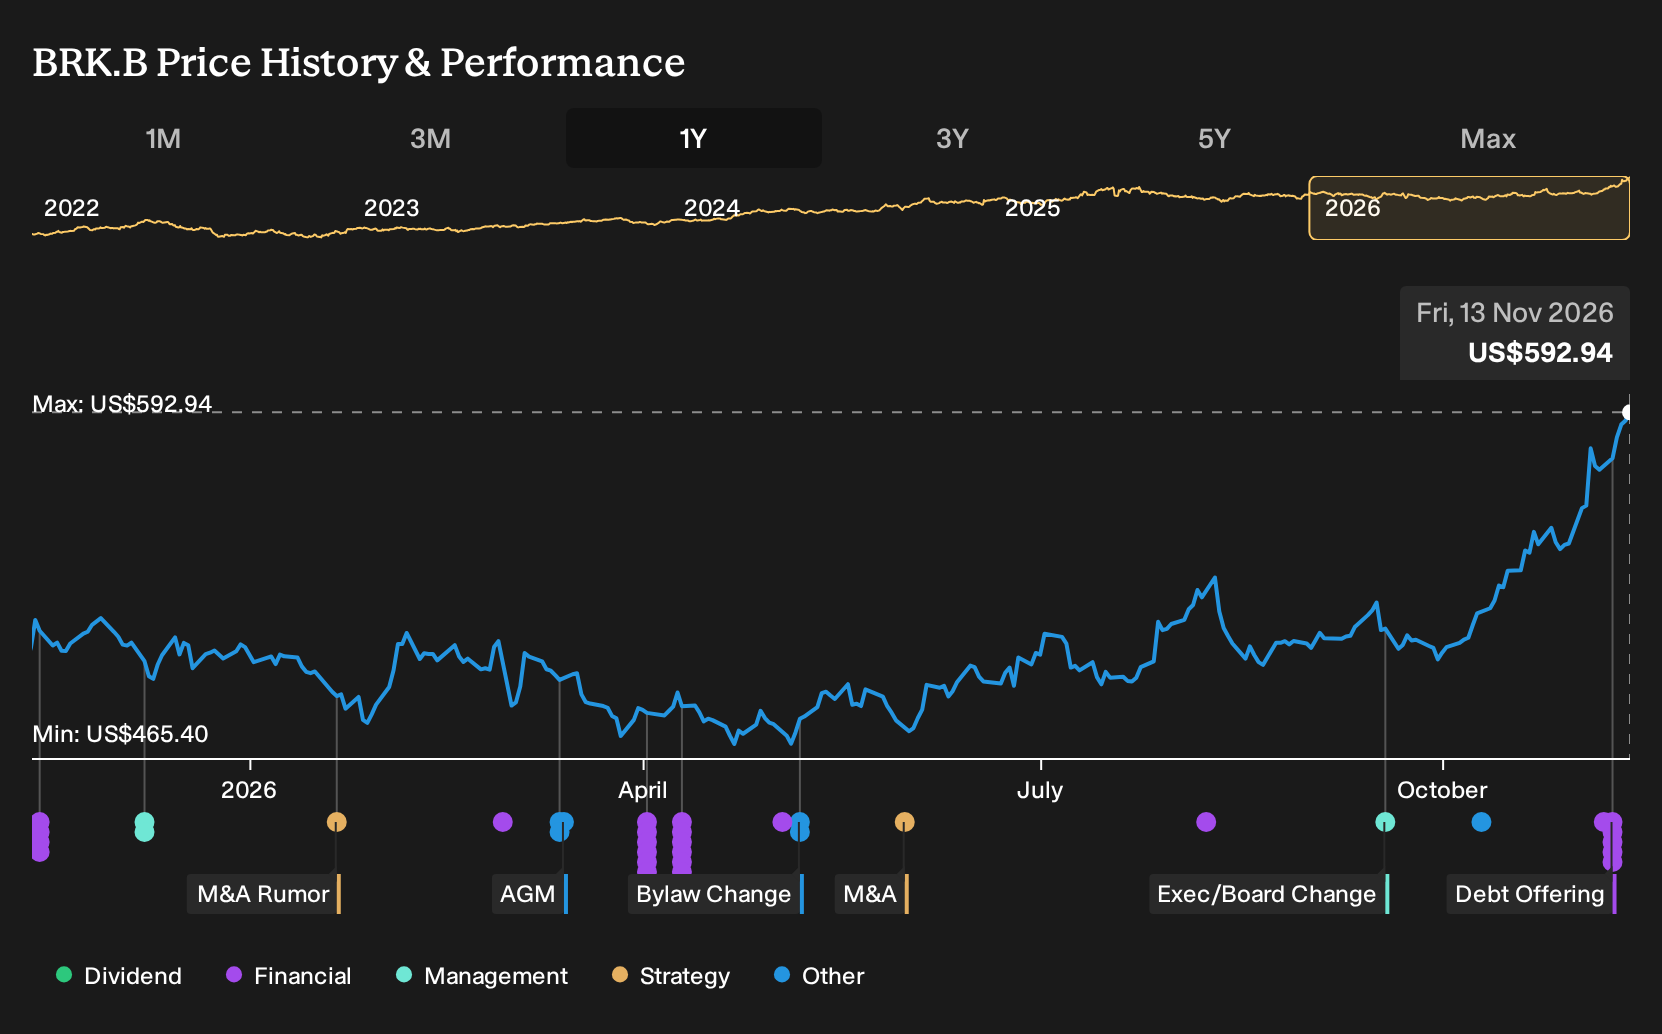
- Warren Buffett has already converted 6,150 Berkshire Hathaway Class A shares into 9,225,000 Class B shares and donated about $5.5b worth to four family foundations, confirming that all his remaining Berkshire holdings are intended for philanthropy.
- The donation concentrates Berkshire Hathaway ownership further in long term holders while Buffett reiterates his confidence in the business, even as the group continues issuing yen bonds to align funding with its Japanese equity exposure.
- We will look at how Berkshire Hathaway’s long term investment narrative is affected by Buffett’s large share donation and ownership shift.
Berkshire Hathaway Investment Narrative Recap
To own Berkshire Hathaway, you need to believe in a diversified, cash generating mix of insurance, utilities, transport and industrial businesses, with disciplined capital deployment under Greg Abel. The analyst consensus Narrative on Simply Wall St expects modest revenue growth and earnings drifting lower, so the thesis leans more on resilience and capital allocation than rapid expansion.
The fresh run of yen bond issues, now including ¥182.3b in fixed rate notes, reinforces that Berkshire funds long term assets with long dated debt. This funding move does not materially change the near term story. The key short term swing factor remains insurance and investment earnings, while leadership transition and utility pushback sit as primary risks.
The most relevant recent update is Berkshire’s completion of multiple yen denominated bond offerings, such as the ¥92b 2.624% notes due 2029 and ¥57.3b 3.007% notes due 2031. These are senior, unsecured, unsubordinated and callable, so they add funding flexibility without tying capital to a single business line.
For you as a shareholder, these bonds matter because they align with Berkshire’s large Japanese equity exposure and support its ability to hold those positions over long horizons. Execution risk sits in how effectively management matches currency and interest obligations to operating cash flows, which feeds into the same catalysts analysts focus on, steady earnings and disciplined balance sheet use.
Berkshire Hathaway Scenario Checks On The Analyst Numbers
Berkshire Hathaway's narrative projects US$455.3b revenue and US$52.3b earnings by 2029. That path assumes 4.8% yearly revenue growth and an earnings decline of about US$24.8b from current earnings of US$77.1b.
Uncover why Berkshire Hathaway's fair value indicates an 8% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about 816,000 and 1,184,000, so you are seeing a wide band of opinion on Berkshire Hathaway. That range aligns with a fresh run of yen bonds and a new co-lead underwriter group, which together keep the focus on long-dated funding discipline. Use these differing views as a prompt to explore several alternative perspectives before relying on any single fair value estimate.
Explore 3 other Berkshire Hathaway fair value estimates, including one that suggests as much as 33% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Berkshire Hathaway research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Berkshire Hathaway. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Berkshire Hathaway's overall financial health at a glance.
Looking For More Ideas Beyond Berkshire Hathaway?
Once you have a handle on Berkshire Hathaway, it can help to widen the lens and compare it with other businesses that share some of the same traits, such as strong balance sheets or consistent cash generation. The Simply Wall St Screener lets you filter for those kinds of characteristics directly so you can build a watchlist that fits your own risk tolerance and return goals.
- For investors who want financial strength at the center of their watchlist, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies built on sturdier foundations.
- If value is your priority and you are hunting for potential mispricings, use a 35 high quality undervalued stocks to see which businesses might be trading below what their fundamentals suggest.
- If you prefer stocks with staying power and less balance sheet stress, especially in choppy periods, then a 30 resilient stocks with low risk scores could help surface candidates with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com