


EN
Liontown (ASX:LTR) Shares Could Be Above Fair Value On A 63% Fall
Liontown has seen its share price fall sharply over the past few years, which puts fresh focus on whether the current valuation is adequately supported by the earnings the business can generate. With sentiment also shaped by shifting lithium market expectations, the question now is how much of that backdrop is already reflected in Liontown's earnings based pricing.
- The stock has declined 62.7% over the past 5 years, which puts long term holders in the position of asking whether today's valuation still lines up with the underlying earnings power.
- Citi's recent cut to lithium price forecasts and its lower target for Liontown highlight how market surplus concerns can influence expectations for future profitability and the earnings multiple investors may be willing to pay.
- There is a second opinion on Liontown worth weighing. See what analysts think Liontown's shares could be worth.
For investors, the debate is whether Liontown's current share price is appropriately grounded in the earnings the company is producing and expected to produce.
If you are weighing Liontown against other opportunities linked to lithium and broader materials exposure, it can help to line it up beside 33 best rare earth metal stocks.
Has Liontown Run Too Far on Earnings?
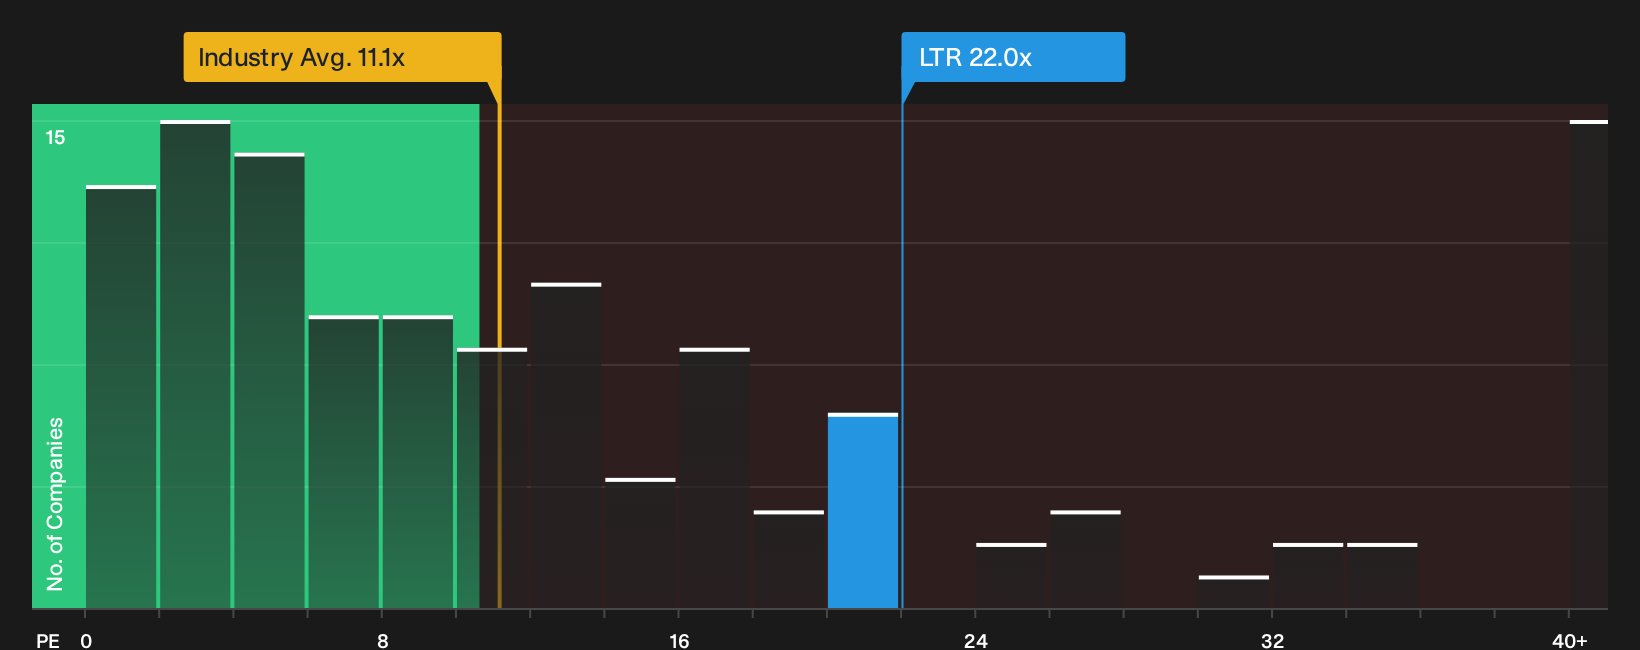
The P/E ratio fits Liontown because earnings are ultimately what need to support any lithium story, no matter how compelling the commodity backdrop looks. On this lens, Liontown trades on roughly 22.0x earnings, which is almost double the broader metals and mining sector average of about 11.1x and well below the roughly 57.6x level seen across its closer peers.
Citi’s recent cut to lithium price forecasts and its lower target for Liontown underline why paying a premium multiple can feel uncomfortable when sentiment leans toward surplus supply. The current P/E sits above the level suggested by a more tailored fair value multiple that takes Liontown’s growth profile, profitability and risk into account, so the shares screen as overvalued on this framework. That gap leaves you weighing how much production execution and lithium pricing strength you need to see to justify paying up on earnings today. Explore the numbers behind Liontown's P/E valuation.
The Liontown Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Liontown leaves off by explaining what level of future growth, margins and earnings profile would be required for the stock to be worth materially more or materially less than its current price on the Community page. Each scenario links a fair value to a specific storyline about Liontown's potential catalysts and risks so you can later compare which version of events is actually unfolding.
One of the top narratives on Liontown: 35% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies that the market is giving limited credit for Liontown’s plan to lift spodumene output by more than 50% from FY30..."
Discover why this Narrative puts Liontown at 35% undervalued.
The Liontown share price is only one piece of the decision
Price and earnings multiples tell part of the Liontown story, but analyst models looking a few years ahead offer a different lens on what the business could be earning relative to today. Explore where analysts expect Liontown to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com