


EN
Why It’s Time to Load Up On Dell Stock
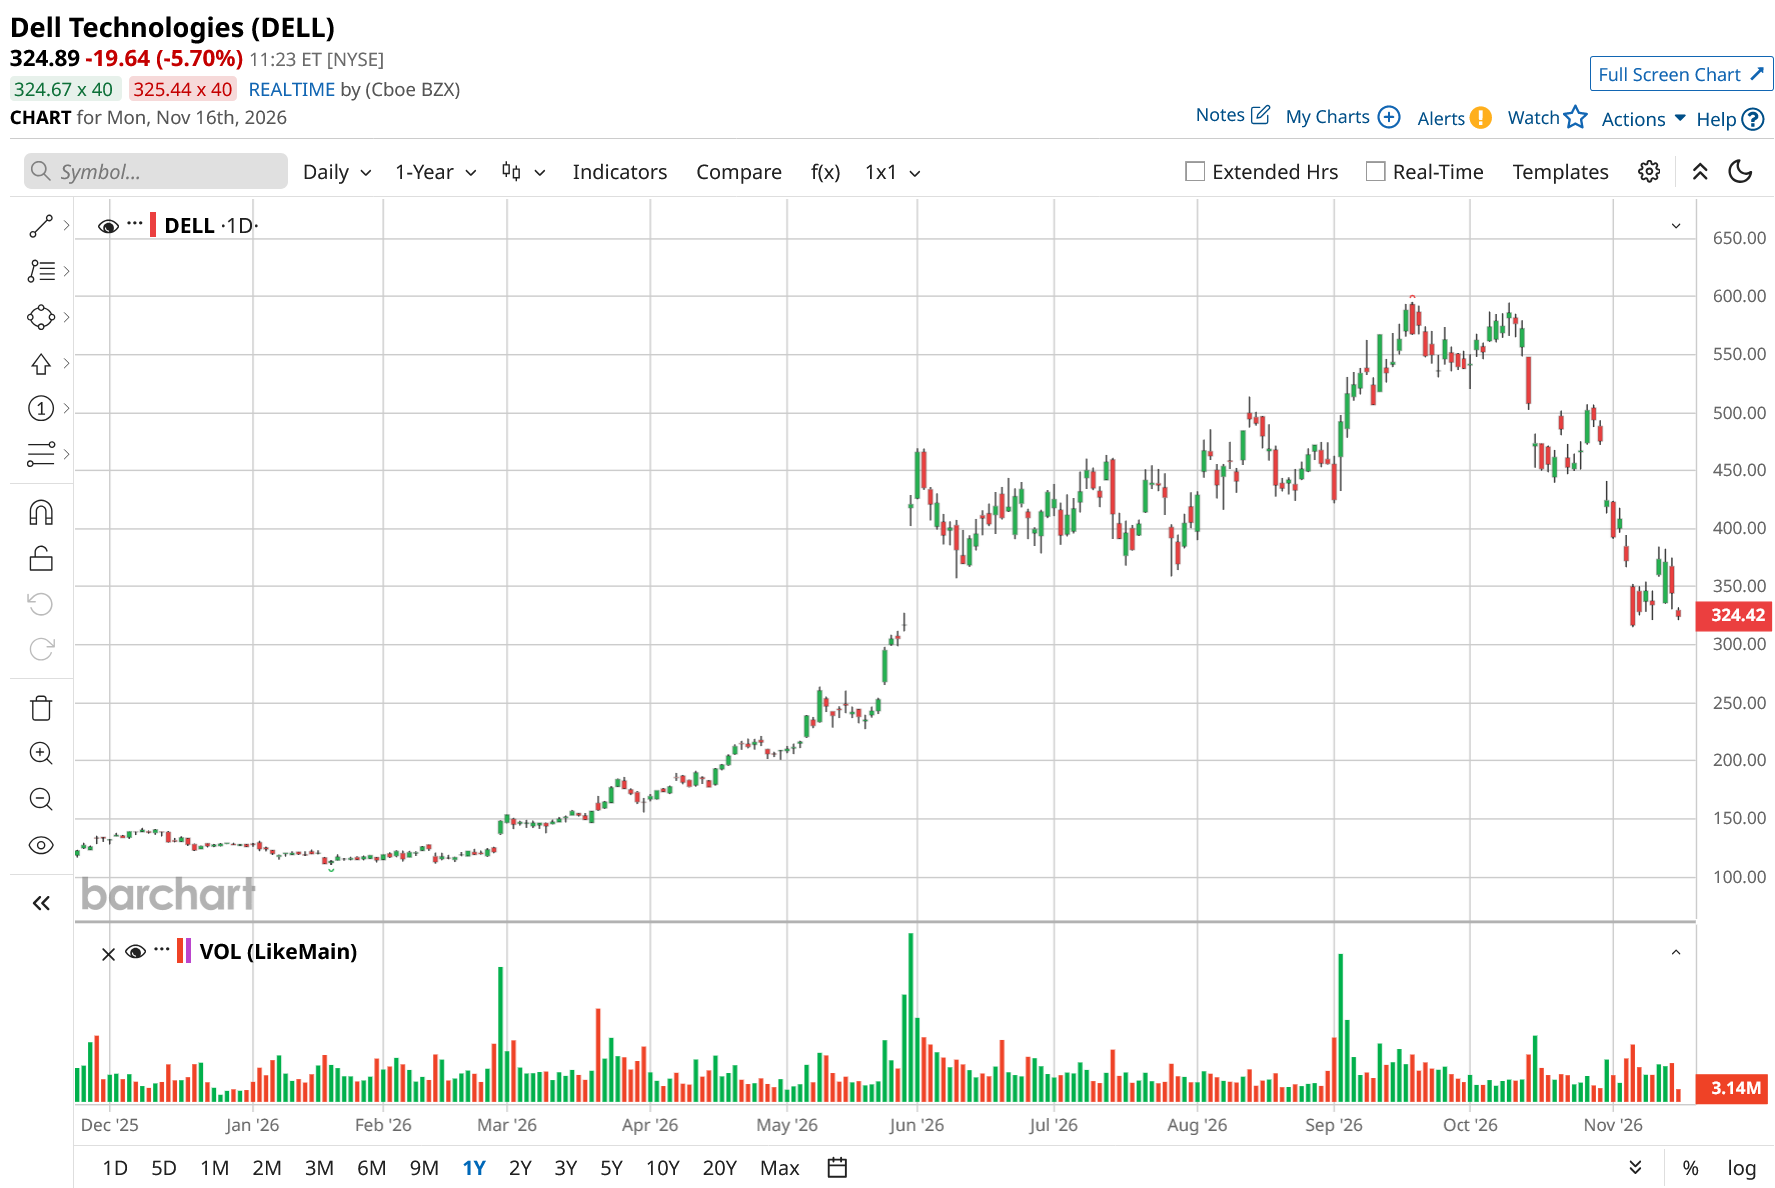
Dell (DELL) stock has witnessed a steep correction, declining about 30% over the past month. The weakness reflects broader selling pressure across AI-related stocks, profit-taking following a strong rally, and persistent concerns surrounding softness in the traditional PC market.
However, the recent decline offers an opportunity to load up on DELL stock. While the stock has pulled back, its prospects remain solid as the technology company will continue to benefit from sustained demand for AI-optimized infrastructure, along with continued demand for conventional servers, networking equipment, and storage solutions. Furthermore, an expanding customer base, a growing addressable market, and a substantial order backlog provide visibility into future growth.
Dell’s Growth Isn’t Slowing Down
Despite the sharp decline in its share price, Dell’s outlook remains strong, with its growth rate unlikely to slow anytime soon. In fact, Dell’s revenue growth is expected to accelerate in the coming quarters. Revenue jumped 58% year-over-year (YoY) to $47 billion in the second quarter, while management expects third-quarter revenue of approximately $49 billion at the midpoint, representing growth of nearly 80%, indicating significant acceleration in business activity.
The biggest contributor to this growth is Dell’s Infrastructure Solutions Group (ISG), which continues to benefit from rising demand for AI infrastructure. ISG revenue surged 89% to $31.8 billion in Q2, driven largely by strong demand for AI servers. The scale of this opportunity is reflected in the division’s record $60.9 billion in AI server orders, $16.4 billion in AI server revenue, and $95 billion in ending backlog. These numbers suggest that demand remains exceptionally strong and that Dell has a substantial pipeline of business to convert into future revenue.
Beyond AI servers, Dell’s traditional server, networking, and storage businesses are also performing well. Traditional server and networking revenue increased 122% to $10.5 billion, as demand continued to outstrip supply. Storage revenue, meanwhile, grew 26% to $4.9 billion, supported by strong demand across Dell’s IP storage portfolio. This is particularly encouraging because storage is also contributing to profitability, with a higher mix of Dell IP solutions helping improve margins. Demand for Dell IP storage has outperformed the broader market for six consecutive quarters.
The outlook for the third quarter is even stronger. Management expects ISG revenue to grow approximately 145%, supported by around $19 billion in AI server revenue. Demand for traditional servers and storage is also expected to remain healthy. Enterprises are continuing to upgrade their data centers to support existing workloads, while growing security and resiliency requirements are encouraging further infrastructure spending. At the same time, the adoption of AI and agentic workflows is creating additional demand for traditional servers, as these applications also require significant CPU computing capacity.
Another positive development is that demand is coming from a wider range of customers. Neocloud providers, sovereign infrastructure projects, and large enterprises are all increasing their investments, while Dell’s customer base has grown to more than 6,500.
Dell’s PC business is also holding up better than the broader market might suggest. Although the overall PC market remains weak, large enterprise customers are continuing to refresh their installed PC base. This has supported double-digit growth across all regions, highlighting the resilience of enterprise demand.
Strong revenue should also translate into meaningful earnings growth. Higher sales volumes, continued focus on operational efficiency, and an improving product mix are expected to support profitability. In particular, the growing contribution from higher-margin Dell IP storage solutions and better pricing across its solutions portfolio could provide further support to margins.
Analysts expect Dell’s earnings to more than double in both the third and fourth quarters. The growth outlook also remains encouraging beyond the current fiscal year, with the company expected to deliver mid-teens EPS growth in fiscal 2028, despite tougher YoY comparisons.
Overall, Dell’s growth story remains intact, and its business momentum appears considerably stronger, supporting its investment case.
Why DELL Stock’s 30% Pullback Is a Buying Opportunity
Dell is expected to benefit from strong AI server demand, a record order backlog, accelerating revenue growth, and improving prospects across its traditional infrastructure and storage businesses. Moreover, the pullback has eased valuation concerns, making the stock more attractive from a risk-reward perspective.
While DELL stock could remain volatile in the short term, its strong growth visibility and expanding AI infrastructure opportunity make the recent weakness an attractive entry point for long-term investors.
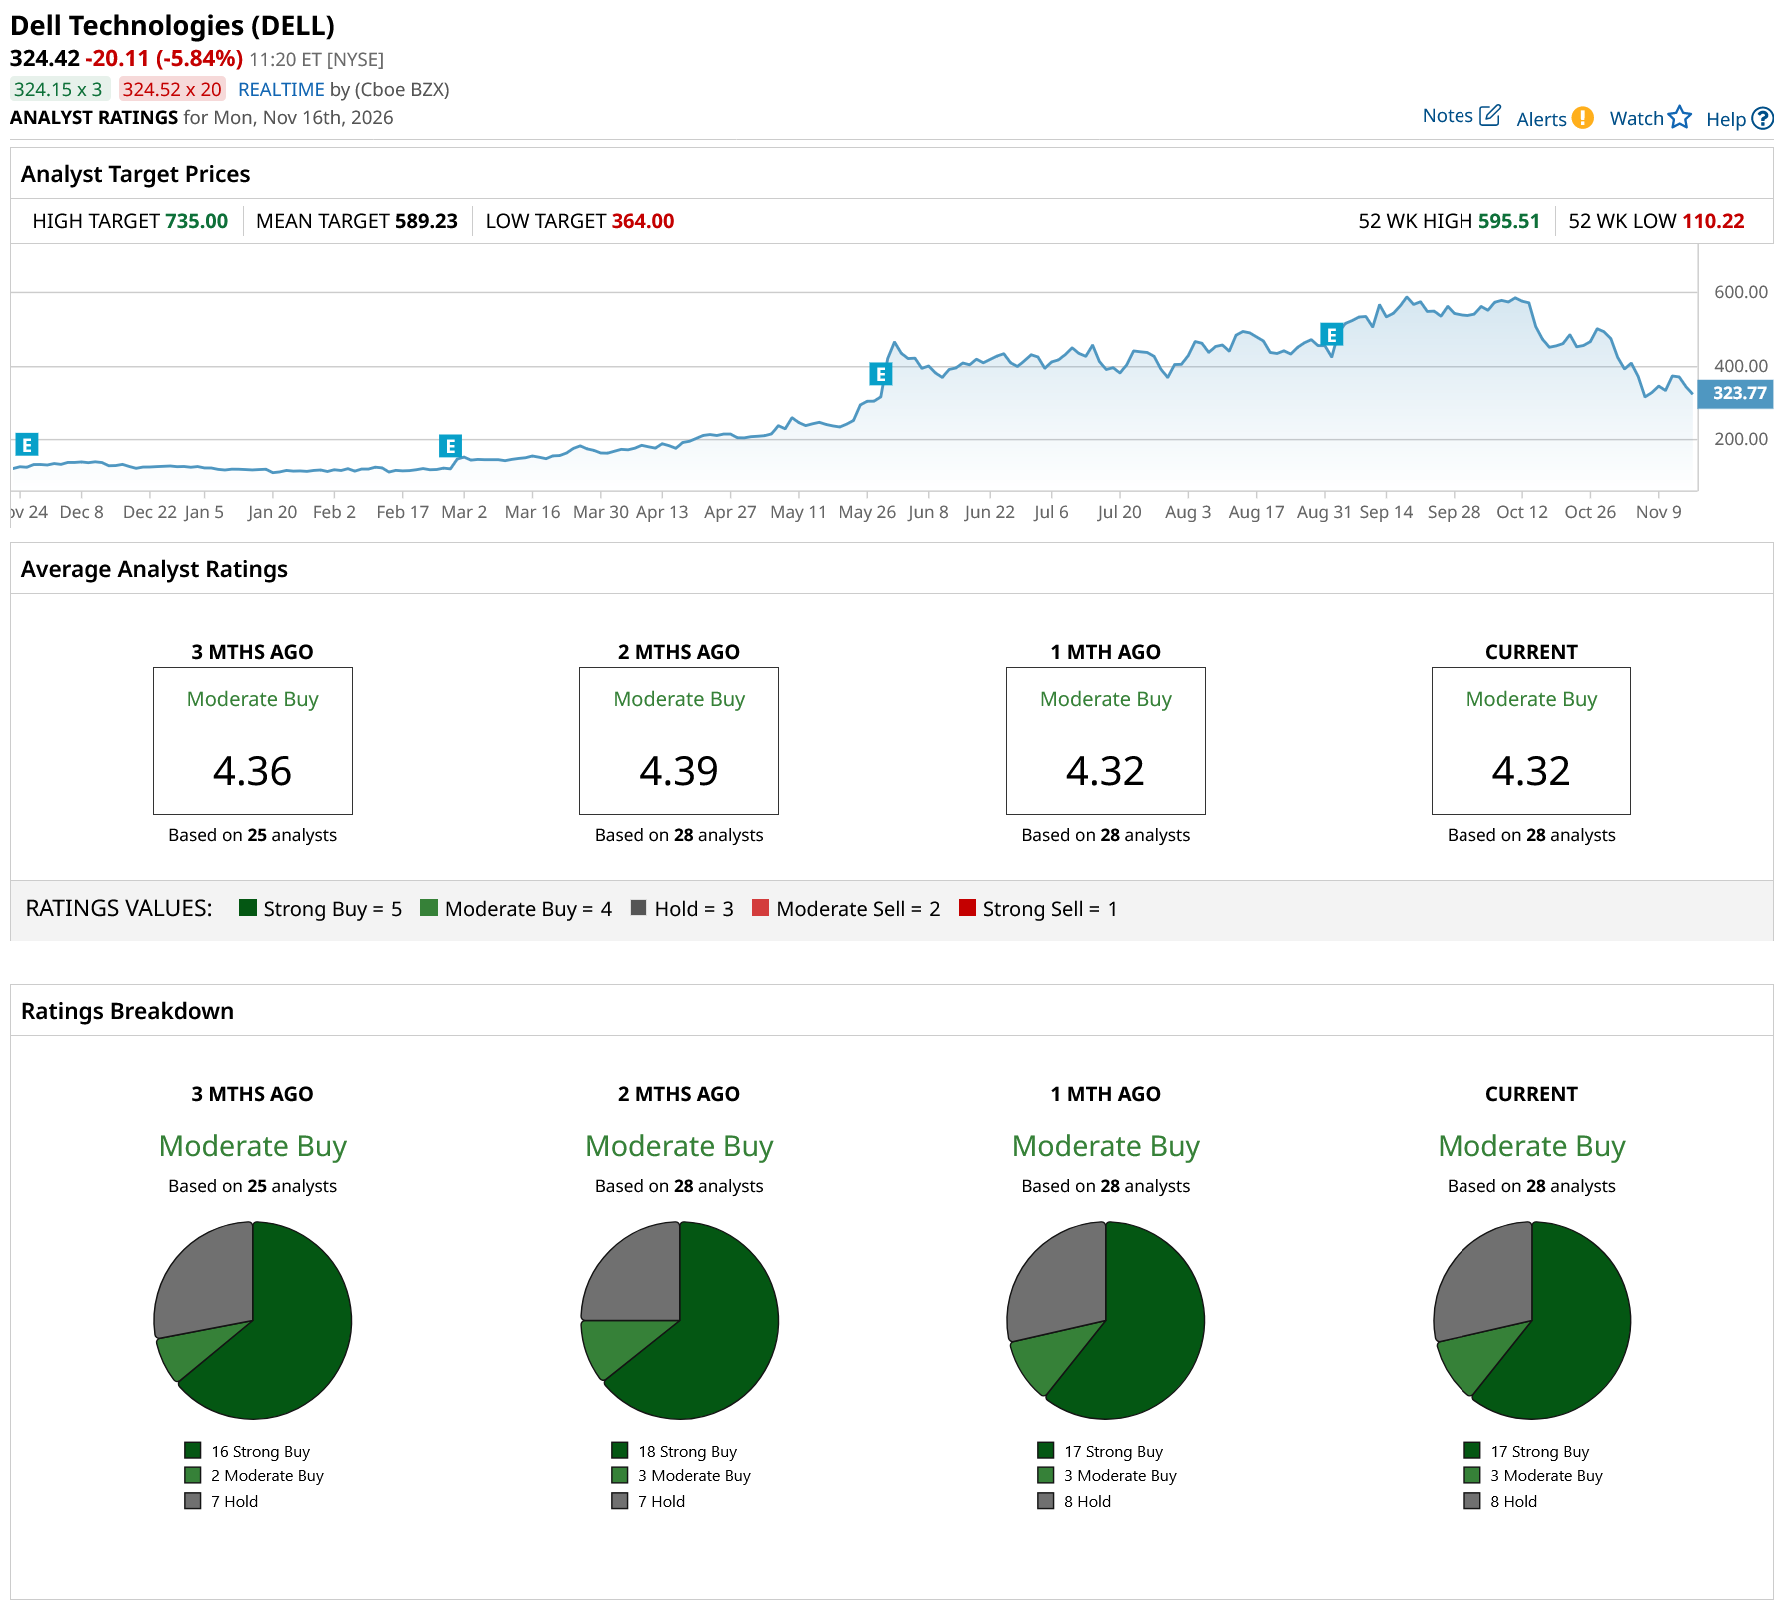
Wall Street analysts maintain a “Moderate Buy” consensus rating on DELL stock, with most analysts still recommending a “Strong Buy.” Furthermore, their average price target of $589.23 suggests approximately 71% upside from the stock’s recent closing price of $344.53 on Friday.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.