


EN
Are Wall Street Analysts Predicting Edwards Lifesciences Stock Will Climb or Sink?
Edwards Lifesciences Corporation (EW), headquartered in Irvine, California, provides products and technologies for structural heart disease and critical care monitoring. Valued at $61.6 billion by market cap, the company offers products such as tissue replacement heart valves, heart valve repair, hemodynamic monitoring devices, angioscopy equipment, oxygenators, and pharmaceuticals.
Shares of this leading global structural heart innovation company have outperformed the broader market over the past year. EW has gained 24.7% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. In 2026, EW stock is up 26.2%, surpassing SPX’s 10.5% rise on a YTD basis.
Zooming in further, EW’s outperformance is also apparent compared to iShares U.S. Medical Devices ETF (IHI). The exchange-traded fund has declined about 6.3% over the past year. Moreover, the stock’s double-digit returns on a YTD basis outshine the ETF’s 6.1% losses over the same time frame.
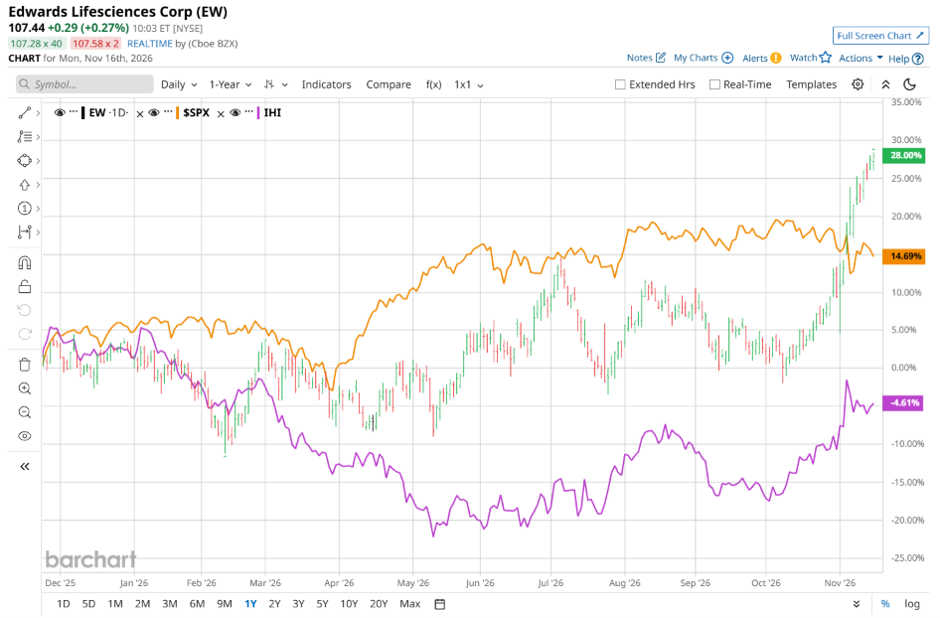
EW’s outperformance reflects sustained operational momentum across its core structural heart portfolio, propelling shares near 52-week highs above $105. The rally has been anchored by surging adoption in its Transcatheter Mitral and Tricuspid Therapies (TMTT) segment, where sales jumped 44% year over year in Q3 on the back of strong demand for its PASCAL, EVOQUE, and SAPIEN M3 platforms. Alongside steady growth in its flagship Transcatheter Aortic Valve Replacement (TAVR) franchise and key regulatory approvals, these catalysts enabled EW to deliver double-digit top-line growth and raise its full-year 2026 sales and adjusted EPS guidance, reinforcing investor confidence in its durable long-term trajectory.
On Nov. 4, EW shares closed up over 4% after reporting its Q3 results. Its revenue stood at $1.7 billion, up 10.5% year over year. The company’s adjusted EPS came in at $0.80, up 19.4% from the year-ago quarter.
For the current fiscal year, ending in December, analysts expect EW’s EPS to grow 17.6% to $3.01 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Among the 30 analysts covering EW stock, the consensus is a “Strong Buy.” That’s based on 23 “Strong Buy” ratings, two “Moderate Buys,” and five “Holds.”
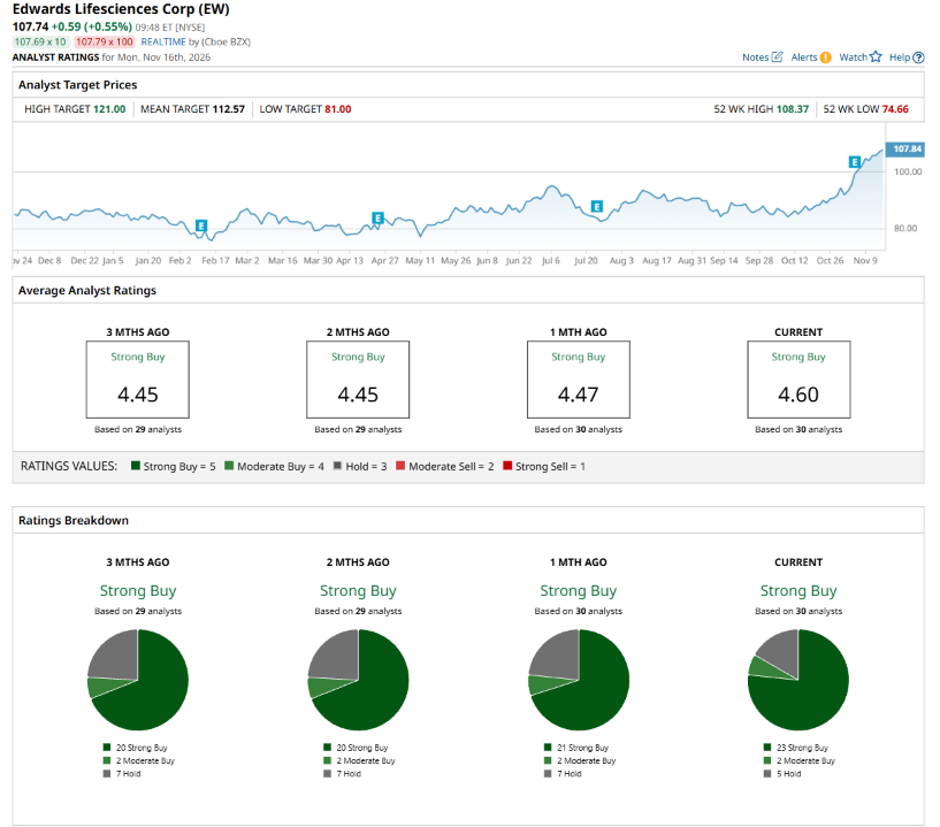
This configuration is more bullish than a month ago, with 21 analysts suggesting a “Strong Buy.”
On Nov. 9, TD Cowen analyst Jaret Seiberg reiterated a “Buy” rating on EW and set a price target of $117, implying a potential upside of 8.6% from current levels.
The mean price target of $112.57 represents a 4.5% premium to EW’s current price levels. The Street-high price target of $121 suggests an upside potential of 12.3%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.