


EN
Auto parts retailer stocks Q3 highlights: Monro
As the craze of earnings season draws to a close, here’s a look back at some of the most exciting (and some less so) results from Q3. Today, we are looking at auto parts retailer stocks, starting with Monro NASDAQ:MNRO.
Cars are complex machines that need maintenance and occasional repairs, and auto parts retailers cater to the professional mechanic as well as the do-it-yourself (DIY) fixer. Work on cars may entail replacing fluids, parts, or accessories, and these stores have the parts and accessories or these jobs. While e-commerce competition presents a risk, these stores have a leg up due to the combination of broad and deep selection as well as expertise provided by sales associates. Another change on the horizon could be the increasing penetration of electric vehicles.
The 5 auto parts retailer stocks we track reported a softer Q3. As a group, revenues were in line with analysts’ consensus estimates.
While some auto parts retailer stocks have fared somewhat better than others, they have collectively declined. On average, share prices are down 4.8% since the latest earnings results.
Weakest Q3: Monro NASDAQ:MNRO
Started as a single location in Rochester, New York, Monro (NASDAQ:MNRO) provides common auto services such as brake repairs, tire replacements, and oil changes.
Monro reported revenues of $283.6 million, down 1.8% year on year. This print was in line with analysts’ expectations, but overall, it was a sluggish quarter for the company with a significant miss of analysts’ EPS estimates and a slight miss of analysts’ gross margin estimates.
“Our second quarter comparable store sales declined 1.8%, reflecting an operating environment which continued to challenge the full-service auto aftermarket. This was driven by lower store traffic, consumers that continued to defer higher-ticket spending decisions and traded-down to lower cost alternatives in tires, and our use of self-funded promotions to drive unit growth in our brake category. The effectiveness of our ConfiDrive courtesy inspection process helped us drive average repair order growth in the quarter, and it was a key contributor to the comparable store sales gains we saw in batteries and maintenance services. These results reinforce that Monro’s full-service model is a genuine competitive advantage, and that when we execute it well, customers respond. The ability to identify a customer’s vehicle needs in real time, communicate them clearly, and address them with quality and care is what distinguishes a full-service provider, and our results in these categories reflect that strength. The traction we’re seeing from our District Manager Toolkit continues to build. With the toolkit now deployed across a majority of our store network and our newly established operating efficiency team actively coaching and training in the field, we are seeing early but meaningful bottom-line improvement in a subset of our locations. Importantly, we maintained our marketing investment during the quarter, even as sales fell short of where we wanted them to be,” said Peter Fitzsimmons, President and Chief Executive Officer.
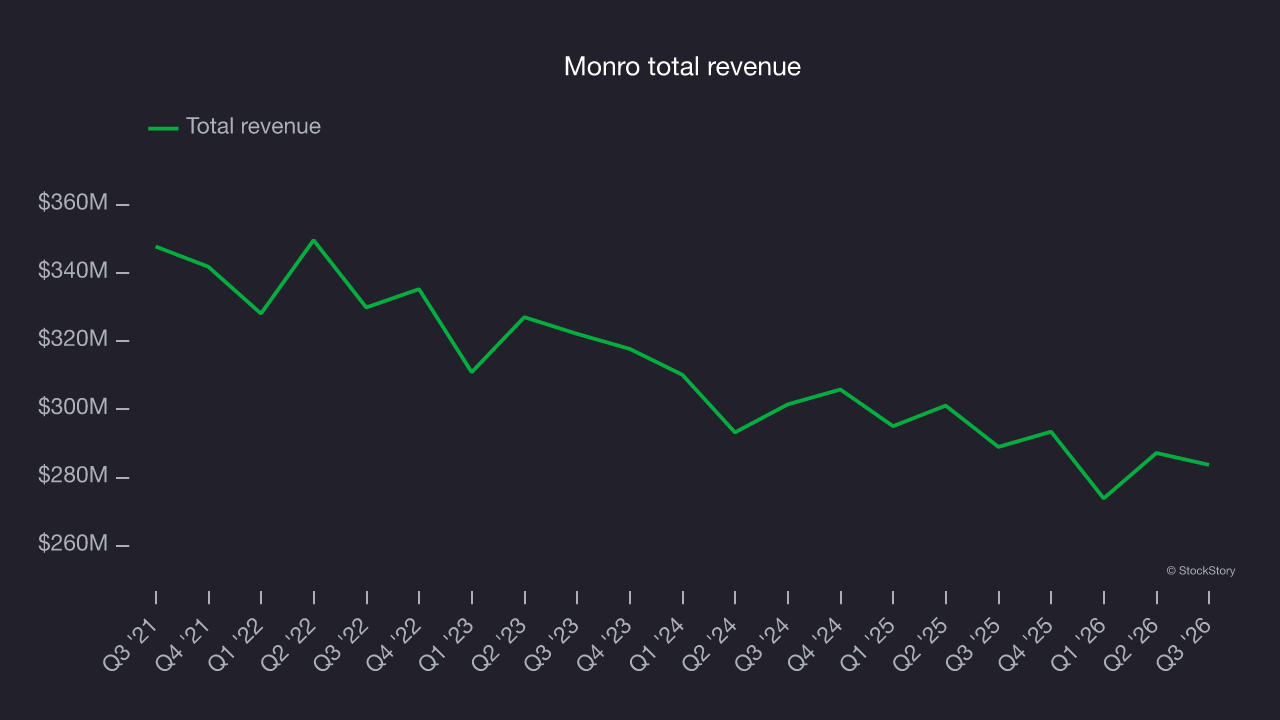
Monro delivered the slowest revenue growth among its peers. The market seems disappointed with the results as the stock is down 26.7% since reporting and currently trades at $10.48.
Read our full report on Monro here, it’s free.
Best Q3: O'Reilly (NASDAQ:ORLY)
Serving both the DIY customer and professional mechanic, O’Reilly Automotive (NASDAQ:ORLY) is an auto parts and accessories retailer that sells everything from fuel pumps to car air fresheners to mufflers.
O'Reilly reported revenues of $5.12 billion, up 8.8% year on year, outperforming analysts’ expectations by 2.1%. The business had a satisfactory quarter with a beat of analysts’ EPS estimates but a slight miss of analysts’ gross margin estimates.
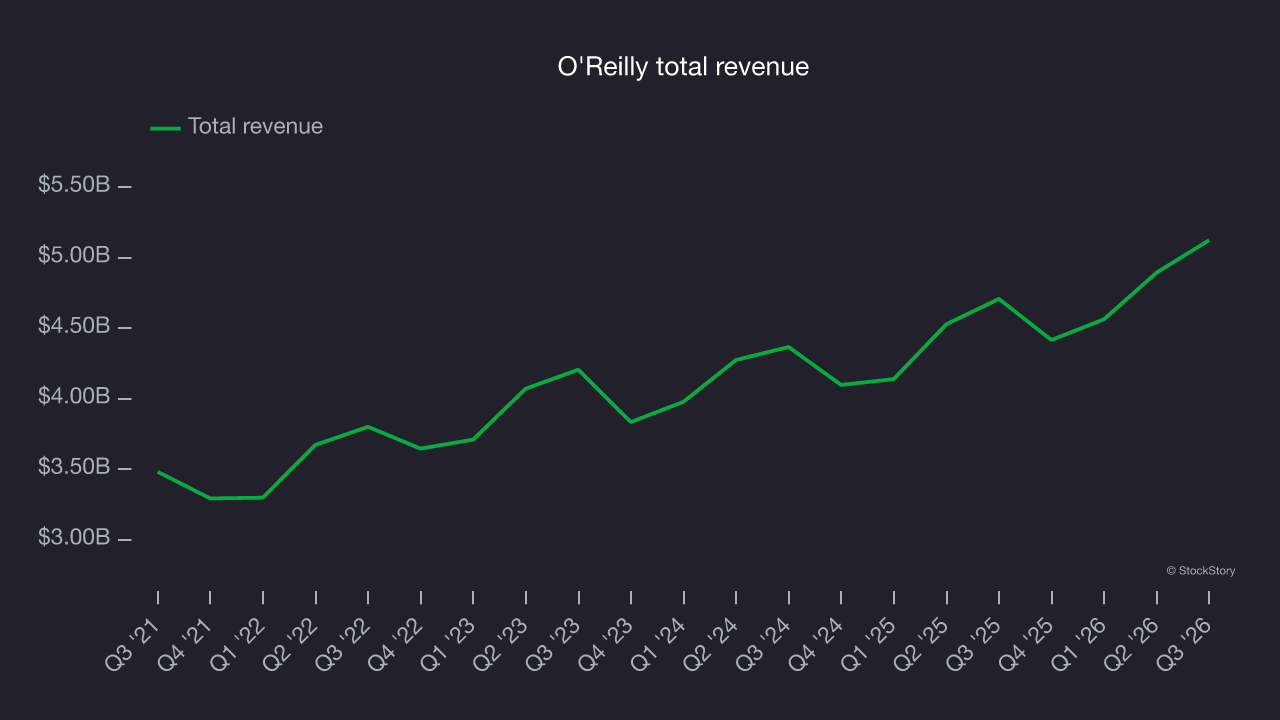
O'Reilly achieved the biggest analyst estimate beat, fastest revenue growth, and highest full-year guidance raise in the group. The market seems content with the results as the stock is up 2% since reporting. It currently trades at $92.23.
Is now the time to buy O'Reilly? Access our full analysis of the earnings results here, it’s free.
AutoZone (NYSE:AZO)
Aiming to be a one-stop shop for the DIY customer, AutoZone (NYSE:AZO) is an auto parts and accessories retailer that sells everything from car batteries to windshield wiper fluid to brake pads.
AutoZone reported revenues of $6.59 billion, up 5.6% year on year, falling short of analysts’ expectations by 1.6%. It was a softer quarter as it posted a slight miss of analysts’ gross margin estimates.
AutoZone delivered the weakest performance against analyst estimates of the whole group. Interestingly, the stock is up 16.3% since the results and currently trades at $3,260.
Read our full analysis of AutoZone’s results here.
Advance Auto Parts (NYSE:AAP)
Founded in Virginia in 1932, Advance Auto Parts (NYSE:AAP) is an auto parts and accessories retailer that sells everything from carburetors to motor oil to car floor mats.
Advance Auto Parts reported revenues of $2.01 billion, down 1.2% year on year. This print lagged analysts’ expectations by 1.4%. Overall, it was a softer quarter as it also recorded full-year EPS guidance slightly missing analysts’ expectations and gross margin in line with analysts’ estimates.
Advance Auto Parts had the weakest full-year guidance update among its peers. The stock is down 10.4% since reporting and currently trades at $45.47.
Read our full, actionable report on Advance Auto Parts here, it’s free.
Genuine Parts (NYSE:GPC)
Largely targeting the professional customer, Genuine Parts (NYSE:GPC) sells auto and industrial parts such as batteries, belts, bearings, and machine fluids.
Genuine Parts reported revenues of $6.52 billion, up 4.2% year on year. This result met analysts’ expectations. Taking a step back, it was a mixed quarter as it also logged a narrow beat of analysts’ gross margin estimates but full-year EPS guidance slightly missing analysts’ expectations.
The stock is down 5.3% since reporting and currently trades at $123.34.
Read our full, actionable report on Genuine Parts here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.