


EN
Discount retailer stocks Q2 results: Benchmarking Ollie's
Wrapping up Q2 earnings, we look at the numbers and key takeaways for the discount retailer stocks, including Ollie's NASDAQ:OLLI and its peers.
Discount retailers understand that many shoppers love a good deal, and they focus on providing excellent value to shoppers by selling general merchandise at major discounts. They can do this because of unique purchasing, procurement, and pricing strategies that involve scouring the market for trendy goods or buying excess inventory from manufacturers and other retailers. They then turn around and sell these snacks, paper towels, toys, clothes, and myriad other products at highly enticing prices. Despite the unique draw and lure of discounts, these discount retailers must also contend with the secular headwinds of online shopping and challenged retail foot traffic in places like suburban strip malls.
The 5 discount retailer stocks we track reported a favorable Q2. As a group, revenues beat analysts’ consensus estimates by 0.7% while next quarter’s revenue guidance was 2.8% above.
In light of this news, share prices of the companies have held steady. On average, they are relatively unchanged since the latest earnings results.
Ollie's NASDAQ:OLLI
Often located in suburban or semi-rural shopping centers, Ollie’s Bargain Outlet (NASDAQ:OLLI) is a discount retailer that acquires excess inventory then sells at meaningful discounts.
Ollie's reported revenues of $741.3 million, up 9.1% year on year. This print fell short of analysts’ expectations by 1.2%, but it was still a favorable quarter for the company with a solid beat of analysts’ EBITDA estimates and a beat of analysts’ EPS estimates.
Mr. van der Valk continued, “Consumers continue to seek value and many of the same pressures affecting our customers are creating buying opportunities across the closeout market. We continue to see strong deal flow and remain committed to reinvesting in price and strengthening our competitive position. With a flexible business model, deep vendor relationships, growing scale, and a talented team, we believe Ollie's is well positioned to deliver long-term profitable growth through any retail environment.”
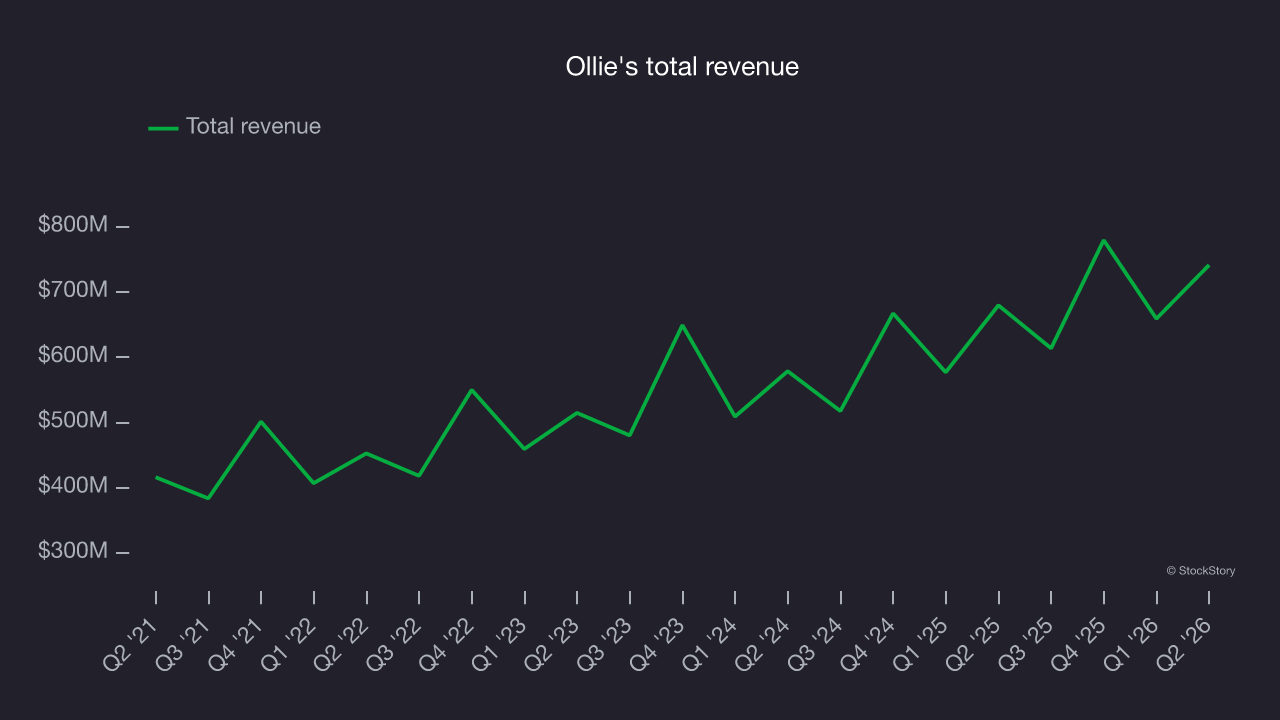
Ollie's delivered the weakest performance against analyst estimates and weakest full-year guidance update in the group. Interestingly, the stock is up 31% since reporting and currently trades at $94.76.
Is now the time to buy Ollie's? Access our full analysis of the earnings results here, it’s free.
Best Q2: Five Below (NASDAQ:FIVE)
Often facilitating a treasure hunt shopping experience, Five Below (NASDAQ:FIVE) is an American discount retailer that sells a variety of products from mobile phone cases to candy to sports equipment for largely $5 or less.
Five Below reported revenues of $1.26 billion, up 22.9% year on year, outperforming analysts’ expectations by 3.6%. The business had an impressive quarter with EPS guidance for next quarter exceeding analysts’ expectations and a solid beat of analysts’ gross margin estimates.
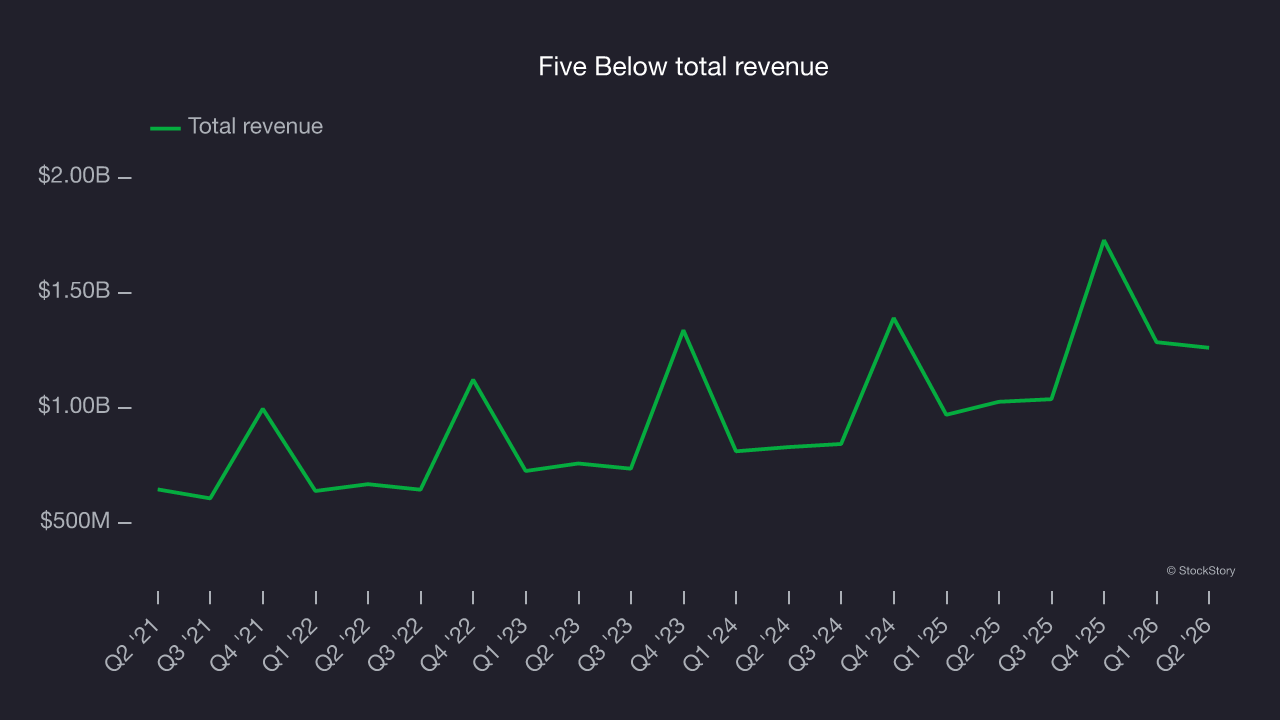
Five Below delivered the biggest analyst estimate beat, highest guidance raise, and fastest revenue growth of the whole group. The market seems content with the results as the stock is up 1.5% since reporting. It currently trades at $246.68.
Is now the time to buy Five Below? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: TJX (NYSE:TJX)
Initially based on a strategy of buying excess inventory from manufacturers or other retailers, TJX (NYSE:TJX) is an off-price retailer that sells brand-name apparel and other goods at prices much lower than department stores.
TJX reported revenues of $15.18 billion, up 5.4% year on year, in line with analysts’ expectations. It was a softer quarter as it posted EPS guidance for next quarter missing analysts’ expectations and full-year EPS guidance slightly missing analysts’ expectations.
TJX delivered the slowest revenue growth among its peers. As expected, the stock is down 11.1% since the results and currently trades at $134.10.
Read our full analysis of TJX’s results here.
Burlington (NYSE:BURL)
Founded in 1972 as a discount coat and outerwear retailer, Burlington Stores (NYSE:BURL) is now an off-price retailer that has broadened into general apparel, footwear, and home goods.
Burlington reported revenues of $3.00 billion, up 11% year on year. This number missed analysts’ expectations by 0.8%. Zooming out, it was a satisfactory quarter as it also produced a beat of analysts’ EPS estimates but EPS guidance for next quarter missing analysts’ expectations significantly.
Burlington had the weakest guidance update of the whole group. The stock is down 22% since reporting and currently trades at $245.
Read our full, actionable report on Burlington here, it’s free.
Ross Stores (NASDAQ:ROST)
Selling excess inventory or overstocked items from other retailers, Ross Stores (NASDAQ:ROST) is an off-price concept that sells apparel and other goods at prices much lower than department stores.
Ross Stores reported revenues of $6.26 billion, up 13.3% year on year. This print surpassed analysts’ expectations by 1.8%. Overall, it was a very strong quarter as it also put up a beat of analysts’ EPS estimates and a solid beat of analysts’ gross margin estimates.
The stock is flat since reporting and currently trades at $230.01.
Read our full, actionable report on Ross Stores here, it’s free.
Market update
Over the past year, investors have been forced to repeatedly answer the same question: What is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Growth Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.