


EN
Is Wall Street Bullish or Bearish on Valero Energy Stock?
Valero Energy Corporation (VLO), headquartered in San Antonio, Texas, manufactures, markets, and distributes petroleum-based and low-carbon liquid transportation fuels and petrochemical products. Valued at $105.9 billion by market cap, the company produces conventional gasoline, diesel, jet fuel, heating oil, asphalt, feedstocks, aromatics, and crude oil under the Valero, Beacon, Diamond Shamrock, Shamrock, Ultramar, and Texaco brands.
Shares of this largest independent refiner have significantly outperformed the broader market over the past year. VLO has gained 108% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. In 2026, VLO stock is up 132.2%, surpassing SPX’s 10.5% rise on a YTD basis.
Zooming in further, VLO’s outperformance is also apparent compared to VanEck Oil Refiners ETF (CRAK). The exchange-traded fund has gained about 38.2% over the past year. Moreover, VLO’s triple-digit returns on a YTD basis outshine the ETF’s 52% gains over the same time frame.
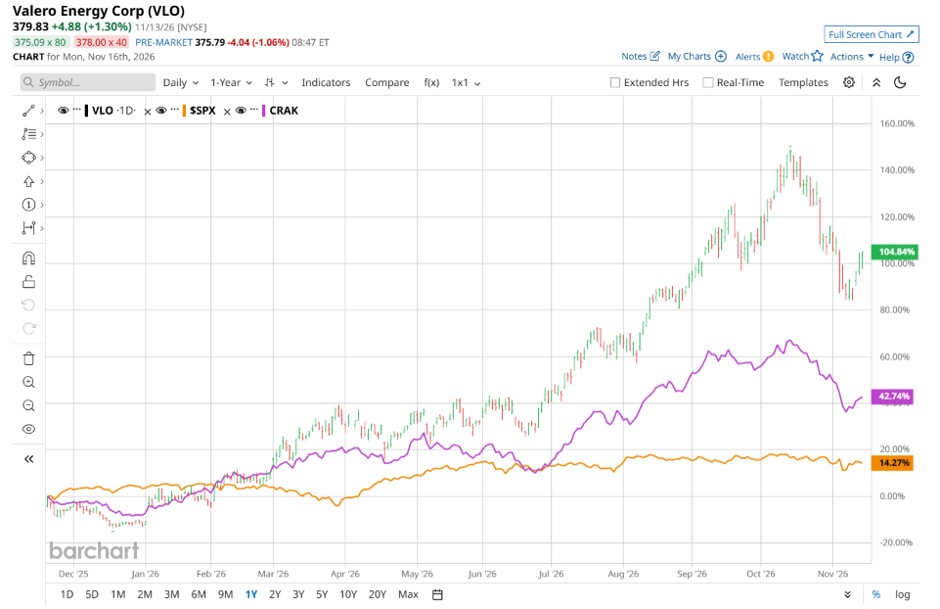
VLO’s significant outperformance reflects exceptional profitability driven by a robust refining macro environment, highlighted by surging crack spreads and tightening global product supply. The company capitalized on strong operational execution and high utilization rates across its complex refining system, which translated into record-shattering quarterly earnings, such as a monumental Q3 EPS beat driven by soaring refining margins and a major turnaround in its Renewable Diesel segment. Supported by a fortress balance sheet with massive cash generation, VLO successfully rewarded shareholders through steady dividends and debt reductions while strategically positioning itself to capture continued strength in global energy markets.
On Oct. 22, VLO shares closed down by 2.4% after reporting its Q3 results. Its adjusted EPS of $23.90 topped Wall Street expectations of $21.28. The company’s revenue was $46.1 billion, topping Wall Street forecasts of $37.4 billion.
For the current fiscal year, ending in December, analysts expect VLO’s EPS to rise 449.8% to $58.33 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 21 analysts covering VLO stock, the consensus is a “Moderate Buy.” That’s based on nine “Strong Buy” ratings, one “Moderate Buy,” nine “Holds,” and two “Strong Sells.”
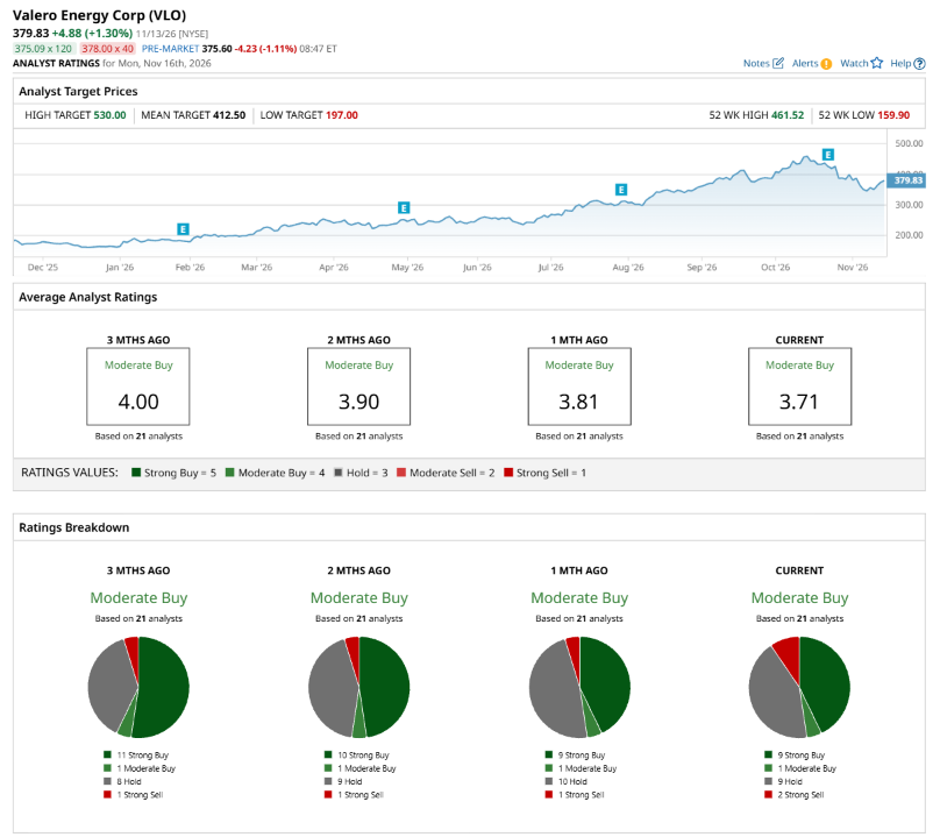
This configuration is more bearish than a month ago, with two analysts suggesting a “Strong Sell.”
On Nov. 3, Mizuho Financial Group, Inc. (MFG) analyst Nitin Kumar kept a “Neutral” rating on VLO and raised the price target to $436, implying a potential upside of 14.8% from current levels.
The mean price target of $412.50 represents an 8.6% premium to VLO’s current price levels. The Street-high price target of $530 suggests a notable upside potential of 39.5%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.