


EN
Arm Stock Could Be Worth Much More if These 3 Catalysts Materialize
The 24/7 Wall St. price target for Arm Holdings (NASDAQ:ARM) is $263 over the next 12 months. That is 31.64% above the model’s $199.78 reference price. The model rates Arm a buy with 70% confidence.
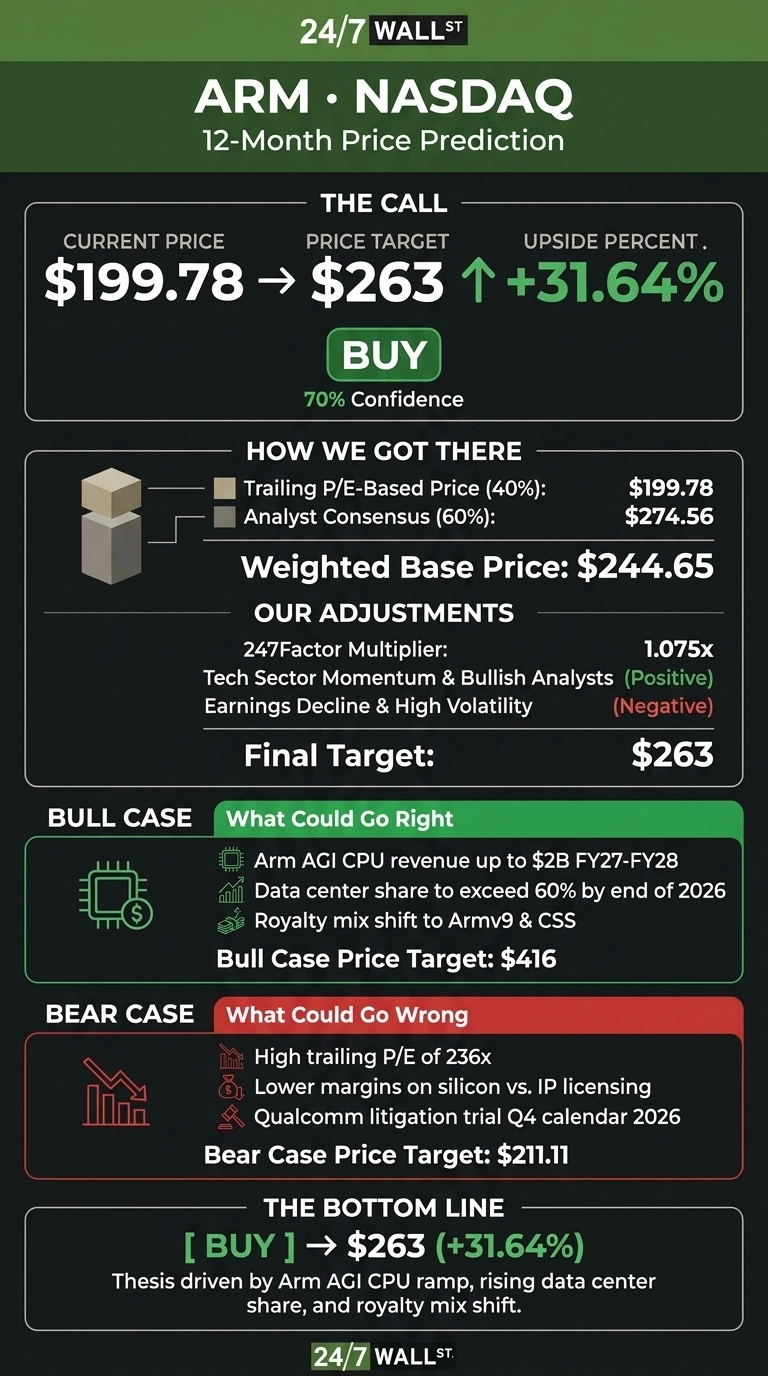 24/7 Wall St. Metric Value Current Price $199.78 Price Target from 24/7 Wall St. $263 Upside/Downside 31.64% Recommendation BUY Confidence Level 70%
Shares fell 7.57% to $184.65 in Friday’s session, which extends the implied upside to 42.4%.
Three catalysts carry the thesis: the Arm AGI CPU silicon ramp, rising data center share, and a royalty mix shift toward Armv9 and Compute Subsystems (CSS).
A Revenue Beat Got Lost in a 27.7% Monthly SlideArm rose 10.75% over the past week but lost 27.7% over the past month. It is still up 68.92% year to date. The stock sits 59.2% under its $452.70 52-week high and 84.6% above its $100.02 low.
Fiscal Q2 2027 revenue grew 27.1% to $1.443 billion, ahead of the $1.378 billion consensus. GAAP EPS of $0.12 missed the $0.4756 estimate. That figure included $46.6 million in equity-investment losses. Non-GAAP EPS rose 33% to 52 cents. Management guided fiscal Q3 non-GAAP EPS to 56 cents plus or minus 4 cents.
Three Catalysts That Could Push Arm Toward $416The bull case reaches $416, and three catalysts drive it.
- Arm AGI CPU. Management raised its confidence in reaching up to $2 billion of AGI CPU revenue across fiscal 2027 and 2028. First deliveries are due in fiscal Q4 2027, and Meta Platforms (NASDAQ:META) is the lead customer.
- Data center share. Arm’s server share at top hyperscalers grew from 15% in 2024 to more than 50% in 2025. Management expects it to top 60% by the end of 2026. Data center royalties doubled year over year.
- Royalty mix. License revenue rose 50% to $773 million. Arm also signed four new CSS licenses, and licensing tends to show up as royalties later.
Coverage features 8 Strong Buy ratings plus 20 Buy ratings, versus 14 Holds and 1 Sell.
What Could Derail the AGI CPU StoryAt 210x trailing earnings, Arm has little room for execution slips. Management expects first-generation AGI CPU gross margins in the 30% to 40% range. Company-wide gross margin is 92.5%. R&D rose 24% to $857 million. Arm China revenue slipped to $208.9 million from $243.1 million.
A licensing lawsuit with a major smartphone chipmaker heads to trial in Q4 calendar 2026. The weaker net income comparison reflects a tough base. The prior-year quarter included a $131 million gain on the Artisan sale. The higher spending also funds the silicon push. The bear case is $211.11.
Arm Trades at a Steep Premium to NVIDIA and BroadcomA fair comparison is NVIDIA (NASDAQ:NVDA) because it is both an Arm customer and a rival for AI spending. Its Vera CPU is built on Arm. NVIDIA grew revenue 105.85% at only 33x earnings.
A relevant peer is Broadcom (NASDAQ:AVGO) because it sells custom silicon to the same hyperscalers. AI semiconductor revenue rose 221% to $16.70 billion.
Company Latest Quarter Revenue Growth Operating Margin Arm 27.1% 18.5% NVIDIA 105.85% 60.4% Broadcom 85.5% 53.9%Both peers post faster growth and higher operating margins, so Arm’s premium depends entirely on its catalysts.
The 24/7 Wall St. price target depends on Arm executing on those catalysts. The AGI CPU ramp is the same kind of early inflection we reverse-engineered from past tech winners in a free Next Nvidia playbook.
Arm Earns a Buy Rating as the Q4 Ramp NearsThe 24/7 Wall St. price target of $263 carries a buy rating at 70% confidence. Data center royalty momentum is the factor that tips the scale.
The thesis strengthens if AGI CPU deliveries begin on schedule. The thesis weakens if silicon margins drag operating profit lower for several quarters. After a month-long selloff, the model’s target means upside from these levels.
The 24/7 Wall St. price target model projects where Arm could trade if current trends hold.
Year Price Target from 24/7 Wall St. 2026 $200.13 2027 $263.00 2028 $297.51 2029 $355.56 2030 $401.71Arm would need to keep executing on its current strategy for these projections to hold. A faster AGI CPU ramp might raises results well above them. Litigation or export controls could pull them below.