


EN
What Are Wall Street Analysts' Target Price for Honeywell International Stock?
With a market cap. of $70.6 billion, Honeywell International Inc. (HON) is a global pure-play automation company serving the building, industrial and process sectors through a broad portfolio of products, services and technology solutions. With more than 50,000 employees worldwide, the company leverages its Honeywell Technologies Accelerator operating system and Forge intelligence platform to drive innovation and advance the industrial sector's transition from automation to autonomy.
Shares of the Charlotte, North Carolina-based company have underperformed the broader market over the past 52 weeks. HON stock has risen 5.7% over this time frame, while the broader S&P 500 Index ($SPX) has increased 12.2%. In addition, shares of the company are up 8.3% on a YTD basis, compared to SPX’s 10.5% gain.
Moreover, shares of Honeywell International have lagged behind the State Street Industrial Select Sector SPDR ETF’s (XLI) 11% return over the past 52 weeks.
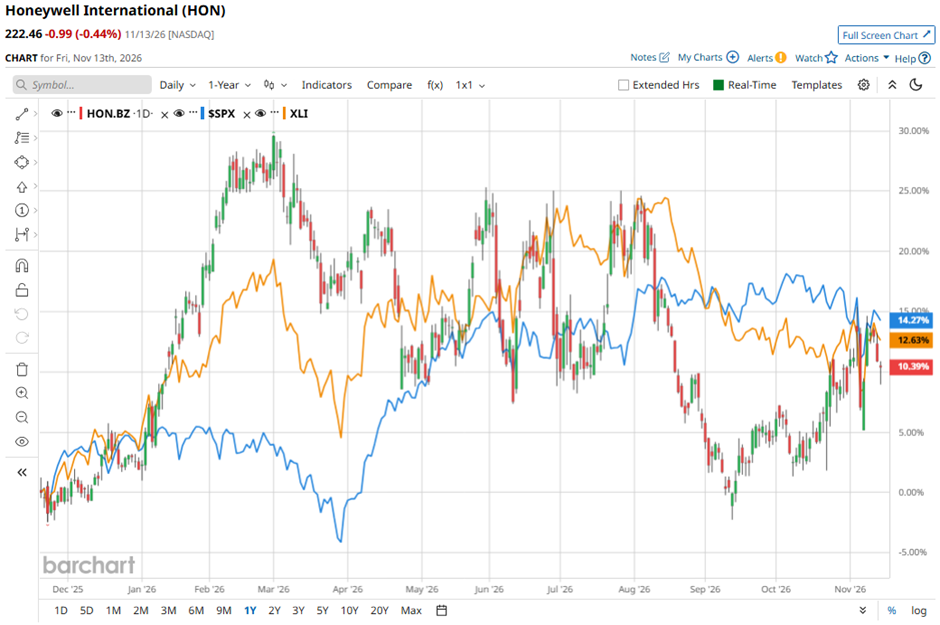
Honeywell International shares rose 1.7% on Oct. 22 after reporting stronger-than-expected Q3 2026 results, with organic sales growth of 7%, adjusted EPS jumping 34% year-over-year to $2.27 and revenue reaching $4.99 billion, supported by broad-based demand across all three segments. Profitability improved significantly, with operating income surging 79% to $740 million, operating margin expanding 640 basis points to 14.8% and segment margin rising 370 basis points to 21.3%, while free cash flow increased 15% to $688 million.
Investor sentiment was further boosted by raised fiscal 2026 guidance, with adjusted EPS lifted to $8.40 - $8.45, organic sales growth upgraded to 4% - 5%, and free cash flow expectations increased to approximately $2.1 billion.
For the fiscal year ending in December 2026, analysts expect HON’s adjusted EPS to decline 56.9% year-over-year to $8.44. However, the company's earnings surprise history is promising. It topped the consensus estimates in each of the last four quarters.
Among the 22 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on 12 “Strong Buy” ratings, one “Moderate Buy,” and nine “Holds.”
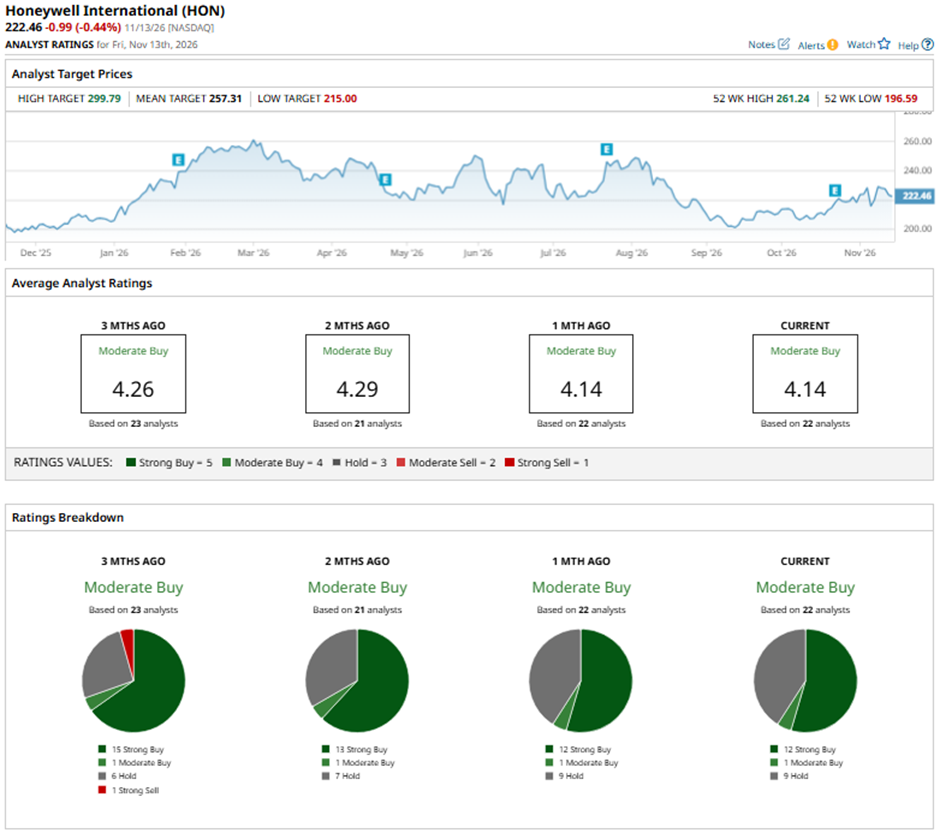
This configuration is less bullish than three months ago, with 15 “Strong Buy” ratings on the stock.
On Oct. 23, RBC Capital analyst Jeffrey Reive cut its price target on HON slightly to $269, while maintaining an “Outperform” rating.
The mean price target of $257.31 represents a 15.7% premium to HON’s current price levels. The Street-high price target of $299.79 suggests a 34.8% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.