


EN
What Thermo Fisher Scientific Holders Bought Into
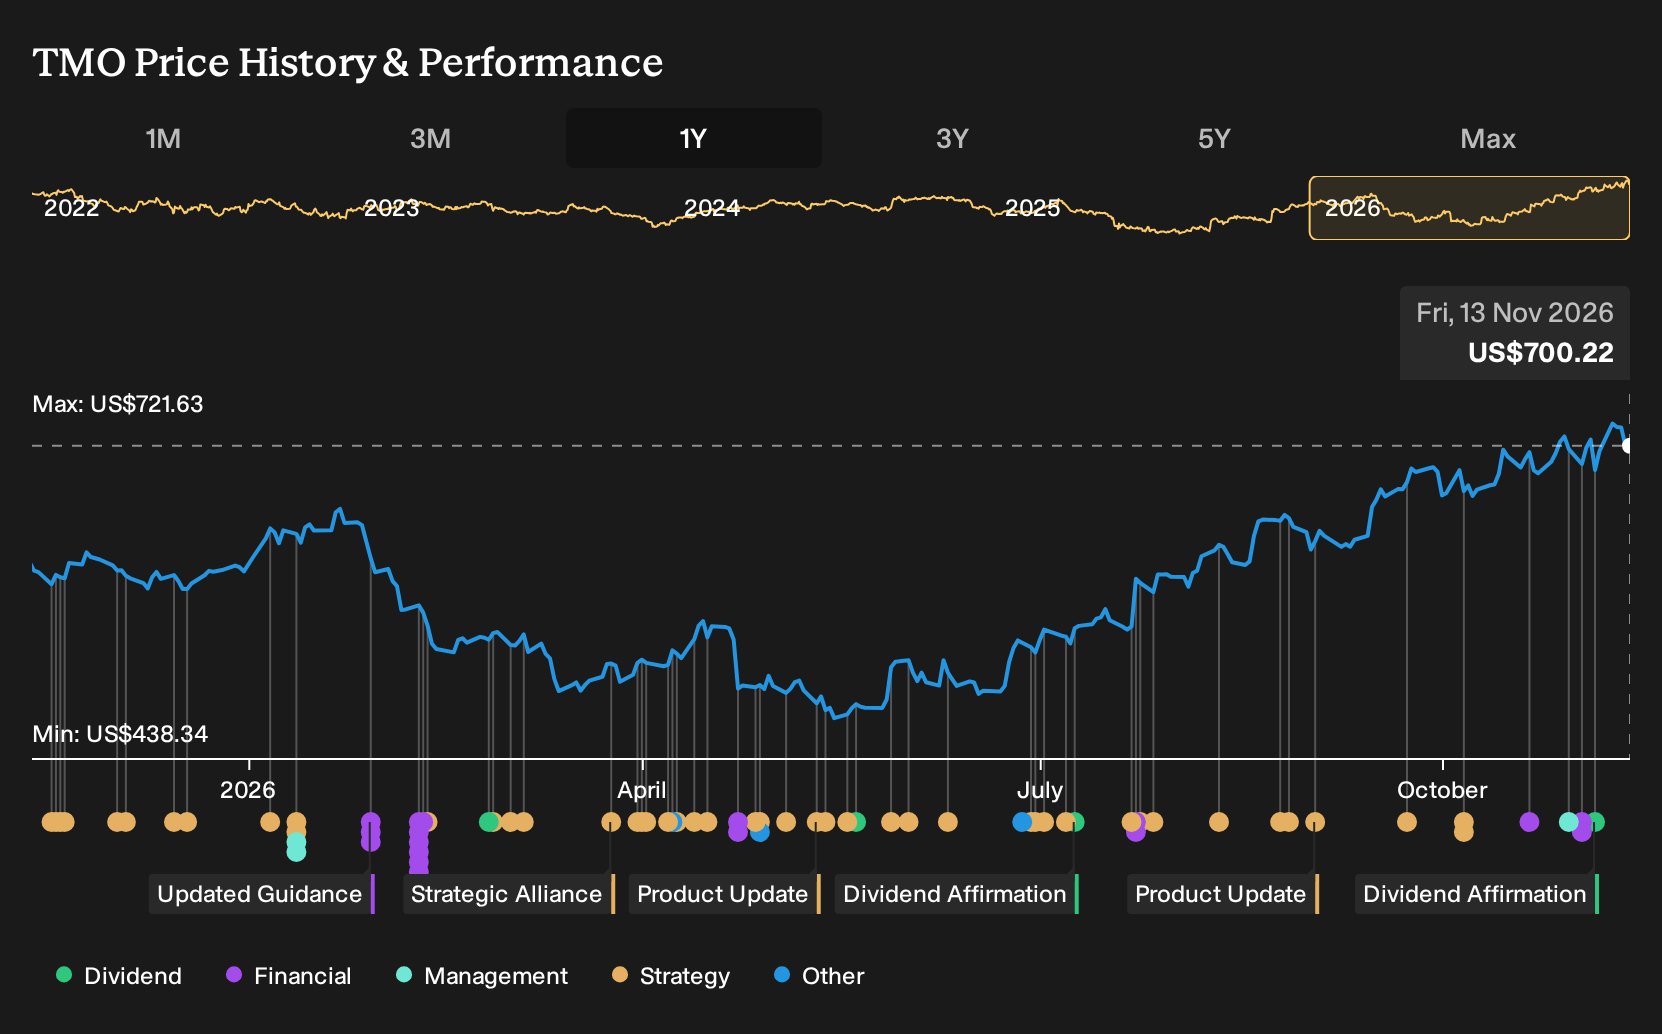
If you had looked at Thermo Fisher Scientific on 13 November 2025, you would have seen bullish analysts arguing that aging populations and gene therapies could justify a higher valuation, while more cautious voices flagged trade frictions, softer academic demand, and acquisition risk. For Thermo Fisher Scientific shareholders, the return over the past year was 23.9%, including dividends. If you were weighing those competing views back then, which parts of the business would you have focused on first?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Thermo Fisher Scientific has already moved. Pinpoint other ways to investigate the theme among 38 healthcare AI stocks.
The Two Thermo Fisher Scientific Stories Investors Were Weighing
Thermo Fisher Scientific shares cost US$580 at the start of the period, and investors were split between two clear stories about what that price already assumed.
On the optimistic side, the July 2025 bullish Narrative saw Fair Value at US$767 and leaned on a world of aging populations and fast growing gene therapies, with Thermo Fisher Scientific capturing that demand through mass spectrometry, electron microscopy and single use bioreactors.
The November 2025 more cautious Narrative put Fair Value at US$547 and rested on a 4.9% revenue growth assumption, while flagging ongoing funding strain in academic and government budgets as a risk to equipment and instrument demand.
What The Evidence Did To The Thermo Fisher Scientific Argument
Thermo Fisher Scientific’s Q3 2026 report showed revenue at US$12.14b and net income at US$1.72b, ahead of Q3 2025, which backed both Narratives that assumed rising earnings. The small shift in net margin, from 14.5% to 14.2%, challenged the more aggressive margin expansion baked into the bullish case. Overall, the period cut both ways.
The hinge assumption was not growth in isolation but how much profit Thermo Fisher Scientific could keep on each extra dollar of sales. When you test another stock, compare management’s long term margin story with the reported net margin trend, rather than looking only at the headline revenue line.
What Thermo Fisher Scientific's Price Now Asks You To Believe
Thermo Fisher Scientific trades at US$700 today, with the bearish analyst Narrative on Simply Wall St placing Fair Value below that level. The Narrative focuses on how divesting the microbiology unit, while pharma and biotech demand improves, could still weigh on earnings power.
At this price you are effectively assuming Thermo Fisher Scientific converts stronger pipelines, bioproduction and clinical research work into durable earnings. How does the risk that divestiture related dilution and muted academic funding persist affect that assumption?
"Although Thermo Fisher Scientific is seeing healthier pipelines and AI supported R&D in pharma and biotech, the planned microbiology divestiture that removes US$645 million of revenue with only partial channel retention could mean that even sustained mid single digit growth in these end markets is not enough to prevent a drag on consolidated organic revenue and adjusted EPS."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 28% below our estimate - uses expanded manufacturing capacity to prioritize higher margin specialty films and services.
- Company 2 - 49% below our estimate - turns shopper and inventory data into AI-driven tools that deepen dealer software adoption.
- Company 3 - 42% below our estimate - expands local payment infrastructure so merchants route more transactions through premium services.
That is three of the list. See all 35 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com