


EN
Did Free Speed Upgrades Just Shift Charter Spectrum's (CHTR) Investment Narrative?
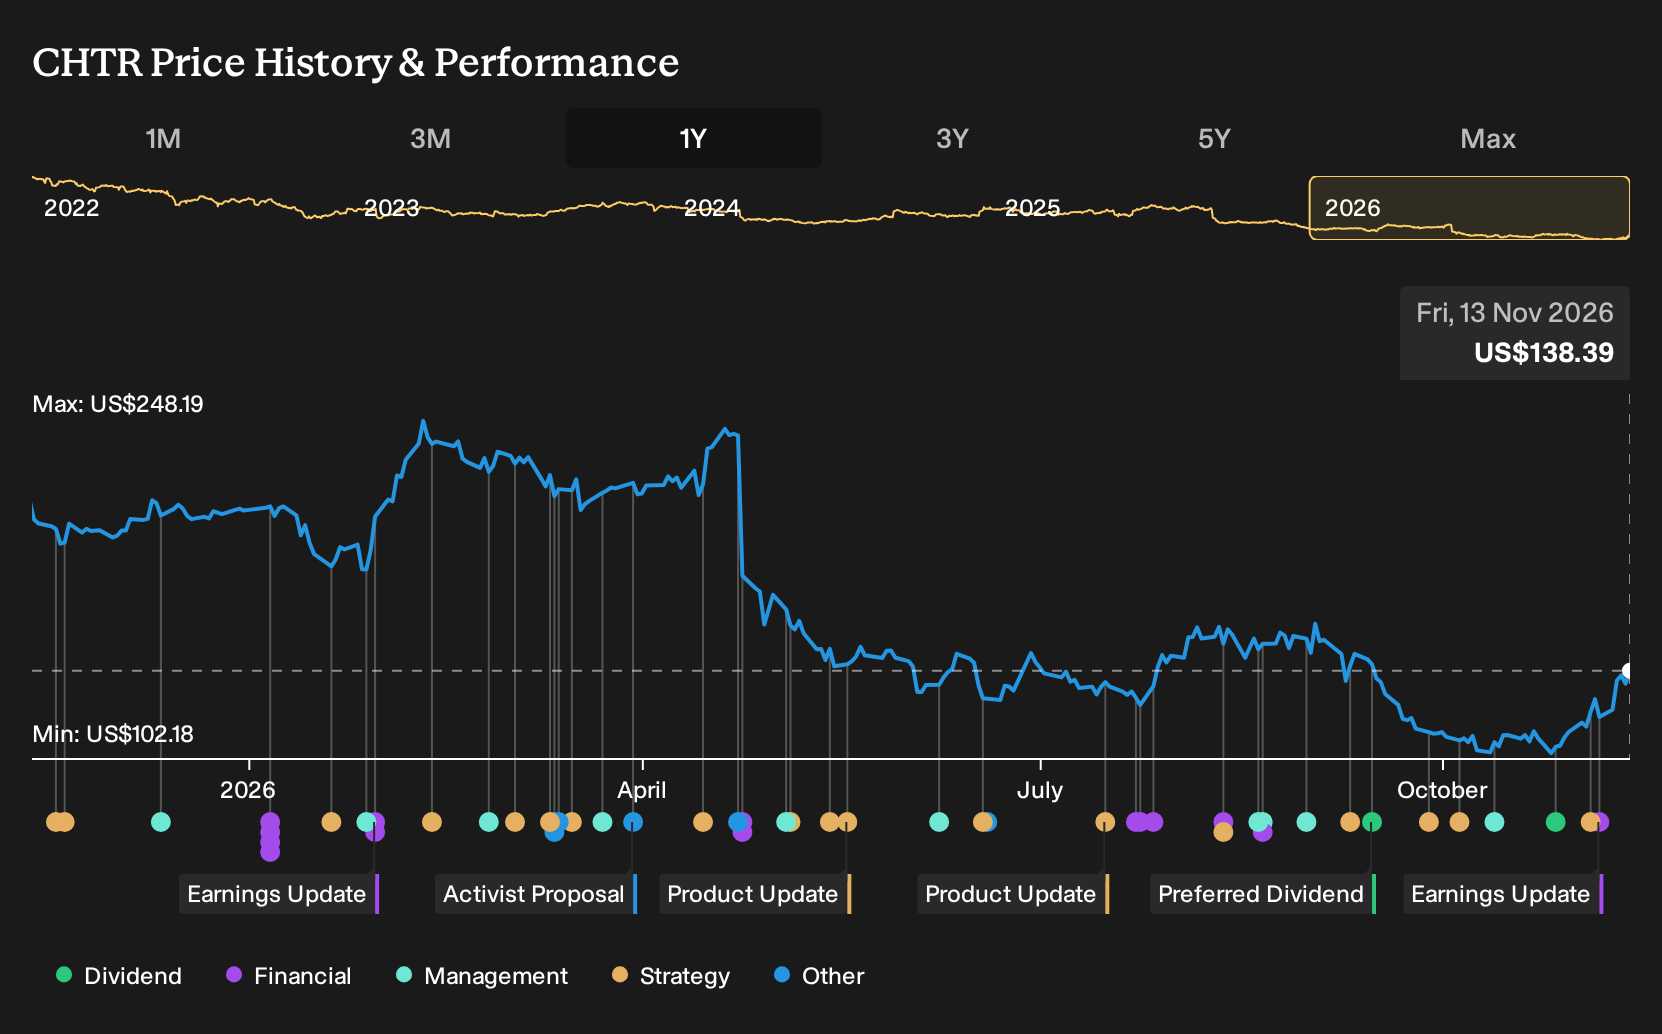
- Charter Communications reported third quarter 2026 sales of US$14.9b and a net loss of US$2.4b, while Spectrum Business launched a managed Cisco Secure Networking service and Spectrum promoted free high speed internet upgrades tied to the GTA 6 release to support customer demand.
- The mix of heavier losses, cost saving ambitions and high profile offers such as the gaming focused speed upgrade shows Charter Communications trying to protect cash generation while competing more aggressively for both enterprise and residential subscribers.
- We will now look at how Charter Communications' investment narrative could be affected by the free gaming focused broadband speed upgrade.
Compare Charter Communications' recent rebound and broadband push with a curated set of other telecom and infrastructure stocks that screen as 35 high quality undervalued stocks right now.
Charter Communications Investment Narrative Recap
To own Charter Communications, you need to be comfortable with a capital intensive broadband business that is still digesting heavy spending and a large one off charge. The third quarter print showed sales of US$14.9b but a net loss of US$2.4b and weaker margins, so the near term story revolves around stabilising profitability while subscriber trends remain in focus.
The key short term catalyst is execution on cost savings and capex discipline as the multi year network upgrade matures. The biggest risk is that interest costs and softer earnings coverage, highlighted by the recent loss, restrict flexibility just as competition and promotional intensity rise around broadband and mobile bundles.
The launch of Spectrum Business' Managed Cisco Secure Networking offer looks most relevant for Charter Communications right now. It speaks directly to enterprise demand for higher capacity and higher security connectivity as AI workloads grow, and it packages that into a subscription that covers hardware, software, design, and ongoing support.
For catalysts, this kind of managed service can deepen relationships with larger clients and support the case for the heavy network investment that david_6nroa, a Simply Wall St Community investor who wrote the narrative, focuses on. Execution risk remains. Charter still has to integrate complex security features, uphold a 100% uptime SLA, and manage capital intensity while interest coverage and margins sit under pressure.
Using revenue growth of 5.0% a year and a future profit margin of 9.1%, the narrative from david_6nroa values Charter Communications at US$294.71 per share, tying that outcome to higher estimated free cash flow and what it presents as a lower effective enterprise value.
Uncover why Charter Communications' fair value indicates a 113% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some analysts frame the risk very differently. You see broadband pressure and rising costs as the core problem, while the most pessimistic group already penciled in 6.9% annual revenue growth to about US$66.5b and earnings of US$5.3b by 2029 before this Charter Communications gaming promotion. They still set much lower targets, which shows how widely narratives can diverge.
Explore 6 other Charter Communications fair value estimates, including one that suggests as much as 51% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Charter Communications research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Charter Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charter Communications' overall financial health at a glance.
Looking For More Ideas Beyond Charter Communications?
If you want to cross check Charter Communications against other opportunities, the Simply Wall St Screener can help you quickly sort through listed businesses by quality, valuation, income potential, and balance sheet strength.
- For investors hunting for resilient balance sheets and robust fundamentals, start with this curated list of solid balance sheet and fundamentals (24 results) that can help you focus on financial strength first.
- If you prefer income potential and consistent payouts, scan through a hand picked set of companies in the 6 dividend fortresses that puts yield and stability side by side.
- When you want to spot underfollowed opportunities with solid numbers, run your eye over the 19 high quality undiscovered gems and see which businesses deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com