


EN
Leadership Reset Could Be A Game Changer For Nike Stock (NKE)
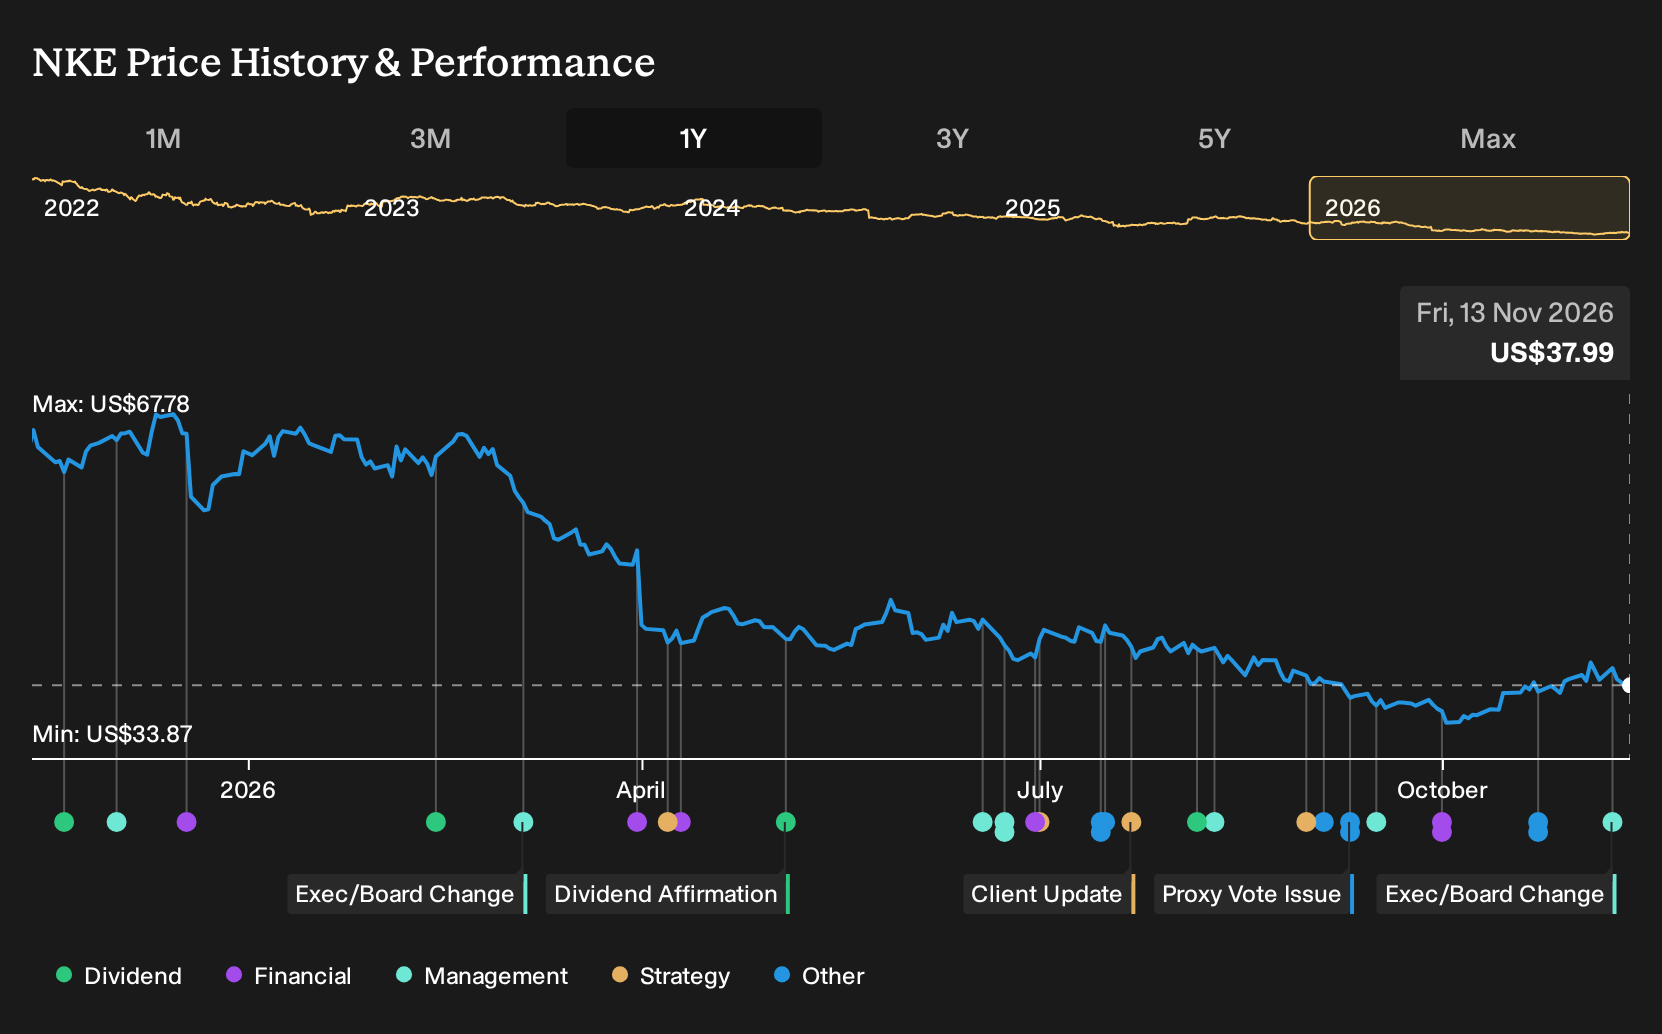
- On 9 November 2026, Nike appointed long-time finance leader Dan McKenzie as Vice President, Chief Accounting Officer and principal accounting officer, with CFO David Denton stepping back from his interim controller duties.
- The return of McKenzie, who previously spent more than 19 years inside Nike’s finance organisation, adds experienced oversight to accounting, finance operations and transformation efforts during a wider leadership reset.
- We will now look at how Nike's evolving leadership bench, including McKenzie's appointment, could shape the broader investment narrative.
Scan how NIKE’s leadership reset compares to other potential turnaround stories by reviewing a hand-picked list from 19 high quality undiscovered gems with strong underlying fundamentals.
NIKE Investment Narrative Recap
To own Nike, you need to believe the sport first reset can rebuild demand in Performance while eventually repairing the damaged Sportswear and Jordan lines. According to ANTONI0, a Simply Wall St Community investor who wrote the Narrative, the key question is whether operating margins can get back near historic levels rather than settling lower. The short term swing factor is whether the marketplace keeps cleaning up without crushing revenue further.
The biggest near term risk sits in that same margin story. Lifestyle demand may not fully come back, Greater China could stay smaller and Pace cost savings might be recycled into marketing instead of dropping to profit. The McKenzie appointment looks additive for execution but does not fundamentally change those operating risks on its own.
The most relevant move for this leadership change is Nike’s plan to give investors a detailed financial framework at the November 2026 investor day. That event is set up as the moment where Elliott Hill and David Denton explain how the turnaround, cost program and product strategy translate into margin and cash flow targets. McKenzie’s return puts a seasoned accounting voice into that process.
For you, the link is practical. Cleaner financial controls and a focused principal accounting officer can help the team deliver the Pace savings, protect already pressured gross margins and keep dividend decisions grounded in actual free cash generation. Given the concerns around dividend coverage and the risk that fixed costs magnify any revenue shortfall, consistent execution against whatever targets are outlined at the investor day becomes the key factor to watch.
ANTONI0’s narrative reaches a fair value of $41.00 by assuming Nike grows revenue about 12.9% a year and eventually earns a 6.7% profit margin, which together support higher normalised earnings and justify a value above what current trough level profitability alone might indicate.
Uncover why NIKE's fair value highlights an 8% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Some bullish analysts anchor on a different catalyst for Nike. They focus on the Pace cost program, arguing that if it lands as they expect, earnings could reach about US$4.4b by around October 2029 on roughly 3.3% annual revenue growth. That is a more optimistic storyline than ANTONI0’s, and it was formed before Dan McKenzie returned. Use that gap between narratives as an invitation to compare several viewpoints yourself and decide which assumptions feel realistic.
Explore 11 other NIKE fair value estimates, including one that suggests up to 35% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own analysis.
- A great starting point for your NIKE research is our analysis highlighting 1 important warning sign that could inform your investment decision.
- See our latest analysis for NIKE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to review NIKE's overall financial position at a glance.
Looking for more NIKE style investment ideas?
Once you have a handle on NIKE, it can help to widen the lens and compare it with other businesses that fit different return and risk profiles using the Simply Wall St Screener.
- For income focused investing where reliability matters, review a curated set of higher yielding payers through 6 dividend fortresses.
- If capital preservation and steadier profiles appeal more than excitement, scan for companies with sturdier metrics using the 29 resilient stocks with low risk scores.
- When you want quality businesses that are still off most investors’ radar, cast a wider net across 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com