


EN
Cui Dongshu: The value added of the automobile industry increased by 0.9% in October, and the pressure on traditional automobile consumption is high
The Zhitong Finance App learned that Cui Dongshu, Secretary General of the Passenger Transport Association, published an article stating that from January to October 2026, automobile production was 26.41 million units, down 4% year on year; new energy vehicle production was 14.48 million units, up 13% year on year, with a penetration rate of 55%; and fuel vehicle production was 11.93 million units, down 19% year on year. In October 2026, automobile production was 3.05 million units, down 8% year on year; new energy vehicle production was 2.03 million units, up 17% year on year, penetration rate 67%; fuel vehicle production was 1.02 million units, down 35% year on year. The value added of the automobile industry increased by 0.9% in October, and the value added of the automobile industry increased by 6.5% from January to October, showing strong performance.
Production and supply grew steadily from January to October of this year, the scale of market sales expanded, foreign trade grew rapidly, employment prices were generally stable, new quality productivity grew vigorously, and the operation of the national economy continued its overall steady and upward trend. However, under the impact of high international oil prices, the pressure on traditional automobile consumption is high.
The automobile industry has a strong ability to eliminate production. From January to October 2026, fixed asset investment in the automobile industry fell 7.9% year on year. It is still higher than the average of all industries of -8.1%, but higher than the decline in investment of -2.4% in the manufacturing industry.
In October '26, total retail sales of consumer goods amounted to 4646.3 billion yuan, an increase of 0.4% over the previous year. Among them, automobile consumption was 33.1 billion yuan, a year-on-year decrease of 21%; retail sales of consumer goods other than automobiles were 4316.2 billion yuan, an increase of 2.5%. From January to October, total retail sales of consumer goods amounted to 41646.4 billion yuan, an increase of 1.0% over the previous year. Among them, automobile consumption was 3265.3 billion yuan, a year-on-year decrease of 16%; retail sales of consumer goods other than automobiles amounted to 38381.1 billion yuan, an increase of 2.8%.
Automobile consumption in 2026 presents a complex situation of “policy continuation, market fragmentation, and pressure on demand”. The trade-in policy continues to gain strength, but the total retail volume is still declining due to factors such as the accelerated contraction of fuel vehicles, high prices suppressing consumer confidence, and a slump in the low-end market. The steady increase in consumption of petroleum products reflects the fact that residents' demand for travel is still rigid, and weak automobile consumption is more indicative of a marginal weakening of the will to spend on durable goods and disposable income.
Since the 2026 trade-in passenger car subsidies were far less strong than commercial vehicles, commercial vehicle subsidies contributed particularly well to NEV retail growth, and NEV passenger vehicles plummeted. Currently, there is a lot of pressure on entry-level passenger car consumption, and the high-end consumption of Chinese cars is too strong and the level of popularity is too low. It is hoped that in the future, there will be a strong long-term continuation policy, reducing personal taxes for car buyers, promoting new energy vehicles going to the countryside, setting standards for economical electric vehicles, optimizing C7 economy electric vehicle driver license applications, greater tax concessions for compliant pure electric vehicles with a battery life of less than 200 kilometers, and encouraging marriage and childbearing car purchases to promote economic growth.
1. Automobile consumption is declining relatively steadily
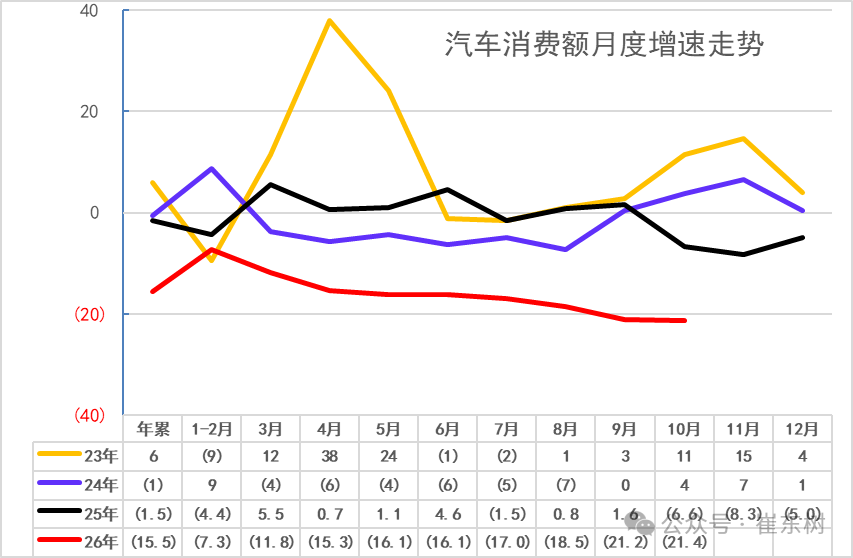
Since the decline in the property market in 2021, automobile consumption has risen from 3.94 trillion yuan in 2020 to 5.03 trillion yuan in 2024, breaking away from the passive situation of hovering around 3.9 trillion yuan for 3 consecutive years in 2018-2020. Since the decline in real estate favors consumption, the problem of investment squeezing consumption has improved. Currently, the problem of poor consumption has improved slightly. From January to October 2026, automobile consumption fell 15.5% year on year, and automobile consumption fell 21.4% year on year in October. After the base figure continued to rise, this year's decline was significant. The high base pressure was greatest in March, June, and September of 2025. The base figure for October this year was not high, but the trend pressure on automobile retail was still strong, and the impact on consumption with high fuel prices was severe.
2. Automobile production trend is weak in 2026
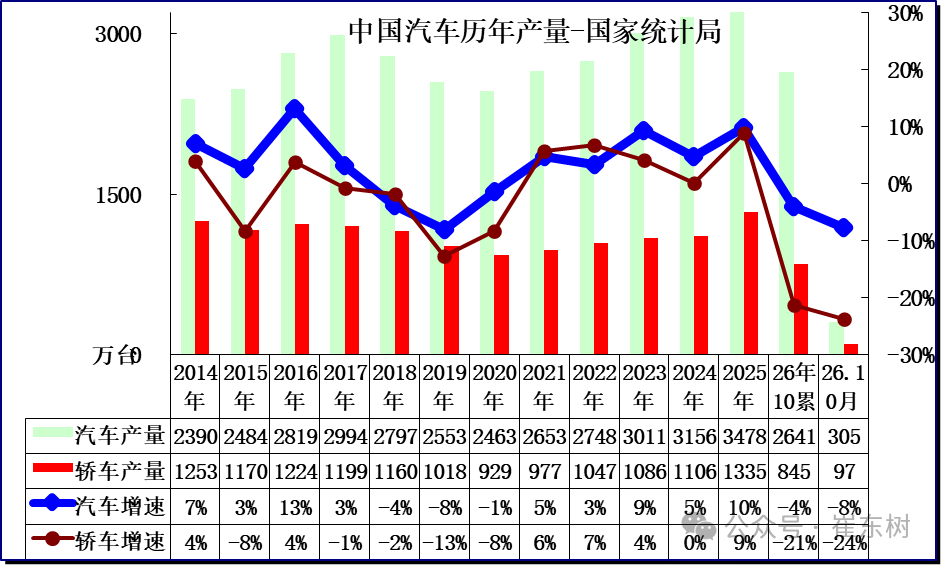
By product, in October, the output of 254 products out of 626 products in large-scale industries increased year-on-year. Among them, there were 3.045 million vehicles, a decrease of 7.7%, including 2.27 million new energy vehicles, an increase of 17.1%; power generation capacity of 794 billion kilowatt-hours, a decrease of 2.1%; and crude oil processing volume of 58.3 million tons, a decrease of 8.1%.
3. The value-added performance of automobiles changed greatly in 2026
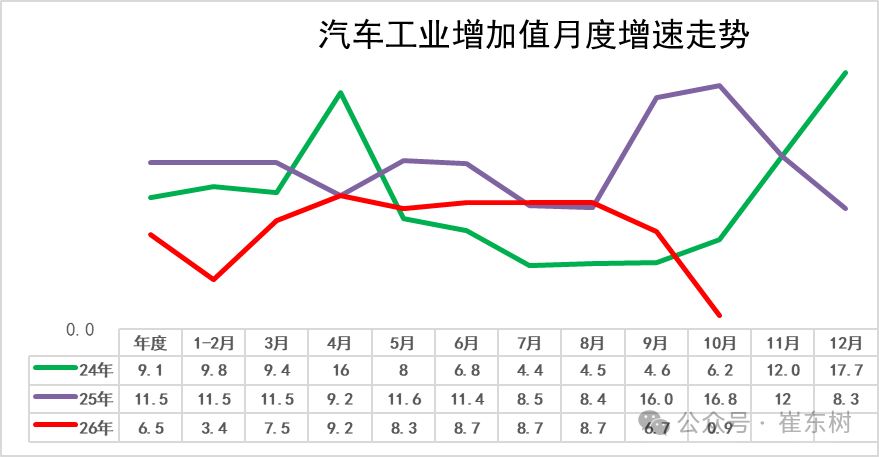
The value added of the automobile industry increased by 6.6% in 2020; the growth rate hovered at the level of 5.5% in 2021; the value added value of automobiles in 2022 was 6.3%, which was strong; the value added of the automobile industry increased by 13% in 2023, achieving super growth; the value added of 9.1% of automobiles increased relatively well in 2024; and the value added of the automobile industry increased by 11.5% in 2025.
From January to October '26, the value added of industries above scale increased by 5.3% year on year. In October, the value added of industries above scale actually increased 4.8% year on year. Among them, the value added of the automobile industry increased by 0.9% in October. Demand began to slump in October last year, but industrial value added was delayed by two months, and this year's pressure began to show. From January to October, the value added of large-scale industries increased by 5.3% year-on-year. Production in the automotive industry increased by 6.5%.
4. The utilization rate of automobile production capacity is relatively stable
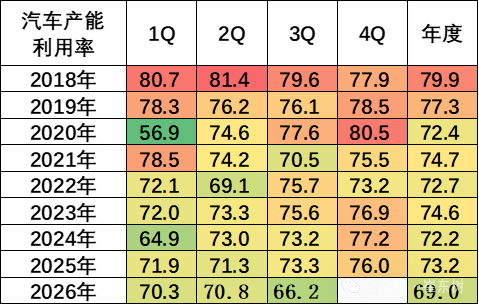
In 2020-2024, the national industrial capacity utilization rate remained within a small fluctuation range of 72.4 to 74.6. In the fourth quarter of 2024, the utilization rate of industrial capacity above the national scale was 76.2%, up 0.3 percentage points from the same period last year, and 1.1 percentage points higher than in the third quarter. In 2025, the utilization rate of industrial capacity above the national scale was 74.4%. By major industries, the automobile industry's capacity utilization rate in 2025 was 73.2%, which is relatively low.
From January to September 2026, the automobile industry's capacity utilization rate was 69%, down 4.2 percentage points from last year. In the first quarter of 2026, the automobile industry's capacity utilization rate was 70.3%, down 1.6 percentage points from last year; in the second quarter of 2026, the automobile industry's capacity utilization rate was 70.8%, down 0.5 percentage points from last year. In the third quarter of 2026, the automobile industry's capacity utilization rate was 66.2%, down 7.1 percentage points from last year.
5. The specific situation of automobile production is relatively normal
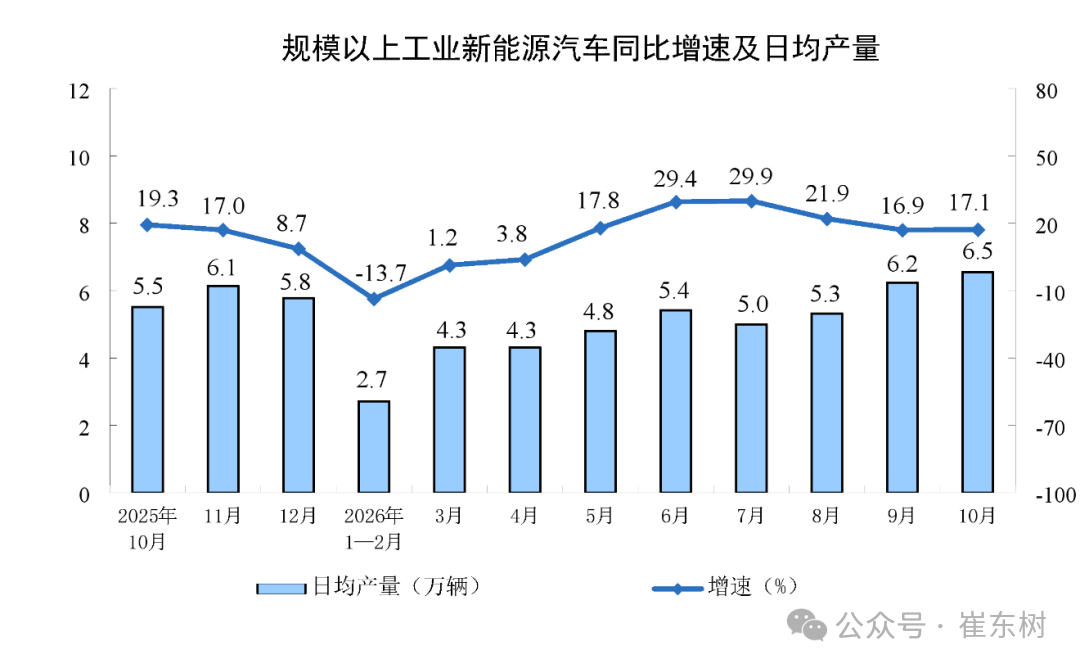
The average daily production of new energy vehicles in October 2026 was 65,000, an increase of 17.1% over the previous year. Due to the high base of new energy cars last year, production fluctuated greatly this year. The production of new energy vehicles in 2025 is better for small and micro electric vehicles. Demand is also strong in the middle and low end, so the sales growth rate is slightly lower than the sales growth rate. The sharp reduction in subsidies this year has had a big impact, but commercial vehicle subsidies are high, and the NEV commercial vehicle market has skyrocketed.
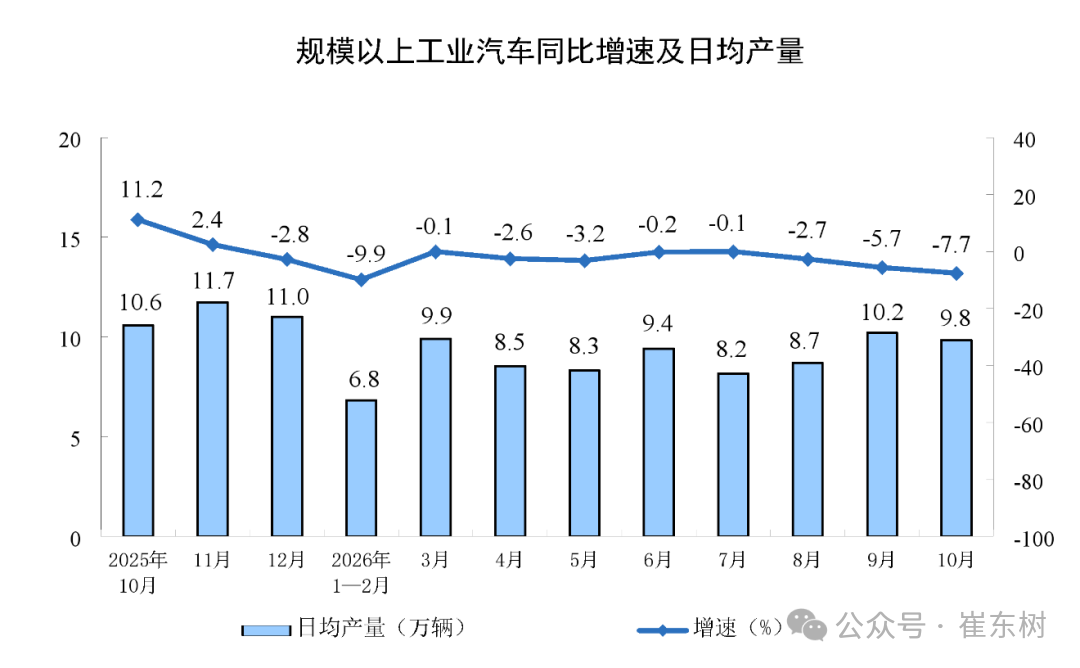
By product, in October 2026, the average number of cars per day was 98,000, a decrease of 7.7%. Considering the increase in the base figure from January to October 2025 and the contraction of policy subsidies in 2026, the growth rate from January to October this year was weak.
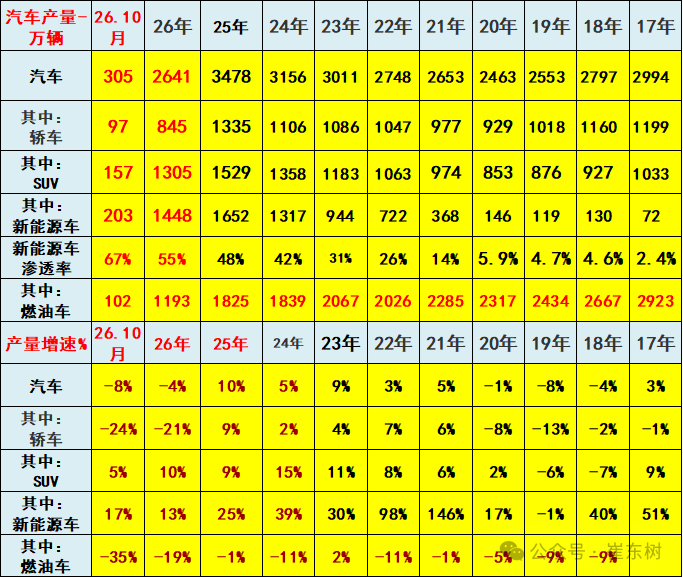
In 2022, automobile production was 27.48 million units, up 3% year on year; new energy vehicle production was 7.22 million, up 98% year on year, penetration rate 26%; fuel vehicle production was 2.06 million units, down 11% year on year.
In 2023, automobile production was 30.11 million units, up 9% year on year; new energy vehicle production was 9.44 million units, up 30% year on year, penetration rate 31%; fuel vehicle production was 20.67 million units, up 2% year on year.
In 2024, automobile production was 31.56 million units, up 5% year on year; new energy vehicle production was 13.17 million units, up 39% year on year, penetration rate 42%; fuel vehicle production was 18.39 million units, down 11% year on year.
In 2025, automobile production was 34.78 million units, up 10% year on year; new energy vehicle production was 16.52 million units, up 25% year on year, penetration rate 48%; fuel vehicle production was 18.25 million units, down 1% year on year.
From January to October 2026, automobile production was 26.41 million units, down 4% year on year; new energy vehicle production was 14.48 million units, up 13% year on year, penetration rate 55%; fuel vehicle production was 11.93 million units, down 19% year on year.
In October 2026, automobile production was 3.05 million units, down 8% year on year; new energy vehicle production was 2.03 million units, up 17% year on year, penetration rate 67%; fuel vehicle production was 1.02 million units, down 35% year on year.
6. Automobile investment continues to decline in 2026
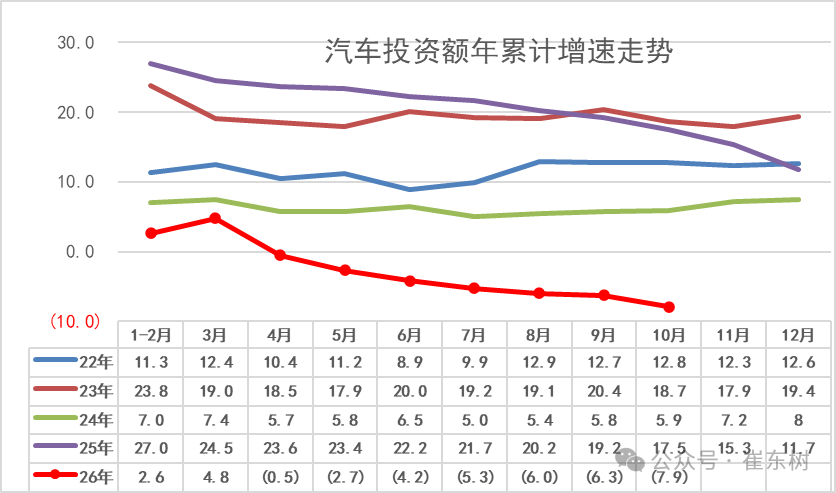
From January to October, the country's fixed asset investment (excluding rural households) was 36482.4 billion yuan, a year-on-year decrease of 8.1%. Investment in the primary sector was 701.8 billion yuan, down 6.1% year on year; investment in the secondary sector was 14233.3 billion yuan, down 3.6%; investment in the tertiary sector was 21547.3 billion yuan, down 10.9%. Industrial investment fell 3.6% year over year. Among them, investment in manufacturing fell 2.9%.
From January to October, private fixed asset investment fell 11.4% year on year. From January to October 2026, fixed asset investment in the automobile industry fell 7.9% year on year. It is still higher than the average of all industries of -8.1%, but higher than the decline in investment in the manufacturing industry.
7. There has been a slight improvement in the real estate consumption squeeze
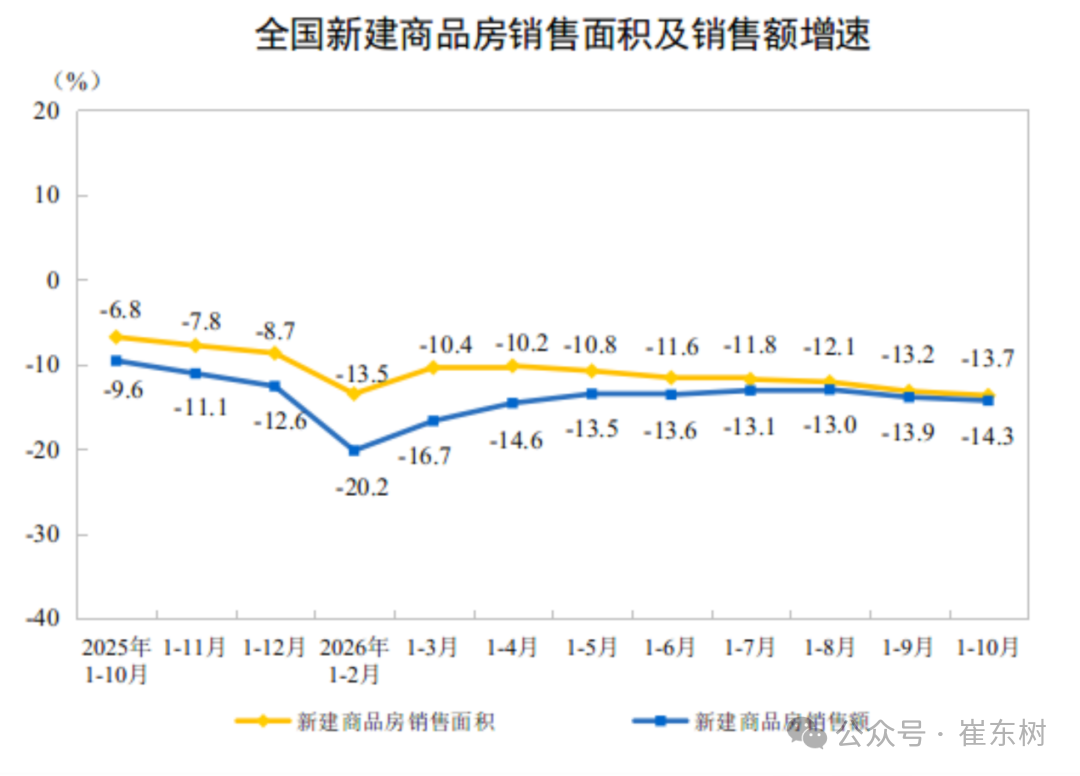
From January to October, the country invested 5721.5 billion yuan in real estate development, a year-on-year decrease of 21.6% (based on a comparable scale, see note 5 for details); of these, residential investment was 4410.2 billion yuan, a decrease of 21.4%. From January to October, the housing construction area of real estate development enterprises was 5681.64 million square meters, a year-on-year decrease of 13.0%.
From January to October, the sales area of newly built commercial housing was 613.58 million square meters, a year-on-year decrease of 13.7%; of these, the residential sales area decreased by 14.2%. Sales of newly built commercial housing amounted to 5855 billion yuan, a decrease of 14.3%; of these, residential sales decreased by 14.1%.
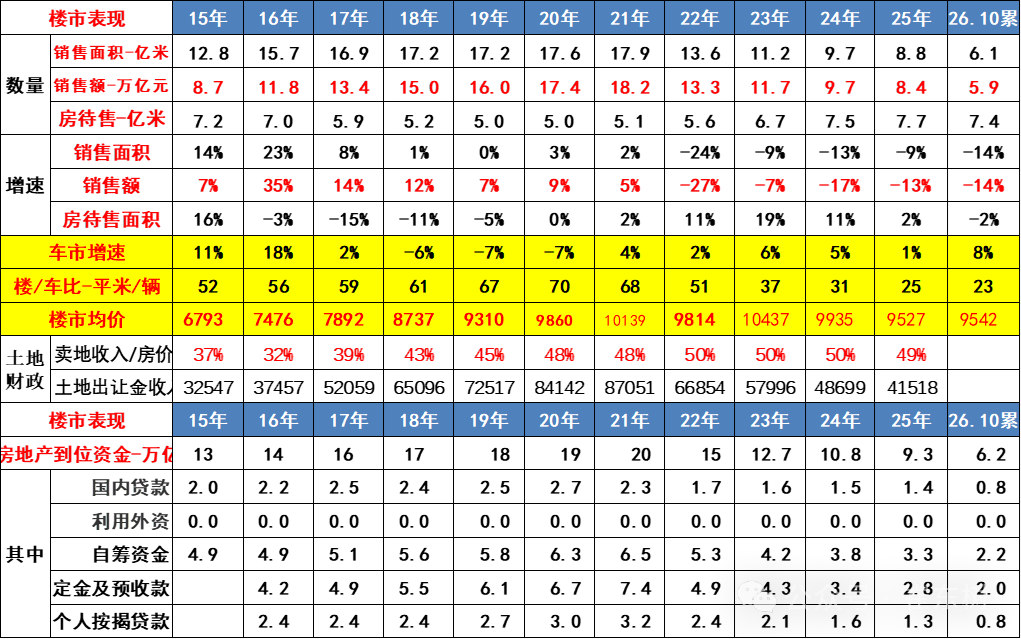
Land concession revenue in 2021 was 8705.1 billion yuan, accounting for 48% of real estate sales; in 2023, land concession revenue was 579.6 billion yuan, accounting for 50% of real estate sales; in 2024, land concession revenue was 4869.9 billion yuan, accounting for 50% of house sales revenue, and real estate contributed greatly to local finance. The 2025 land sales revenue data still accounts for 49% of housing prices.
Currently, the relationship between automobile sales and real estate sales from January to October 2026 is a 23-square-meter house/1 vehicle, and the unreasonable comparison of sales has improved. Although motorhomes have improved compared to the 70-square-meter house/1 car at their peak in 2020, the pressure on debt in the early period and the pressure on the current 10,000 yuan property market are still squeezing consumption, causing demand in the car market to be sluggish due to debt pressure.
The wealth effect of the property market has had a certain effect on boosting demand for high-end cars. The recent decline in residents' property market debt pressure and weakening demand for home purchases have also brought certain potential benefits to improving car market consumption.
8. Vehicle market consumption requires continuous policy support
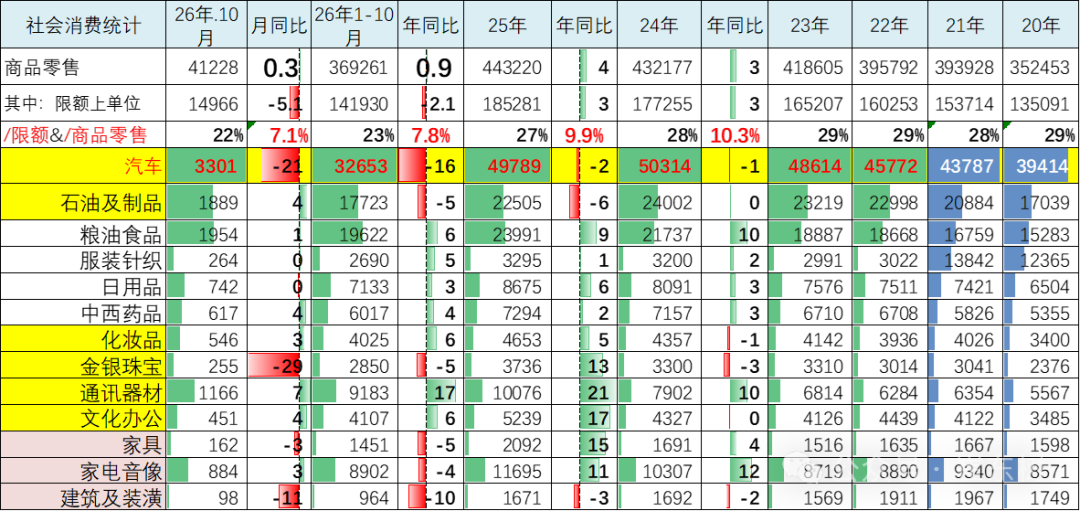
Since the decline in the property market in 2021, automobile consumption has risen from 3.94 trillion yuan in 2020 to 4.98 trillion yuan in 2025, breaking away from the passive situation of hovering around 3.9 trillion yuan for 3 consecutive years in 2018-2020. As the decline in real estate reduces consumers' expectations of buying a house, unleashes consumption potential, favors consumption, and investment in buying a house squeezes the consumption problem. In 2025, total retail sales of consumer goods amounted to 5012.2 billion yuan, an increase of 3.7% over the previous year. Among them, automobile consumption was 4978.9 billion yuan, a year-on-year decrease of 2%; retail sales of consumer goods other than automobiles were 45141.3 billion yuan, an increase of 4.4%. The cost of living has risen sharply, consumption of clothing and food is growing too fast, and consumption of car purchases is being seriously squeezed by food and clothing. Consumption in the car market fell 15% from January to October 2026. Currently, the problem of poor consumption still needs to be improved.
In October '26, total retail sales of consumer goods amounted to 4646.3 billion yuan, an increase of 0.4% over the previous year. Among them, automobile consumption was 33.1 billion yuan, a year-on-year decrease of 21%; retail sales of consumer goods other than automobiles were 4316.2 billion yuan, an increase of 2.5%. From January to October, total retail sales of consumer goods amounted to 41646.4 billion yuan, an increase of 1.0% over the previous year. Among them, automobile consumption was 3265.3 billion yuan, a year-on-year decrease of 16%; retail sales of consumer goods other than automobiles amounted to 38381.1 billion yuan, an increase of 2.8%.
Automobile consumption in 2026 presents a complex situation of “policy continuation, market fragmentation, and pressure on demand”. The trade-in policy continues to gain strength, but due to factors such as the accelerated contraction of fuel vehicles, price wars diluting consumer confidence, and the downturn in the low-end market, the total retail volume is still declining. The steady increase in consumption of petroleum products reflects the fact that residents' demand for travel is still rigid, and weak automobile consumption is more indicative of a marginal weakening of the will to spend on durable goods and disposable income.