


EN
How Dublin Data Center Expansion At Johnson Controls (JCI) Has Changed Its Investment Story
- Armada and Johnson Controls International have started production at Galleon Forge Two in Dublin, building Leviathan modular data centers in Europe using Johnson Controls thermal management technology and manufacturing capacity.
- The Dublin facility embeds Johnson Controls more deeply into sovereign AI infrastructure, tying its cooling portfolio directly to multi megawatt data center projects owned and controlled by European customers.
- We will now look at how Johnson Controls’ expanded role in European sovereign AI data centers could influence its wider investment narrative.
Scan 53 AI infrastructure stocks that, like Johnson Controls International, are connected to the build out of high density AI data centers and critical cooling and power technology.
Johnson Controls International Investment Narrative Recap
For an investor to back Johnson Controls International, the belief has to be that its building systems heritage can support a long runway in data center and AI related infrastructure, while margins keep tracking the analyst consensus narrative on Simply Wall St. The Galleon Forge Two ramp in Dublin ties that thesis more closely to sovereign AI cooling projects in Europe, which may matter for near term order momentum in high density data centers.
The biggest near term catalyst still looks operational. Investors are watching whether the newer organizational model and Lean focus convert a US$21b style backlog into higher margin service and thermal content. The key risk is that complexity in product lines and ongoing weakness in security and fire offsets data center strength, particularly given that debt levels and valuation are already highlighted as pressure points.
The Galleon Forge Two production start is the headline here. It embeds Johnson Controls International equipment, controls and zero water thermal technology directly into Armada Leviathan builds for European AI customers. That tightens the link between JCI’s cooling portfolio and multi megawatt projects, which connects directly to the data center mix shift that analysts describe as central to earnings quality.
Executive changes around the same time also matter for execution. The appointment of a new Chief Information Officer with enterprise AI and data experience gives JCI an internal owner for digital tools, cybersecurity and AI strategy, which relates to how efficiently these large data center contracts are delivered and serviced. The new Chief Legal Officer adds governance and risk experience, which is relevant if valuation expectations remain elevated and any operational stumble tests investor confidence.
What The Johnson Controls International Forecasts Assume
Johnson Controls International's narrative projects US$33.1b revenue and US$4.9b earnings by 2029. This rests on analysts building in 8.9% yearly revenue growth and an earnings increase of US$2b from US$2.9b today.
Uncover why Johnson Controls International's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
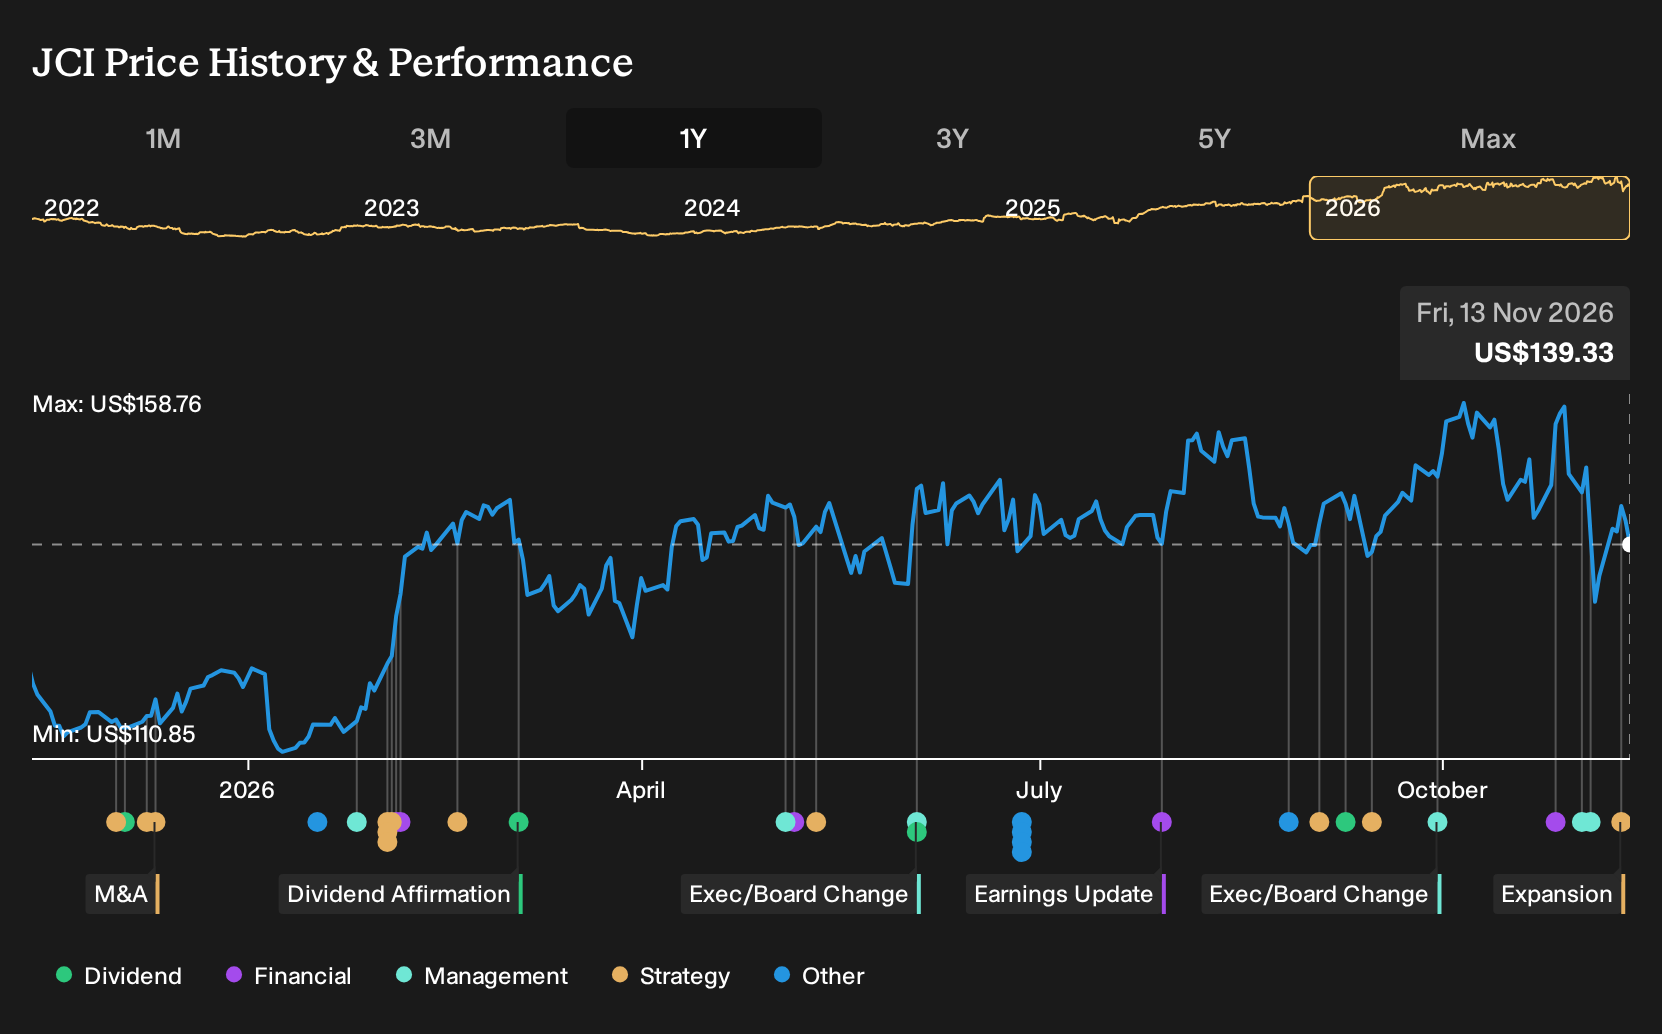
Exploring Other Perspectives
One alternate view puts more weight on Johnson Controls International stumbling over data center project delays rather than riding them. That bearish group had penciled in about US$31.0b of revenue and US$4.6b of earnings by 2029, which is lower than consensus. Those estimates came before this Galleon Forge Two news, so use them as a starting point to compare narratives, not the final word.
Explore 3 other Johnson Controls International fair value estimates, including one that suggests it could be worth just $173.45!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis.
- A great starting point for your Johnson Controls International research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Johnson Controls International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Johnson Controls International's overall financial health at a glance.
Looking for more investment ideas beyond Johnson Controls International?
Once you have formed a view on Johnson Controls International, it can help to compare it with other opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- If you care most about stability and capital preservation, start with a curated set of 29 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Income focused investors can scan a hand picked group of 6 dividend fortresses that pair higher yields with supporting fundamentals.
- For those hunting for future leaders before they are widely followed, there is a focused collection of 19 high quality undiscovered gems with solid underlying metrics and room for the story to develop.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com