


EN
Did Return To Losses Just Shift Zillow's (ZG) Investment Narrative?
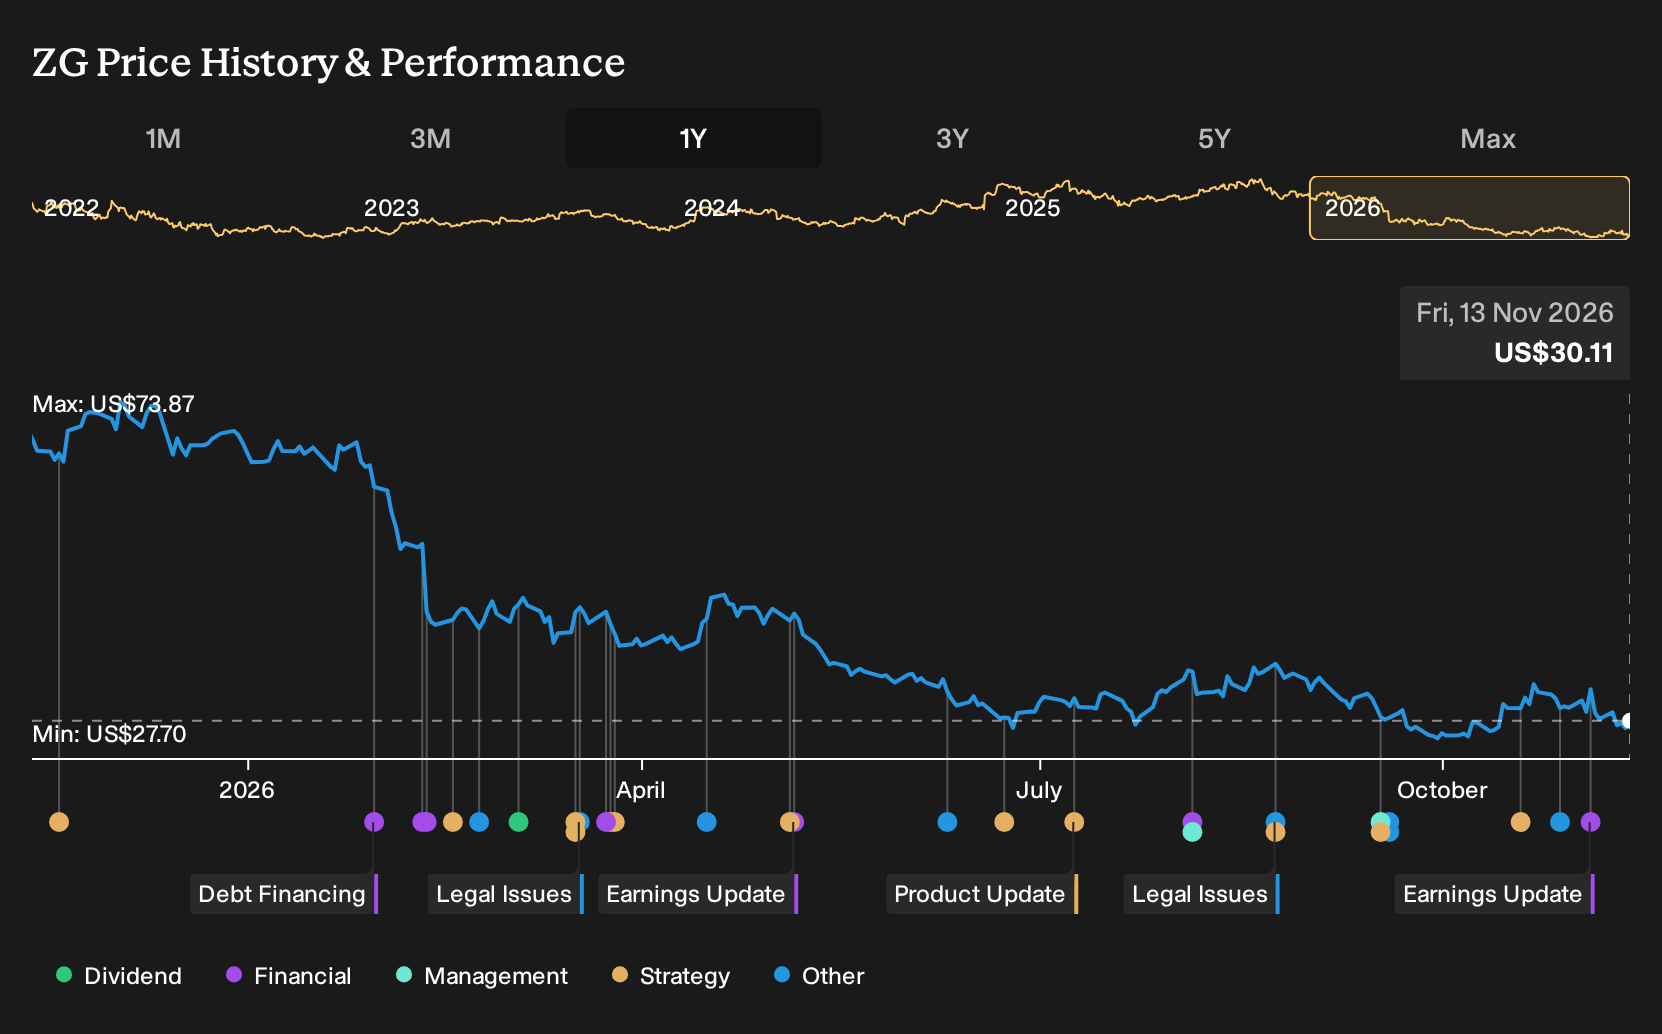
- Zillow Group reported third quarter 2026 revenue of US$724 million and sales of US$709 million, but moved from a US$10 million profit a year earlier to a net loss of US$158 million, with basic and diluted loss per share of US$0.70 from continuing operations.
- For the first nine months of 2026, Zillow Group recorded higher sales and revenue than the prior year but swung from a US$20 million profit to a US$116 million loss, highlighting pressure on costs and profitability even as the top line expanded.
- Next, the focus shifts to how Zillow Group's higher revenue but return to quarterly losses may influence the longer term investment narrative.
Scan beyond Zillow Group and explore other real estate and housing related stocks with stronger fundamentals using our curated list of list of solid balance sheet and fundamentals (24 results).
Zillow Group Investment Narrative Recap
For an investor to stay with Zillow Group, the core belief is that its real estate platforms can keep deepening user engagement and monetizing traffic across Residential, Rentals and Mortgages. The analyst consensus Narrative on Simply Wall St leans on that digital shift, yet the latest quarter shows rising revenue alongside fresh losses. That mix keeps attention squarely on execution in core advertising and newer software driven services.
The most immediate swing factor is whether management can contain costs while still investing in growth tools like CRM, rentals platforms and end to end transaction products. The largest current risk is that persistently weak transaction volumes or commission pressure restrict Premier Agent and related advertising income, which would make the recent step back into losses more concerning for near term margin progress.
The third quarter and nine month earnings update is the key operational signal here. Zillow Group lifted sales and revenue versus a year earlier, though it shifted from profit to a net loss for both the quarter and year to date. That pattern puts more scrutiny on how quickly newer offerings such as rentals and software can scale without further straining the income statement.
For catalysts, the existing analyst consensus Narrative on Simply Wall St highlights products like Zillow 360, Enhanced Markets and rentals partnerships as ways to diversify beyond traditional agent advertising. In light of the latest results, those initiatives matter more because they aim to add higher margin, recurring style revenue. Execution risk remains, especially given prior missteps in expansion, so many shareholders will likely focus on whether future updates show cleaner progress from revenue growth to consistent earnings.
Zillow Group's narrative projects US$3.9b revenue and US$522.8 million earnings by 2029. That profile assumes 11.9% yearly revenue growth and an earnings increase of about US$467.8 million from US$55.0 million today.
Uncover why Zillow Group's fair value signals a 51% potential upside to its current price. This may represent a discount that could close more quickly than you expect.
Exploring Other Perspectives
Some of the most optimistic Zillow Group analysts framed the Preferred agent shift as the real prize, expecting about 13.5% annual revenue growth and US$744.5 million in earnings by 2029, versus the consensus US$522.8 million. After this latest move back into quarterly losses, you can now weigh whether those pre news forecasts still feel realistic and explore how views might adjust.
Explore 2 other Zillow Group fair value estimates, including one that suggests up to 186% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Zillow Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Zillow Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zillow Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Zillow Group?
Once you have a view on Zillow Group, it can help to widen the lens and compare it with other businesses that line up with the kind of risk, income or value profile you want in your portfolio. The Simply Wall St Screener can surface ideas that match those preferences in a few clicks.
- If capital preservation comes first for you, start with companies that have stronger financial footing by reviewing our 29 resilient stocks with low risk scores.
- For investors who want value opportunities supported by fundamentals, scan through the 35 high quality undervalued stocks and see which stocks match your checklist.
- If you prefer businesses with cleaner balance sheets and steadier fundamentals, filter your universe with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com