


EN
Brembo (BIT:BRE) Lifts Nine Month Earnings, Is The Stock Fully Priced?
What Brembo’s Latest Earnings Signal For Shareholders
Brembo (BIT:BRE) just updated the market with nine month earnings to 30 September 2026, reporting higher sales and net income compared with the same period a year earlier.
The business posted €2,881.96m in revenue and €175.3m in profit, with basic and diluted earnings per share from continuing operations at €0.55 versus €0.51 previously.
Recent earnings have come alongside a share price of €10.22, with a 7 day share price return of 3.23% but a 30 day share price return that fell 3.31%. Meanwhile, the 1 year total shareholder return of 12.47% points to momentum that has been building over a longer stretch.
Scan how Brembo’s earnings shift compares with peers by reviewing a curated set of auto and industrial suppliers in the list of solid balance sheet and fundamentals (199 results).
Brembo looks like a solid operator with rising sales and profit, yet the share price has drifted over the past month. Is the current valuation giving you a fair entry, or is it already baking in that strength?
Price-to-Earnings of 14.7x: Is It Justified For Brembo?
Brembo trades on a P/E of 14.7x, which puts the current €10.22 share price in an interesting spot compared with both local and sector peers.
The P/E ratio compares what investors are paying today for each euro of earnings. For a manufacturer of braking systems and related components like Brembo, this metric often reflects how confident the market is in the durability of profits through the cycle.
Against its immediate peer set, the stock is described as good value because its 14.7x P/E sits well below the 34x average. That gap points to a market that is assigning a lower price tag to Brembo’s earnings than to those of similar auto component groups. Relative to the wider European Auto Components industry though, which sits at 14.4x, the same 14.7x is described as slightly expensive. The estimated fair P/E of 19.8x is materially higher than both, which signals a level the multiple could move towards if sentiment and fundamentals stay aligned with that fair ratio view.
Explore the SWS fair ratio for Brembo.
Result: Preferred multiple of Price-to-Earnings of 14.7x (ABOUT RIGHT)
Still, Brembo relies on cyclical auto demand and earnings expectations, so any slowdown in vehicle production or shift in analyst sentiment could quickly challenge today’s pricing.
Find out about the key risks to this Brembo narrative.
Another View On Brembo’s Valuation
There is a small twist when you switch from the P/E discussion to the SWS DCF model. At €10.22, Brembo trades slightly above an estimated future cash flow value of €10.04, which points to a modest premium. Is that narrow gap enough to change how you frame the opportunity?
Look into how the SWS DCF model arrives at its fair value.
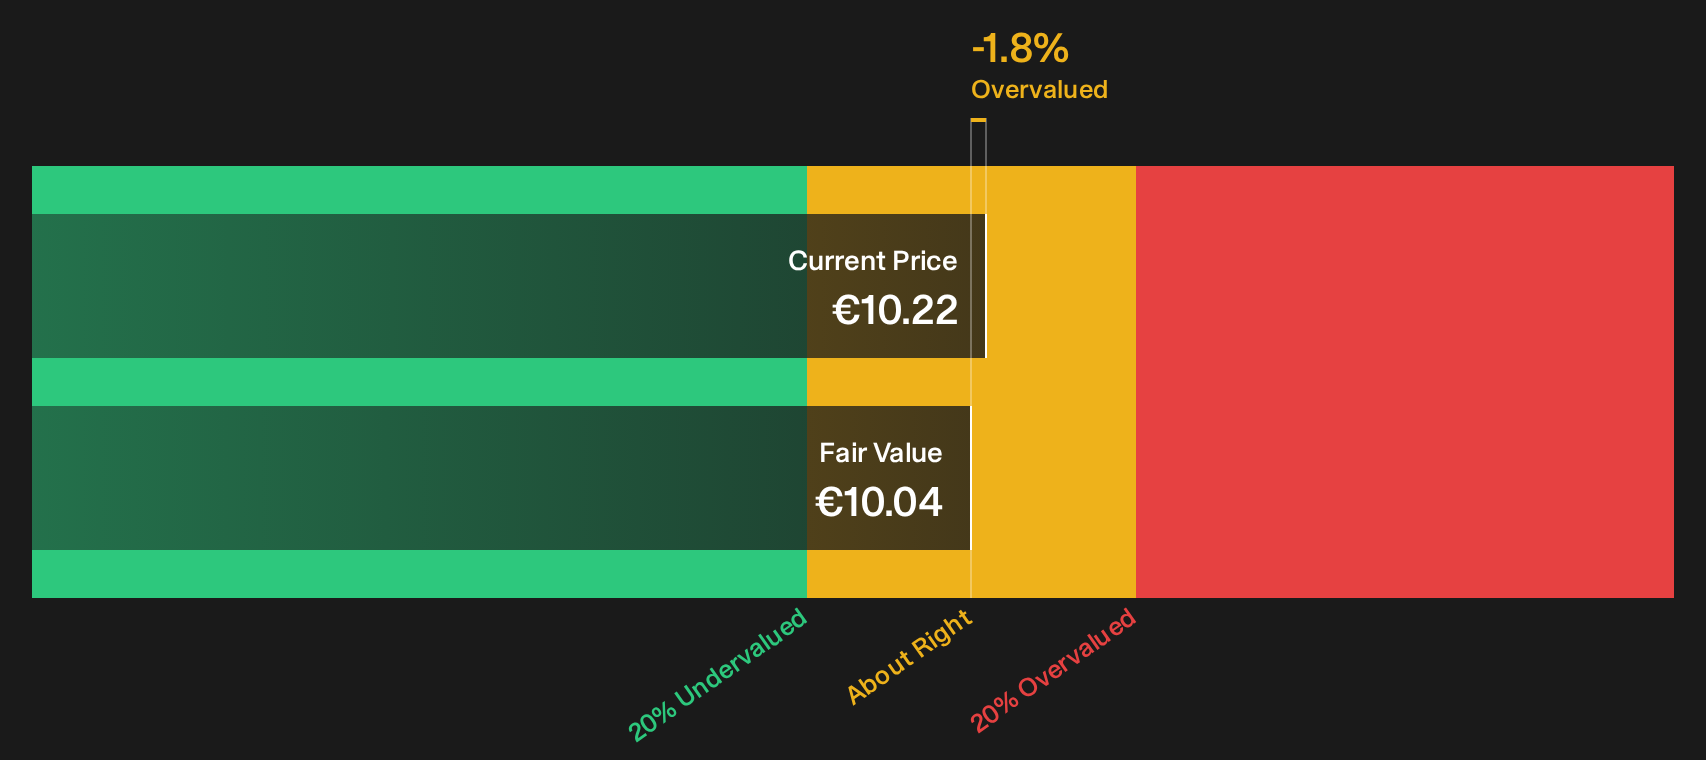
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brembo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 201 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Brembo is mixed, with solid recent numbers but a valuation that invites debate. Act while the data is fresh and form your own take using the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Brembo?
If Brembo has you thinking harder about valuation and quality, do not stop at one opportunity. Broaden your watchlist before the next move passes you by.
- Target better value by scanning companies that combine quality fundamentals with attractive pricing in the 201 high quality undervalued stocks.
- Strengthen your income stream by reviewing consistently high yield payers featured in the 224 dividend fortresses.
- Dial down portfolio stress by focusing on financially resilient businesses highlighted in the 206 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com