


EN
Viavi Solutions (VIAV) Returns To Profit With Fresh Guidance, Is The Stock Too Pricey?
Viavi Solutions (VIAV) just put fresh numbers on the table that matter for shareholders. First quarter sales reached US$469.3 million with net income of US$76 million, and management also issued revenue guidance for the upcoming quarter.
The share price reaction has been cool in the short term, with Viavi Solutions down 5.6% on a 1 day basis and 7.97% over 30 days. However, the year to date share price return of 69.26% and 1 year total shareholder return of 83.95% point to strong underlying momentum. Longer term investors have seen very large gains, with the 3 year total shareholder return around 3x and the 5 year total shareholder return up 96.8%. The fresh earnings beat, revenue guidance and expanded buyback help explain why sentiment has shifted this far despite recent profit taking.
Scan how Viavi Solutions compares to a curated 35 high quality undervalued stocks that combines strong fundamentals with what our models flag as attractive pricing.
After a near 70% run in 2026 and a sharp pullback on the latest report, Viavi Solutions now poses a simple question: Is this the moment to commit fresh capital, or does patience offer a better entry?
Most Popular Narrative: 47% Undervalued
On the analyst consensus Narrative on Simply Wall St, Viavi Solutions screens as significantly undervalued, with a fair value of $58.14 against a last close of $30.72, which puts the current debate around the stock into much sharper focus.
Viavi is experiencing robust and sustained demand across the data center ecosystem, with customers updating optical connectivity to 400G, 800G, and now 1.6T, enabling multi-year upgrade cycles and expanding its total addressable market. This is expected to support structural revenue trends through 2026 and beyond. The rapid proliferation of fiber broadband deployments for both hyperscale data interconnect and traditional carrier networks, coupled with aggressive announced spending by North American fiber operators, points to a significant near-term acceleration in fiber-related test equipment orders, which in turn is anticipated to support higher future revenues.
See why 16 investors see Viavi Solutions as 47% undervalued.
Result: Fair Value of $58.14 (UNDERVALUED)
Still, several pressure points could derail that upbeat Viavi Solutions narrative, including prolonged weakness in wireless test demand and any stumble in integrating recent acquisitions funded with new debt.
Find out about the key risks to this Viavi Solutions narrative.
Another View: What Viavi Solutions’ P/E Is Saying
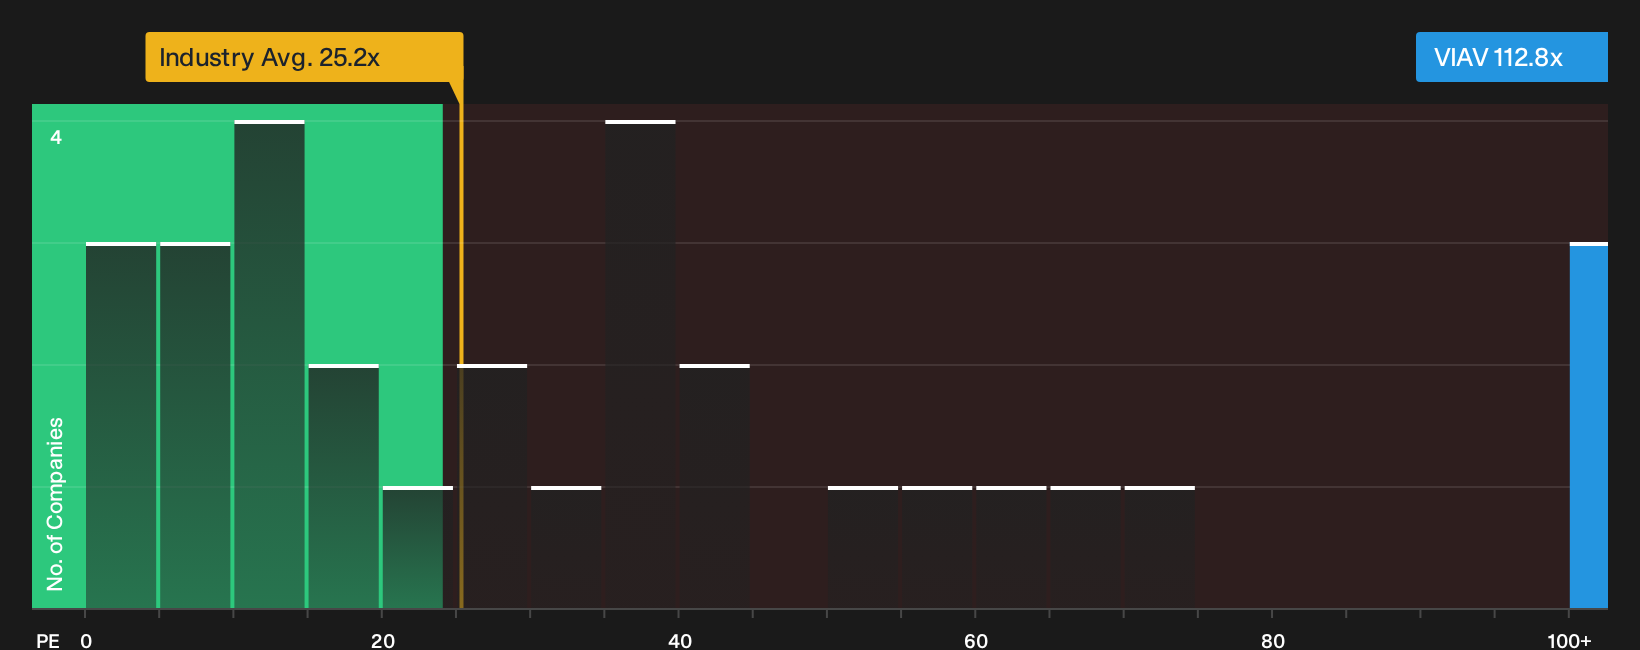
Those DCF and analyst fair value figures paint Viavi Solutions as undervalued, yet the P/E ratio tells a very different story. The stock trades on about 112.8x earnings versus 41.8x for peers, 25.2x for the broader US Communications group, and a fair ratio closer to 47.1x.
That gap suggests investors are already paying a steep premium today, which can amplify downside risk if high growth and margin expectations slip. It raises a simple question for you as a shareholder or prospective buyer: Is this premium a risk you are comfortable carrying at this stage of the story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Viavi Solutions is split, with enthusiasm for the upside sitting right beside concern about what could go wrong next. Act while the details are fresh and decide where you stand by weighing up the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Viavi Solutions?
If Viavi Solutions has sharpened your thinking, do not stop here. The screener can surface other opportunities that match your risk appetite and return goals.
- Target resilient opportunities by focusing on companies with strong financial durability using the 29 resilient stocks with low risk scores.
- Spot potential value candidates that pair quality fundamentals with appealing pricing by filtering through the 19 high quality undiscovered gems.
- Prioritise financial strength and liquidity by zeroing in on businesses featured in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com