


EN
Learn Why The Bull Case For Live Nation Entertainment Stock Could Change Following Earnings Growth
- Live Nation Entertainment reported third quarter 2026 sales of US$10,105.04 million and net income of US$447.84 million, with basic earnings per share from continuing operations of US$1.74.
- The sharp jump in quarterly earnings per share from continuing operations, from US$0.74 to US$1.74 year on year, highlights how Live Nation Entertainment converted strong event activity into higher profitability per share.
- We will look at how Live Nation Entertainment's jump in third quarter earnings per share has influenced the longer term investment narrative.
Scan beyond Live Nation Entertainment and see how other event driven businesses are priced by reviewing the hand picked 19 high quality undiscovered gems that could be riding similar demand for live experiences.
Live Nation Entertainment Investment Narrative Recap
Owning Live Nation Entertainment means believing that live events can support both high volumes and healthy profitability over time. The analyst consensus Narrative on Simply Wall St expects venue expansion and Ticketmaster scale to matter most. The latest quarter showed strong third quarter earnings per share despite mixed nine month net income, so the near term story still leans on execution rather than a reset in direction.
Right now, the key short term catalyst is how effectively Live Nation Entertainment converts record fan activity into cash generation as new venues and technology investments come on line. The biggest risk remains regulatory and antitrust pressure around Ticketmaster, which could limit pricing power or contract terms if remedies expand.
Among recent information, the extended consent decree and related Ticketmaster remedies sit closest to this earnings release, even though they are legal rather than financial announcements. Those measures require more open ticketing contracts and support for rival distributors, which could matter more as Live Nation Entertainment tries to grow fee bearing tickets and monetize expanding capacity.
This legal backdrop means the strong third quarter results arrive while core ticketing economics face scrutiny. Any future remedies trial outcomes or appeals process introduce uncertainty over potential changes to venue, ticketing, or sponsorship structures, so investors watching catalysts will likely track regulatory milestones alongside updates on new Venue Nation projects and international expansion.
Live Nation Entertainment's narrative projects US$34.4b revenue and US$996.6m earnings by 2029. This assumes 9.4% yearly revenue growth and requires a US$1.25b earnings improvement from a loss of US$258.0m today.
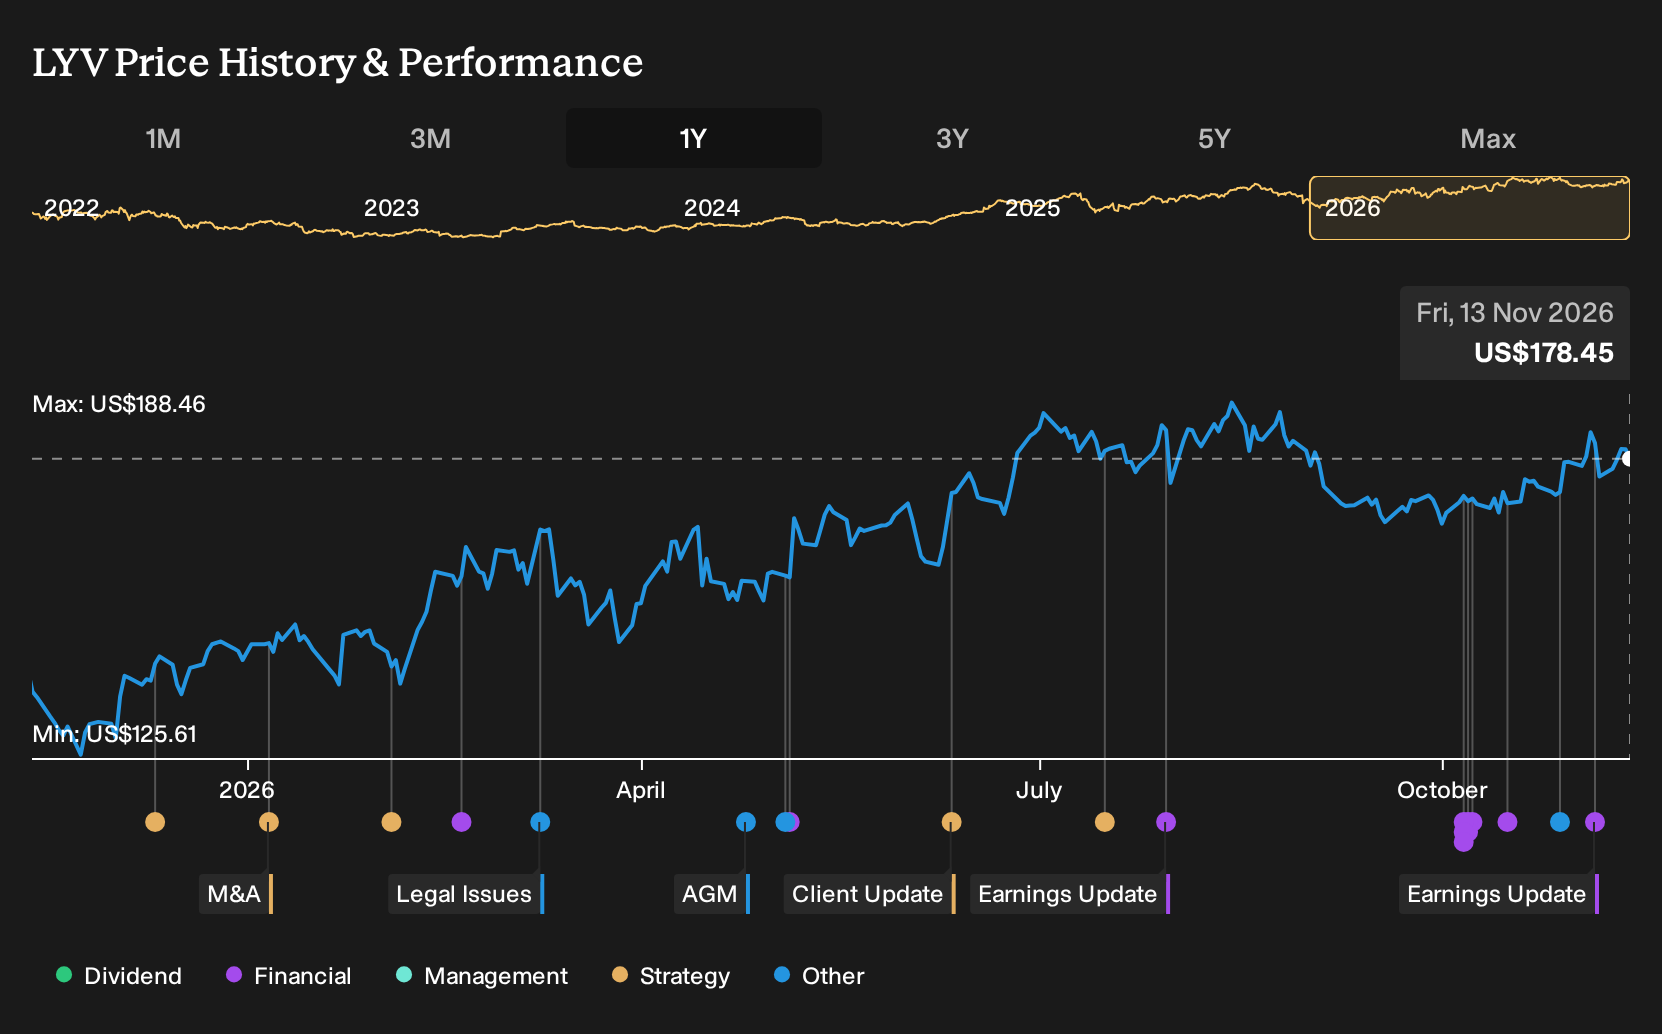
Uncover why Live Nation Entertainment's fair value indicates a 13% potential upside to its current price, a discount that could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$196 and US$202 per share, so retail views of Live Nation Entertainment currently show little dispersion. Those opinions were formed before the latest US$10.1b quarter and regulatory overhang, so treat them as a starting point. Explore multiple viewpoints.
Explore another Live Nation Entertainment fair value estimate, including one that suggests as much as 13% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Live Nation Entertainment research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Live Nation Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Live Nation Entertainment's overall financial profile at a glance.
Looking for more investment ideas beyond Live Nation Entertainment?
If Live Nation Entertainment has you thinking about where to deploy your next dollar, it can help to compare it with a wider field of potential opportunities that have different risk and income profiles.
- If you want potential bargains with quality fundamentals, start by checking companies flagged as undervalued through the 34 high quality undervalued stocks. This tool filters for strong cash generation and sensible balance sheets.
- For investors who care most about resilience and capital preservation, consider reviewing the 29 resilient stocks with low risk scores. It highlights businesses with lower overall risk scores and steadier financial profiles.
- If a solid financial base matters more to you than short term excitement, scan the list of solid balance sheet and fundamentals (24 results) to focus on companies with stronger balance sheets and underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com