


EN
Viper Energy (VNOM) After Strong Q3 And Higher Dividend Looks Undervalued In This Narrative
Viper Energy (VNOM) just released third quarter numbers that turned last year’s loss into a profit, raised full-year oil production guidance, and confirmed a higher cash dividend for shareholders.
Viper Energy’s latest earnings, guidance upgrade and higher dividend land against a mixed trading backdrop. The share price is up 3.57% over the last day and 4.23% across seven days, yet down 5.95% over 30 days and 1.65% over 90 days. Year to date the share price return is 9.18%, and the 1 year and 3 year total shareholder returns of 17.77% and 64.84% suggest longer term holders have still seen momentum build despite recent volatility.
Scan how Viper Energy fits alongside other income-focused plays by comparing it with our curated list of 6 dividend fortresses that prioritize reliable payouts and robust cash generation.
Viper Energy’s earnings rebound and higher dividend point to a business delivering stronger cash flows, yet the patchy share price suggests sentiment is still catching up. How does that mix show up in the current valuation?
Most Popular Narrative: 24% Undervalued
On the narrative view, Viper Energy’s fair value sits at $56.00 against the latest $42.34 close, and according to John_Eric, an investor in the Simply Wall St Community who built the valuation, the gap rests on what you are really buying with each share.
Viper is not merely a stream of today's royalty checks. It is ownership of a large Permian mineral estate through which thousands of existing wells already produce, thousands more are being developed or contemplated, and future operators can continue turning buried geology into royalty income largely with somebody else's capital.
See why 32 investors see Viper Energy as 24% undervalued.
Across that framework, the narrative anchors on a $56.00 fair value that sits between a conservative $44 scenario and a more optimistic $68 case. A 7.236% discount rate is used to reflect the riskiness of those future cash flows.
The conclusion is simple for investors comparing it with the current quote. The latest $42.34 price is below the $56.00 fair value in the narrative, which points to a material valuation gap even after accounting for the risks around commodity prices, drilling decisions, and undeveloped mineral inventory.
Result: Fair Value of $56.00 (UNDERVALUED)
Still, this story can break if drilling activity across Viper Energy’s acreage slows sharply, or if related-party deals with Diamondback start to look misaligned.
Find out about the key risks to this Viper Energy narrative.
Another View: Viper Energy Looks Expensive On Earnings
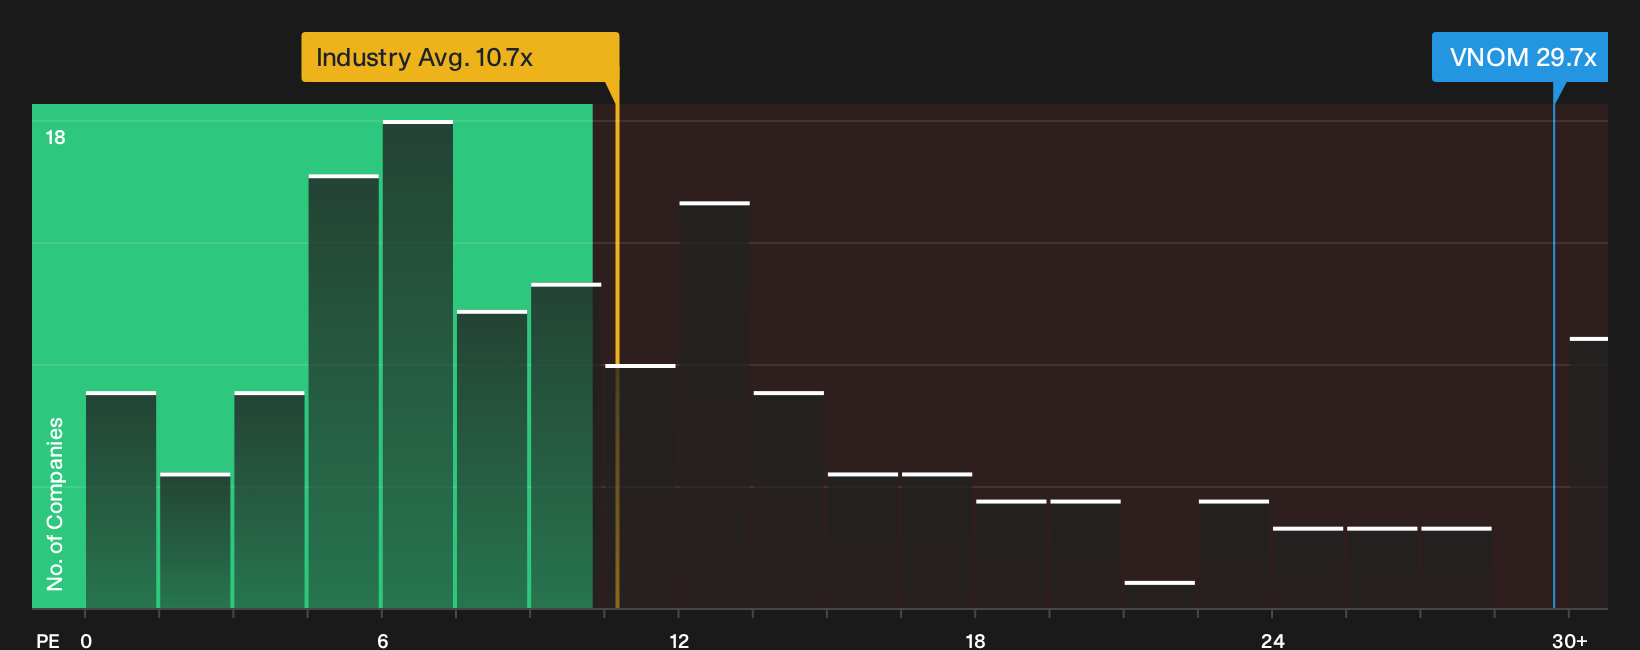
Take the narrative fair value of $56.00 and set it beside the earnings multiple. Viper Energy trades on a P/E of 29.7x, which is far richer than the US Oil and Gas industry at 10.8x, the peer average at 15.5x, and even its own fair ratio of 21x. That richer pricing can mean investors are already paying up for future progress, so how much room is left if expectations slip?
To see how that richer earnings multiple stacks up against the underlying numbers in more detail, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Viper Energy can be confusing, so move quickly to review the full picture and then decide where you stand on its outlook. A fast way to pressure test both sides of the story is to weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Viper Energy?
If Viper Energy has your attention, do not stop here. Broaden your watchlist with fresh income and value angles that might better match your goals.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (24 results) that surfaces companies with financial strength front and center.
- Hunt for potential mispricings with a 34 high quality undervalued stocks that highlights businesses trading below what their fundamentals may justify.
- Strengthen your income stream using a 6 dividend fortresses focused on companies that pair higher yields with durable cash support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com