


EN
Linamar (TSX:LNR) On Earnings, Buybacks And 2026 Guidance Looks Cheap Enough To Question
What Linamar’s latest earnings and guidance tell you
Linamar (TSX:LNR) just packed a lot into one day. Fresh third quarter numbers, a reaffirmed 2026 outlook, a new buyback plan, and a quarterly dividend all landed at once.
Over the last few months, Linamar’s share price has given back some ground, with a 30-day share price return down 5.62% and a 90-day share price return down 19.13%. However, the 1-year total shareholder return is 10.57% and the 3-year total shareholder return is 52.13%, which points to longer term momentum that contrasts with the recent pullback around these earnings, guidance, dividend and buyback headlines.
Compare Linamar’s buyback and dividend story with peers by scanning our hand picked list of 6 high quality undervalued stocks.
Linamar shares have slid into this earnings release even as management commits cash to buybacks and dividends. Are investors being paid for fresh upside, or mostly crystallizing gains already on the table?
Preferred P/E of 7.6x: Is it justified?
On simple headline numbers, Linamar looks cheap. The stock closed at CA$86.16 while it trades on a P/E of 7.6x against a peer average of 13.8x.
The P/E ratio links the current share price to earnings per share. For a manufacturer like Linamar with established operations in Mobility and Industrial, it is a quick way to see how much investors are paying for each dollar of profit.
Here, the gap is wide. Linamar is described as good value both versus the North American Auto Components industry P/E of 13.9x and versus peers at 13.8x. This points to the market assigning a lower earnings multiple despite high quality earnings and earnings growth over the past year.
Compared with its own cash flow value, the discount looks even steeper. Linamar at CA$86.16 is flagged as trading 54.6% below an SWS DCF model estimate of future cash flow value of CA$189.75. This is a level that the multiple could move towards if sentiment and assumptions align over time.
See what the numbers say about this price — find out in our valuation breakdown..
Result: Price-to-earnings of 7.6x (UNDERVALUED)
Still, the Linamar story can be knocked off course if global auto demand softens or if higher input costs squeeze margins in Mobility and Industrial.
Find out about the key risks to this Linamar narrative.
Another view on Linamar’s value
DCF math paints a different picture compared with the simple P/E gap. Linamar at CA$86.16 is described as trading 54.6% below an SWS DCF model estimate of future cash flow value of CA$189.75, which raises a key question for you as an investor: Is the discount signalling caution or patience?
Look into how the SWS DCF model arrives at its fair value.
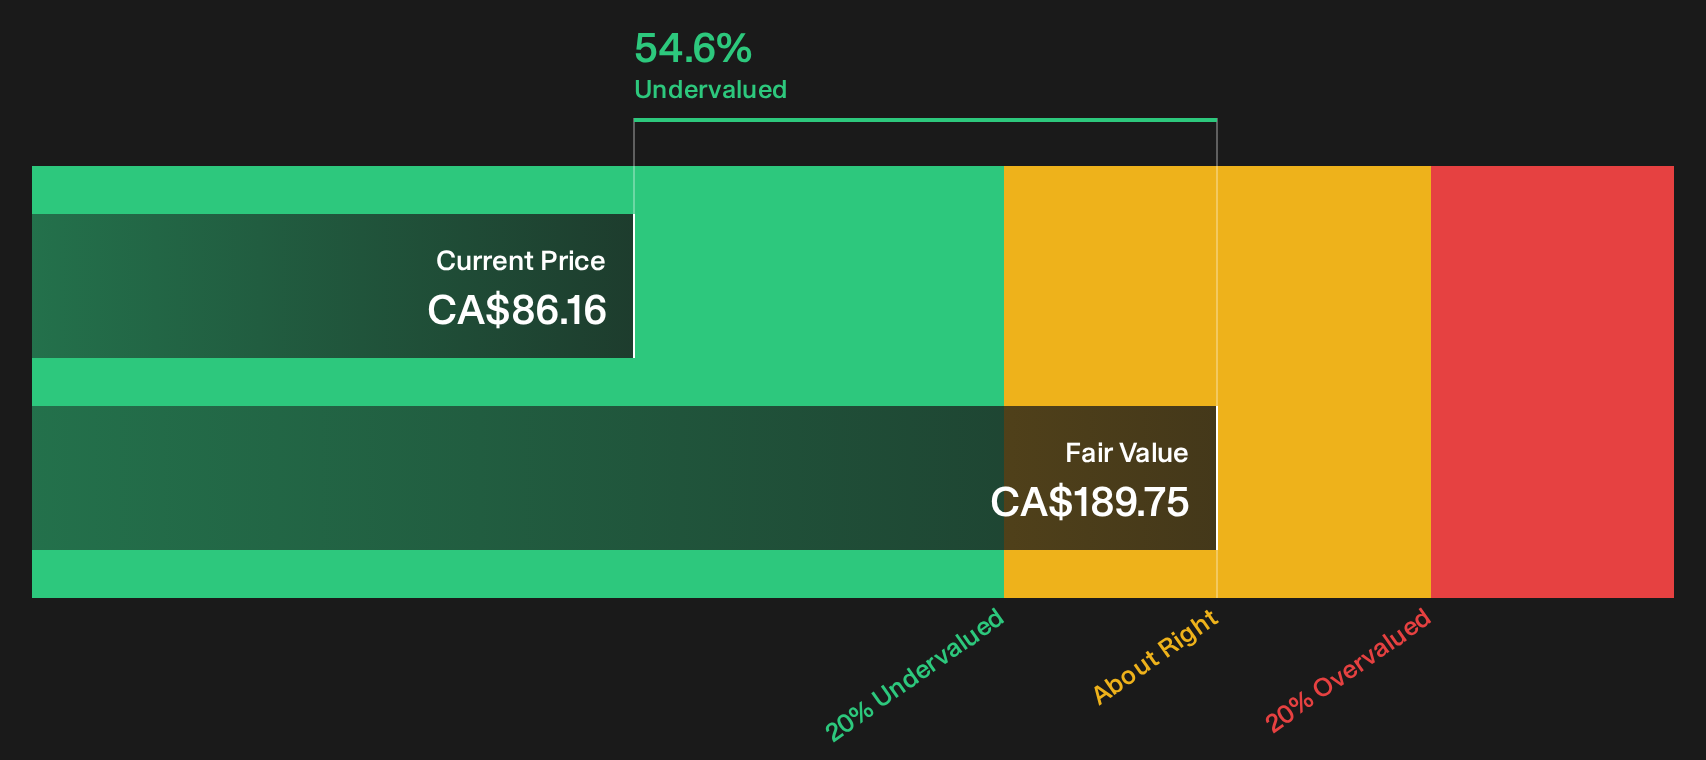
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Linamar for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the Linamar story feels mixed to you, that is the point. The data carries both concern and optimism, so it is worth reviewing the details and weighing the 4 key rewards and 1 important warning sign.
Looking for more Linamar investment ideas?
If Linamar has your attention, do not stop here. Fresh ideas often come from scanning high quality watchlists that spotlight different strengths and risk profiles.
Expand your opportunity set by using the Simply Wall Street Screener to uncover focused lists built around specific qualities and financial profiles across the market.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (6 results).
- Hunt for pricing gaps where quality may meet a lower entry point through the 6 high quality undervalued stocks.
- Spot future leaders before they are widely followed by checking the 10 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com