


EN
How Strong Earnings At SECOM (TSE:9735) Has Changed Its Investment Story
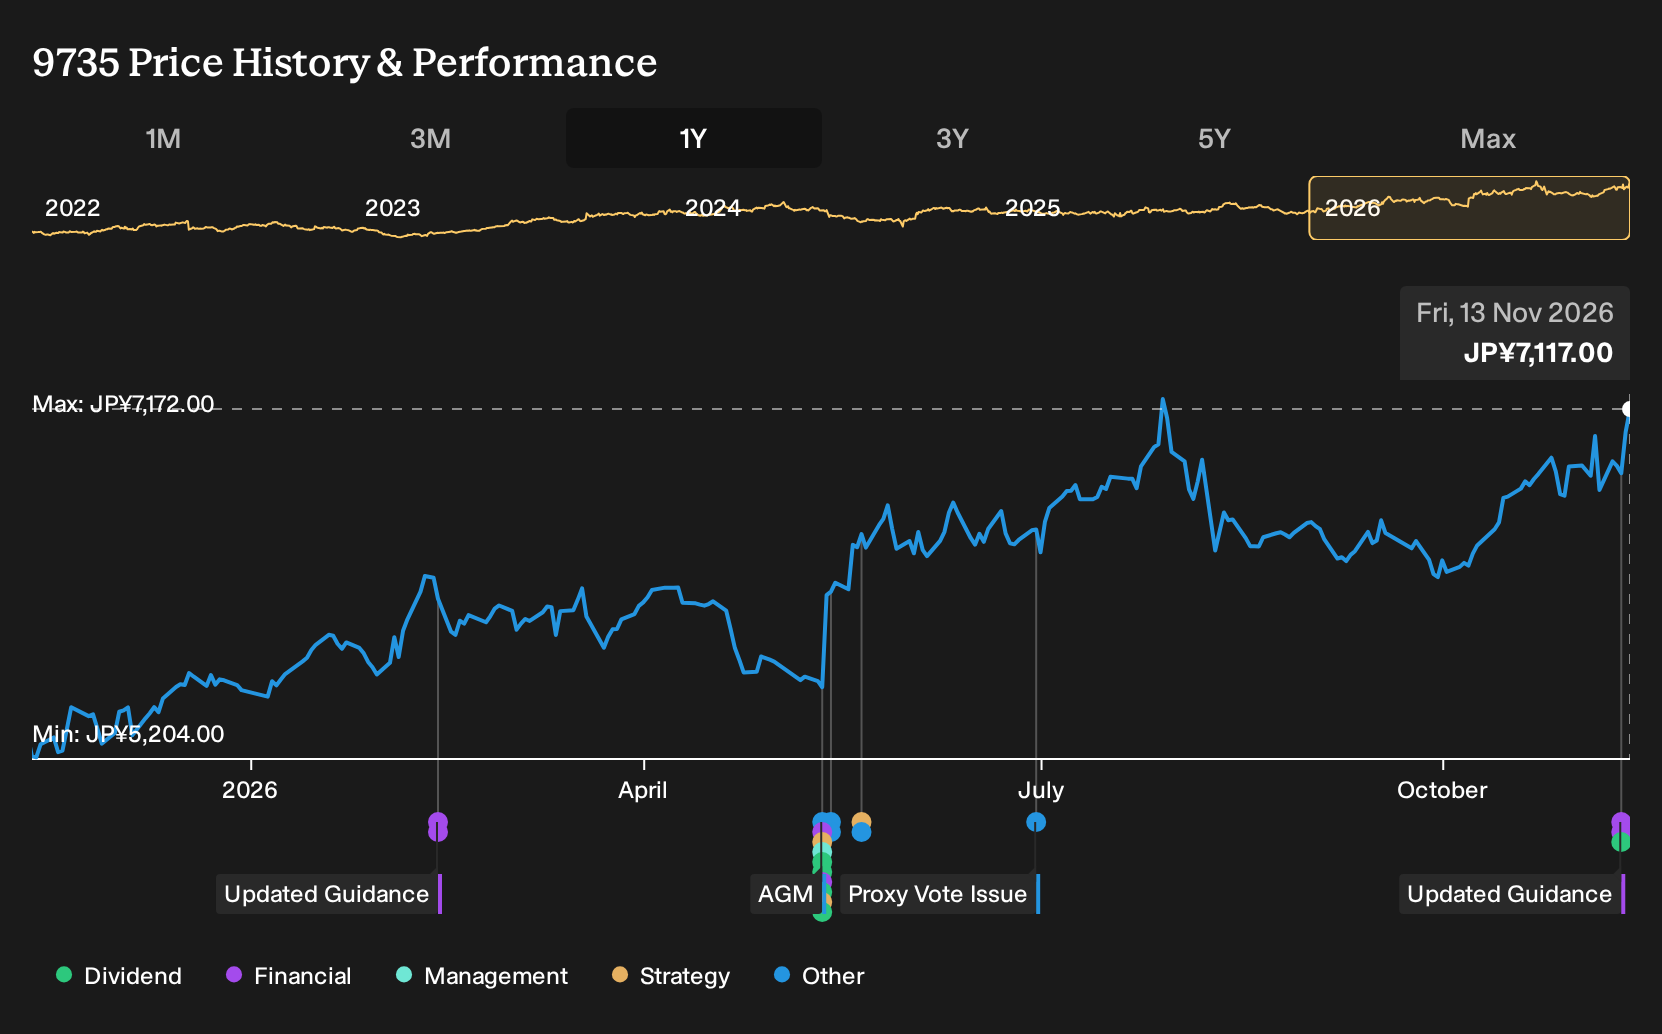
- SECOM reported half year results to September 30, 2026 with sales of JPY 587,444 million and net income of JPY 55,270 million, alongside new full year guidance and an interim dividend of JPY 60 per share to be paid from December 9, 2026.
- The combination of higher half year earnings, increased basic EPS from continuing operations and a larger interim dividend indicates management’s confidence in SECOM’s operating performance and cash generation.
- The focus now turns to how SECOM’s higher interim dividend and earnings guidance could influence the broader investment narrative that investors follow.
Scan how SECOM’s dividend and earnings story compares with other income focused opportunities by lining up its profile against a curated 29 dividend fortresses in the market.
What Is SECOM's Investment Narrative?
To own SECOM, you need to be comfortable with a fairly steady, execution driven story. The business leans on recurring security contracts, fire protection installations and a growing mix of medical and BPO and ICT services, so demand tends to track corporate and public sector spending rather than big consumer swings. The new full year guidance, including expected net sales of ¥1,313.5b and profit attributable to owners of parent of ¥105.8b, sets out how management currently views that operational backdrop.
The raised interim dividend to ¥60 per share and higher basic EPS for the half year indicate that SECOM is willing to return more cash when earnings support it. That can be a short term support for the stock if investors continue to treat it as a dependable, income leaning holding. The main near term risks still lie in execution across its many segments, pricing power in core security services and the capital required to keep technology and infrastructure current.
Even so, the picture looks less straightforward once you weigh that against ...
There's only one way to know the right time to buy, sell or hold SECOM. Head to Simply Wall St's company report for the latest analysis of SECOM's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your SECOM research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for SECOM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SECOM's overall financial health at a glance.
Looking For More Investment Ideas Beyond SECOM?
Once you have formed a view on SECOM, it can help to widen the lens and compare it with other listed businesses that fit different roles in your portfolio. The Simply Wall St Screener is built for exactly that kind of side by side research.
- If you want income with an emphasis on resilience, line up SECOM against a 19 resilient stocks with low risk scores that may help balance out bumpier holdings.
- For investors hunting for quality at a measured price, broaden your watchlist with a 72 high quality undiscovered gems that might not yet be widely followed.
- When capital preservation and financial strength are at the top of your checklist, compare SECOM with a list of solid balance sheet and fundamentals (24 results) that can help surface sturdier business models.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com