


EN
What Edwards Lifesciences (EW) Earnings Beat Means For Shareholders
- Edwards Lifesciences reported Q3 2026 sales of US$1,715.5 million and net income of US$307.5 million, raised full year guidance and outlined Q4 sales expectations of US$1.67 to US$1.75 billion.
- Alongside these figures, the company highlighted strong clinical data for its PASCAL and PROGRESS TAVR programs. It also absorbed a US$220.2 million impairment on acquired research and fixed assets.
- We will look at how Edwards Lifesciences' existing investment narrative is sharpened by stronger guidance and new TAVR clinical evidence.
Edwards Lifesciences Investment Narrative Recap
For an investor to stay in Edwards Lifesciences, the core belief is that the structural heart portfolio can keep widening its reach while margins steadily repair. The analyst consensus narrative on Simply Wall St already leaned on procedure volume growth and operating discipline. The raised 2026 guidance reinforces that in the near term, even as nine month net income and margins are weighed down by the large impairment charge.
Right now, the key short term catalyst is execution on TAVR and TMTT volume growth in line with the new sales ranges. The main near term risk is that tariffs, legal constraints around acquisitions and any continued one off charges keep profit margins below the levels analysts are building into their models.
The single announcement that ties the story together is the upgraded full year and Q4 2026 outlook. Higher group sales guidance, tighter TAVR growth ranges and a lifted TMTT target to US$780 to US$790 million link directly to the volume and mix shift catalysts analysts have been watching for.
That said, the US$220.2 million impairment and the earlier compliance requirements around deals show that execution is not only about clinical wins and reimbursement. Investors also need Edwards Lifesciences to manage legal exposure, integration risk and cost discipline so that headline revenue progress converts more cleanly into earnings over time.
Edwards Lifesciences' narrative projects US$8.7b revenue and US$2.3b earnings by 2029, which implies 9.2% yearly revenue growth and an earnings increase of about US$1.3b from US$994.3m today.
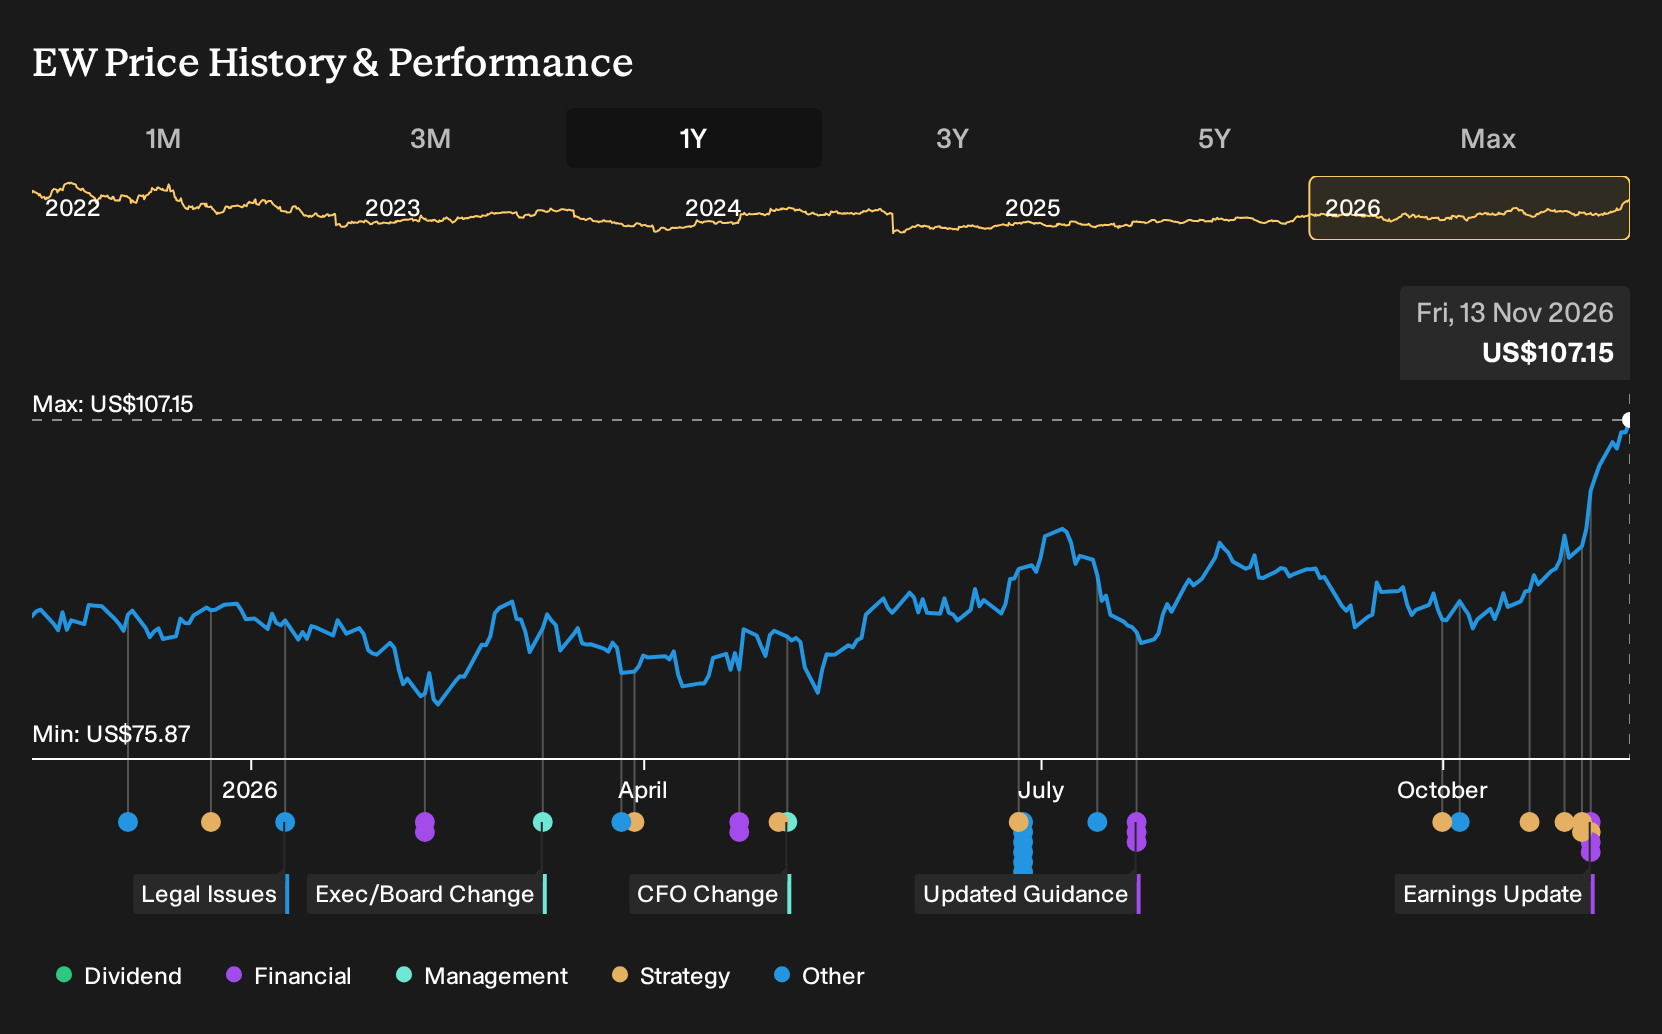
Uncover how Edwards Lifesciences' fair value indicates a 3% potential downside to its current price, suggesting a premium that may not be sustainable.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between about US$104 and US$108, which leaves plenty of room for very different views once the latest Edwards Lifesciences TAVR data, guidance lift and US$220.2 million impairment are reflected. Treat this as a starting point, and compare it with several alternative opinions before deciding how you frame the stock.
Explore another Edwards Lifesciences fair value estimate, including one that suggests it could be worth as much as $108.36.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Edwards Lifesciences research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Edwards Lifesciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Edwards Lifesciences' overall financial health at a glance.
Looking For More Investment Ideas Beyond Edwards Lifesciences?
If the Edwards Lifesciences story has sharpened your thinking about risk, reward and execution, it can be useful to line it up against other opportunities that fit your own criteria. The Simply Wall St Screener lets you filter for balance sheet strength, valuation and income potential so you can see where Edwards Lifesciences sits in a much broader opportunity set.
- Prefer companies where capital strength and fundamentals come first? Start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on financial resilience.
- Looking for potential value where quality and price intersect? Scan a curated 34 high quality undervalued stocks that may fit a more price conscious approach.
- Want income on top of potential capital gains? Review a targeted 6 dividend fortresses that screens for higher yielding opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com